

Not enough businesses are prepared for a downturn
More astute businesses keep an eye on cost productivity, practise balance sheet discipline, and go for aggressive growth plays and proactive M&As.
DESPITE a long run of strong economic growth in Singapore and South-east Asia, the next global recession will have serious effects here.
It's a turbulent world, and Singapore relies substantially on exports to China, the US, Europe and elsewhere, as well as capital flows from abroad.
True, the Republic weathered the global financial crisis a decade ago much better than many other countries, but it was hit harder than some of its neighbours in South-east Asia; its gross domestic product (GDP) growth fell from 9 per cent in 2006 to negative -1 per cent in 2009.
Moreover, many of the traits that cushioned Singapore then offer less of a buffer today. For one thing, its economic growth rate fell 5.6 percentage points between 2006 and last year. In exports, with a 2-percentage-point increase since 2006 in the share of Singapore shipments that go to China, the country is now more exposed to China, where growth has almost halved. An ongoing US-China trade war might further slow the Middle Kingdom's growth. In addition, Singapore's corporate and household debt has risen significantly as a share of GDP, from 112 per cent to 169 per cent.
The combined effect of these structural shifts means that Singapore is more exposed than lower-income countries such as Laos that depend more on domestic demand.
Despite these vulnerabilities, many senior executives in Singapore and South-east Asia have not begun to seriously prepare for a downturn. Bain & Company's recent survey of CEOs and CFOs in the region found that 77 per cent of them expect a severe downturn in the region within two years, yet only 37 per cent expect a severe effect on their own company.
Very few - 20 per cent - have significant actions or plans in place. Our conversations with them suggest that some are loath to even think about cost programmes while they are growing; or they have never weathered a downturn as senior executives. Others are simply overly optimistic or believe they have time to wait.
CRITICAL ACTION
For Singapore's business leaders, then, the critical action is getting ready to seize the moment early, when they have more options. By taking a "future back" approach on what they want their company to look like in five to 10 years, they can use the downturn as an opportunity to achieve future growth through more efficient operations and selective investments when asset prices and borrowing costs are lower.
Bain research finds that well-prepared Southeast Asian companies emerged as winners during and after the last downturn. Headed into the global financial crisis, a group of 200 public South-east Asian companies posted double-digit earnings growth on average, our analysis found.
As soon as the storm hit, performance diverged sharply: The winners, on average, realised a compound annual growth rate (CAGR) of 20 per cent from 2007 through 2009; in contrast, the losers barely mustered a 2 per cent CAGR. What's more, winners locked in gains to grow at an average of 7 per cent after the downturn, from 2012 through 2017; the losers slipped at negative 3 per cent.
Our research reveals key moves by companies that outperformed their peers in four areas: early attention to cost productivity, balance sheet discipline, aggressive commercial growth plays and proactive mergers and acquisitions.
Winning companies focus on cost productivity without cutting muscle. We analysed the cost productivity of 200 public companies in South-east Asia, defining cost productivity as earnings growth less revenue growth - namely, the part of earnings growth attributable to cost rather than revenue.
During the 2007 to 2009 slowdown, winners had a 20 per cent CAGR in earnings, with 10 percentage points of that coming from cost productivity. The losers had just a 2 per cent CAGR in earnings, with cost productivity actually dropping by two points. This divergence continued during the subsequent recovery.
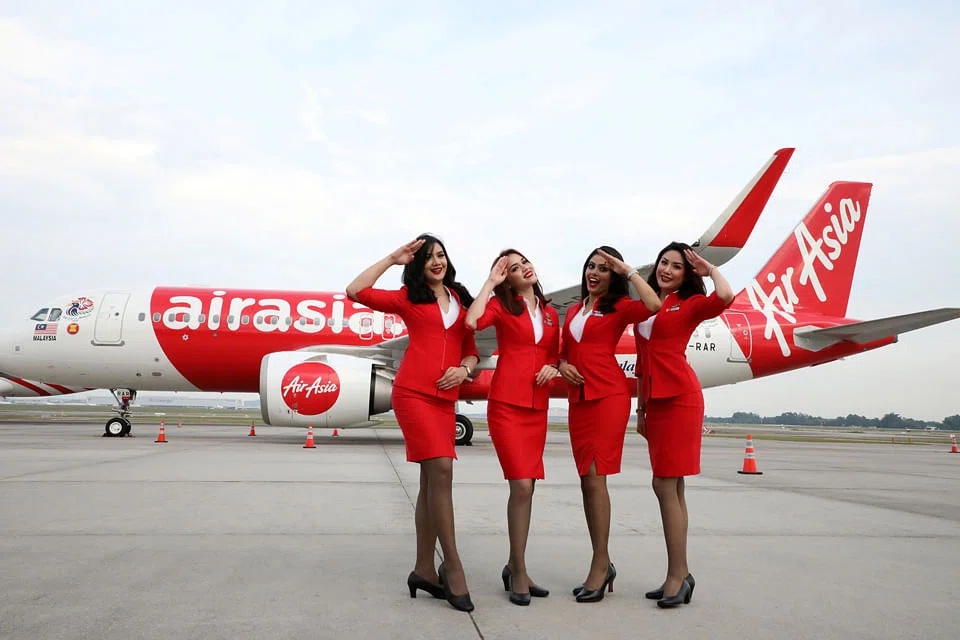
Malaysia-based AirAsia, one of the winning companies, was able to grow revenue and maintain profit margins from 2007 through 2012, far exceeding the overall industry growth rate and more than doubling passenger volume. The airline focused on keeping costs low without degrading service through tactics such as emphasising online channels and shifting to the more fuel-efficient Airbus A320-200 aircraft, which in turn reduced operational complexity as staff had to service only one type of aircraft.
They also put their financial house in order. The winners managed the balance sheet as strategically as they did the profit-and-loss statement. They tightly managed cash, working capital and capex, all to create fuel to invest throughout the cycle.
JG Summit, a leading conglomerate based in the Philippines, generated capital for growth by issuing new stock to the public for its Universal Robina and Robinsons Land subsidiaries in 2006. It took advantage of lower costs of capital and asset prices by making several debt and equity investments: Robinsons Land issued fixed-rate notes in 2009, and United Industrial bought shares in 2008 when the price had fallen by roughly 40 per cent since the boom period.
Winners play offence by reinvesting selectively for commercial growth. Coming out of the last downturn, the strongest companies went on the offence early, while many of their peers focused on survival and waited for the cycle to clear.
AirAsia tripled the marketing budget during the financial crisis and launched a high-profile "One million free seats" campaign to build brand loyalty. It expanded through higher-priced, demand-resilient routes, and increased daily low-cost options to otherwise expensive routes, such as Kuala Lumpur to Singapore. The carrier also launched AirAsia X in 2007 to destinations in Asia, Australia and the US.
PROACTIVE M&A
Finally, they pursue a proactive M&A pipeline. For the well positioned, the last downturn presented a window to use M&A to reshape the portfolio of businesses. Acquirers bought new product lines, customer segments or capabilities at lower prices. Others exited businesses that didn't fit strategically with the company's future.
JG Summit used selective M&A to grow its market share. The Universal Robina unit acquired General Milling's Granny Goose brand and snacks line in 2008. JGS Petrochemicals regained Marubeni in 2007 in order to pursue different strategic alternatives for petrochemical business.
Astute leaders in Singapore and throughout South-east Asia realise the value of preparing for the coming downturn now, even if their companies have not yet felt the pain and are currently focused on managing growth. If past patterns are any guide, their downturn-proof moves will allow them to steal a march on competitors who falter and drop to a trailing position from which they may not recover.
TRENDING NOW
Singapore expects all parties to honour commitments, says PM Wong after Indonesia cuts gas exports
China’s US$3.5 trillion stock rout deepens as profits sink, major stimulus stays elusive

Gas supply cut from Indonesia accounts for less than 2% of Singapore’s daily gas demand: EMA

Singapore’s central gas buyer affirms Indonesia’s role as ‘important partner’ amid export review warning

