Sats-WFS deal: Lack of clarity on funding plan diverts investor focus from merits of acquisition
Some Sats shareholders may wonder if the deal is in their best interests after watching the stock dive this past week

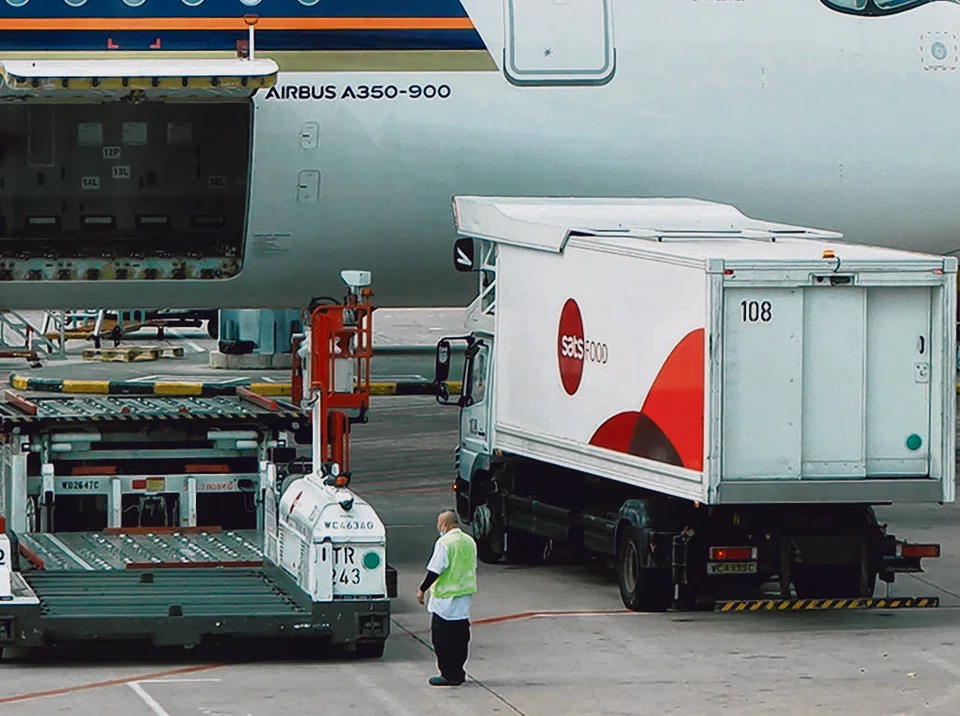
THE board of Sats could not have been unaware that its proposed acquisition of Worldwide Flight Services (WFS) would be met with hostility in the market.
On Sep 21, the inflight caterer and ground handler confirmed a news report that it was indeed discussing a potential acquisition of WFS. The following day – despite some analysts extolling the strategic benefits of such a deal – its shares fell more than 5 per cent.
As it happened, Sep 21 was also the day the United States Federal Open Market Committee hiked interest rates by 75 basis points for a third consecutive time and slashed its estimates of US growth for 2022 and 2023 – which sparked a big sell-off around the globe.
So, when Sats announced this past week that it will acquire WFS at a total cost of 1.3 billion euros (or approximately S$1.8 billion), its board and paid advisers should not have been surprised by the market’s seeming lack of appetite for the deal.
Sats closed Friday (Sep 30) at S$3.01 – down more than 22 per cent since the acquisition was announced on Sep 28; and down more than 26 per cent since the company confirmed media reports about the deal.
Given the skittishness in the market, it seems strange to me that Sats did not state upfront how it will finance the acquisition of WFS.
Instead, Sats said last week that it has secured an “acquisition bridge facility”, but is still evaluating its options on a final funding structure.
The company added that its “base funding plan” involves raising equity capital from its shareholders and new strategic investors. This might include a placement of new shares, hybrid securities or convertible instruments.
Yet, the pro forma financial effects of the acquisition provided by Sats last week are based on the assumption that the company raises S$1.7 billion through a renounceable rights issue of 609 million new shares at S$2.79 each.
This hint that a big, deeply-discounted rights issue is in the offing has very likely added to the downward pressure on the stock, and made it less likely that Sats will now be able to tap strategic investors for equity capital on attractive terms.
Thanks to the lack of clarity on how Sats will fund the acquisition of WFS in a tough market, investors are not focusing on the value the world’s biggest air cargo handler will add to Sats but on how much further Sats’ share price might fall.
Immediate EPS accretion?
Some Sats shareholders may now be wondering if the acquisition of WFS is really in their best interests, and are second-guessing the stated merits of the deal.
In particular, the claim by Sats and its paid advisers that the acquisition of WFS and the deeply-discounted rights issue will immediately result in significant earnings per share (EPS) accretion is being closely scrutinised by some investors.
On a pro forma basis, Sats’ EPS for its financial year (FY) to Mar 31, 2022 would have been 3.2 cents including amortisation of intangible assets; or 5.4 cents excluding amortisation of intangible assets.
Sats’ actual reported EPS for FY2022 was 1.8 cents.
On the face of it, Sats is suggesting the acquisition of WFS will immediately boost its EPS by some 78 per cent after amortisation, and 200 per cent before amortisation.
But some market watchers figure the pandemic might have boosted the air cargo handling business at WFS during the 12 months to Mar 31 even as it weighed on Sats’ overall performance – thus amplifying the pro forma improvement in EPS.
For its FY2022 to Mar 31, Sats reported revenue of S$1.18 billion and earnings before interest, taxes, depreciation and amortisation (Ebitda) of S$94.2 million. This was still well below its FY2020 revenue of S$1.94 billion and Ebitda of S$355.6 million.
By contrast, WFS achieved revenue of 1.72 billion euros and Ebitda of 232 million euros for the 12 months to Mar 31, 2022. This was significantly above the revenue of 1.43 billion euros and Ebitda of 75 million euros it earned in 2019, before the pandemic started.
As the pandemic wanes and profitability at Sats and WFS normalise, the actual EPS uplift from the deal – which is expected to be completed by the end of March 2023 – might turn out to be much lower.
In any case, the acquisition and rights issue will leave Sats with significantly higher gearing. On a pro forma basis, its debt-to-equity ratio as at Mar 31, 2022 would have risen to 71 per cent from 46 per cent.
Its net debt-to-Ebitda ratio would have been 3.4 times instead of 0.5 times.
Conceptually compelling
Still, the acquisition of WFS seems conceptually compelling for Sats.
The company said last week that the “transformational opportunity” will give it a network of more than 200 cargo and ground handling stations in over 20 countries.
The combined group’s network will cover trade routes responsible for more than half of global air cargo volumes.
Sats will also be better positioned to benefit from the growth of e-commerce as well as increasing demand for specialised cargo handling for pharmaceuticals and perishable products.
Sats said it expects the increased scale and geographical diversification of its air cargo business to make its earnings more resilient.
It also sees opportunities to harness synergies that could add S$100 million to the combined group’s Ebitda over the medium term.
More to the point, it seems unlikely that the slump in Sats’ share price will derail its acquisition of WFS. Temasek owns 39.7 per cent of Sats and has provided an irrevocable undertaking to vote in favour of the deal when an extraordinary general meeting is convened.
Until the deeply discounted rights issue everyone seems to be expecting is done and dusted, however, it seems unlikely to me that shares in Sats will recover much.