

Strong will survive as new rules come into play for data centres
Nisha Ramchandani
THE rise of the digital economy and the acceleration of digitalisation thanks to the Covid-19 pandemic have resulted in increased demand for data centres. But the investment premise for data centre assets is under attack.
Late last month, US-based hedge fund manager and short seller Jim Chanos revealed he is raising money for a fund that will short real estate investment trusts (Reits) listed in the United States. In particular, Chanos expects to make money as the prices of data centre Reits falls.
In an interview with Financial Times, Chanos said data centre Reits face “technical obsolescence” because their 3 biggest customers — the Big 3 cloud providers Amazon Web Services, Google Cloud and Microsoft Azure — are also their 3 biggest competitors.
He believes that although demand for cloud services will grow, the cloud providers will take most of the profits in the space.
Chanos’s comments had an immediate impact. Prices of US-listed data centre asset owners Digital Realty Trust, Equinix and Iron Mountain fell by 3 to 5 per cent the day Chanos made his comments.
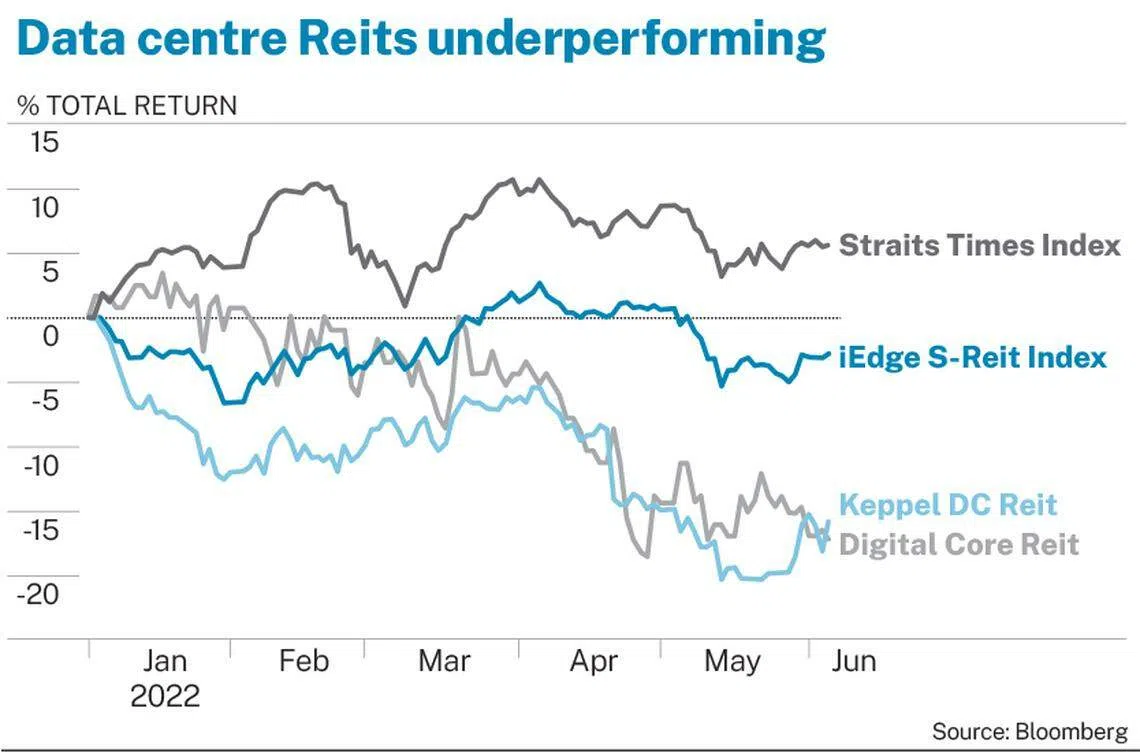
In Singapore, pure-play data centre Reit Digital Core Reit also fell. The counter has been on a downtrend this year, but it hit a low of US$0.73 on Jul 1.
Its peer, Keppel DC Reit , is faring slightly better but is also in negative territory.
In fact, unit prices of both Digital Core Reit and Keppel DC Reit have underperformed the Straits Times Index (STI) and the iEdge S-Reit index. The STI is up 3.5 per cent this year, and the iEdge S-Reit index is down 4.9 per cent. Digital Core Reit and Keppel DC Reit, however, are down about 17 per cent.
Local market analysts, however, are far more positive than Chanos about the market’s prospects.
In a report on Keppel DC Reit, Citi analyst Brandon Lee noted that data centres are still very much in demand even as tech firms have come under pressure this year. Keppel DC Reit is seeing “demand driven by (the) acceleration of cloud migration and increased prominence of cloud computing”. With capitalisation rates remaining stable, Keppel DC Reit could go on to make acquisitions in markets “where yield spreads remain positive, likely Japan, Europe and China in our view”, wrote Citi’s Lee.
DBS analysts Dale Lai and Derek Tan, meanwhile, see Digital Core Reit supported by its long weighted average lease to expire of 5.5 years. This will ensure long-term occupancy and income, the analysts said.
In any case, the Asia-Pacific market appears to have a shortage of data centre space. DBS said in its report that the likes of Amazon, Google and Microsoft “continue to seek new capacity to keep up with their customer growth”.
Land-scarce Singapore is a leading hub for data centres in the Asia-Pacific, as it is seen as a springboard to South-east Asia. Real estate consultancy Colliers calculates there are over 70 operational data centres here with a total capacity of about 1,000 megawatts (MW), run by some 40 operators, though the top 5 data centre operators account for nearly two-thirds (63 per cent) of the total power load. Of the total stock, 4 million square feet (sq ft) is estimated to be lettable white space, delivering some 600 MW of power.
According to Colliers, data centres are able to deliver higher rates of return vis-a-vis most other real estate classes here — as they come with higher operational risks. Against the backdrop of robust demand and limited supply, the real estate consultancy sees rents for data centres climbing north, and expects them to rise about 3 per cent annually on average.
Supply in the Singapore market is tight amid a government-imposed moratorium and after the pandemic derailed construction timelines for new data centres, contributing to high utilisation rates. Analysts say that supply in Singapore will grow by some 20 per cent by the end of next year as fresh supply comes on stream and as the moratorium is lifted.
Earlier this year, the government announced it would remove a moratorium on the construction of new data centres, albeit with the imposition of certain criteria linked to sustainability. With fighting climate change high on the Republic’s agenda, the moratorium was introduced in 2019 as the authorities sought to manage the growth of the market and curb emissions. A Bain & Co report forecasts data centres will account for 12 per cent of Singapore’s power consumption by 2030.
Under the pilot phase, which will commence this year, up to 3 data centres of 10 to 30 MW capacity will be approved as 60 MW of capacity is split among a maximum of 3 operators. Other criteria include a 10-year-lease tenure and a power usage effectiveness (PUE) of 1.3 or under: criteria which some industry players admittedly have been less than enthusiastic about, citing cost inefficiencies and a short lease tenure. (The PUE is a ratio that measures the energy efficiency of a data centre - the lower the better.)
Amid more stringent regulations, data centre operators equipped with the financial muscle and operational experience will ultimately be the ones that will succeed in the new landscape.






