

US office S-Reits will need to diversify tenant mix in response to work-from-home trend
Jude Chan
REAL estate investment trusts (Reits) that own office properties in the United States are going through a rough patch that could be a precursor to monumental change.
Most Singapore-listed real estate investment trusts (S-Reits) are riding on the reopening of economies post-pandemic, while bracing for higher interest rates and higher inflation.
But S-Reits in the US office sub-sector are fending off macroeconomic headwinds on the one hand, while grappling on the other with an uncomfortable reality: Workers in the land of the free have become so used to working from home during the pandemic, they are refusing to return to the office.
“We thought they would come back, but we are taken aback that they are not back,” said Caroline Fong, Manulife US Reit’s chief investor relations and capital markets officer, at a recent briefing accompanying its second quarter results announcement.
“For Americans, it’s all about freedom. No employer has so forcefully said ‘you have to come back’, because they may be sued.”
Manulife US Reit reported physical occupancy of just 28 per cent across its portfolio as at Jul 11, improving from physical occupancy of 25.3 per cent in the first quarter. (Physical occupancy is the estimated number of people physically occupying the building. It is a different measure from portfolio occupancy, which reflects tenancy.)
According to Kastle System’s Back to Work Barometer, average physical occupancy across 10 major US cities hovered around 44 per cent in mid-July.
All 3 US office S-Reits – Manulife US Reit, Prime US Reit and Keppel Pacific Oak US Reit (KORE) – reported positive rental reversions for the latest period. But with the move towards hybrid work arrangements, some challenges are surfacing on the leasing front.
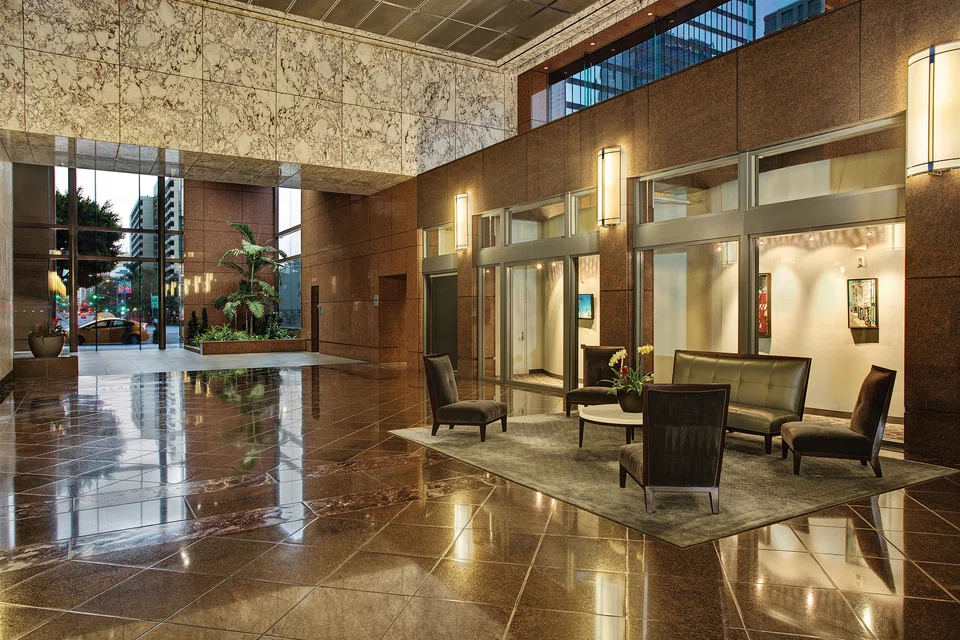
At its results briefing, Manulife US Reit disclosed that 2 major tenants are giving up space at its Figueroa asset – a Grade A office building in Los Angeles.
TCW Group, a finance and insurance tenant that has been at Figueroa since the completion of the building in 1991, will be vacating its space when its lease expires in December 2023.
The Reit manager said TCW will be giving up the net lettable area (NLA) of 188,835 square feet (sq ft) “to avoid major renovation”.
Meanwhile, Quinn Emanuel Trial Lawyers is cutting its space by more than half. The legal tenant is downsizing its current 135,003 sq ft space by 71,000 sq ft effective end-August, while renewing the remaining 64,000 sq ft for another 5.4 years starting September.
TCW and Quinn Emanuel are the 2 largest tenants at Figueroa.
TCW is also Manulife US Reit’s second-largest tenant across its entire portfolio, accounting for 3.8 per cent of gross rental income (GRI).
Quinn Emanuel, currently the seventh-largest tenant portfolio-wide at 2.9 per cent of GRI, will account for 1.4 per cent of Manulife US Reit’s GRI post-downsizing.
Similar news was delivered at the results briefing of Prime US Reit – professional services company Whitney, Bradley & Brown (WBB) has not renewed its lease, which expired in July.
WBB was Prime US Reit’s ninth-largest tenant portfolio-wide, contributing to 2.6 per cent of the Reit’s portfolio cash rental income (CRI) as at end-June.
It occupied 73,511 sq ft of Reston Square – a 6-storey Class A office building in Virginia, which has a total NLA of 139,018 sq ft – and its departure will bring the occupancy rate of the formerly fully occupied building to less than 50 per cent.
Such departures do not bode well for the US office S-Reits, whose portfolio occupancy rates have already dropped significantly since the start of the pandemic.
Prime US Reit’s portfolio occupancy was 89.6 per cent at end-June, down 6.2 percentage points (ppt) from 95.8 per cent at end-2019 – before the start of the Covid-19 outbreak.
Manulife US Reit reported portfolio occupancy of 90 per cent in the latest period, falling from an occupancy rate of 95.8 per cent at the end of December 2019.
Over the same period, portfolio committed occupancy at KORE has dipped 1.6 ppt – to 92 per cent at end-June, 2022.
On the face of it, occupancy rates at other pure-play office S-Reits with assets outside the US appear to be dwindling as well.
Elite Commercial Reit , which listed on the Singapore Exchange (SGX) in February 2020, reported an occupancy rate of 98 per cent at end-June. The Reit’s initial portfolio of United Kingdom properties was fully occupied at end-August, 2019.
Keppel Reit , which owns mostly Singapore properties but also owns some assets in Australia and South Korea, posted portfolio occupancy of 95.5 per cent at end-June – falling from 99.1 per cent at end-2019.
Nevertheless, the duo are unlikely to face the same headwinds as the US office S-Reits as a result of changing work patterns.
Over 99 per cent of Elite Commercial Reit’s portfolio is leased to the UK government, while physical occupancy at Keppel Reit’s Singapore-majority assets is seen to be healthy.
Manulife US Reit’s Fong suggested this could be because Singaporeans are more tractable, and have returned to the office when employers or the government said they should do so.
To help mitigate the impact of lower physical occupancy, Manulife US Reit said it is exploring a concept called the “hotelisation” of its office assets. The Reit is looking to partner operators to offer flexible workspace in its buildings, which will allow existing and prospective tenants to expand and contract as needed.
The Reit manager said this could include increased “experiential offerings” and common spaces, which will make its buildings a more “fun” and “comfortable” place to work.
It is exploring this hotelisation concept at its Michelson building in Irvine, with the possibility of turning the rooftop of the building into a space for F&B. Other ideas include converting the low floors into amenities such as gyms and lounges, and introducing outdoor chill-out areas.
Any potential turnaround, however, will not be witnessed immediately.
The Reit manager said it could immediately bring in operators to start the hotelisation transformation. But it conceded that, with the need for some asset enhancement works, any financial uplift that may be garnered from this hotelisation will only kick in from FY2023.
Manulife’s proposed shift in product mix is not new.
Capital Tower, a Grade A office tower in Singapore’s central business district that is owned by diversified S-Reit CapitaLand Integrated Commercial Trust (CICT) , offers flexi-workspace options as well as a suite of business facilities such as auditorium and conferencing facilities. The building also houses a club fitness centre as well as some F&B and retail outlets.
Meanwhile, CICT’s CapitaSpring office tower literally shares the same address as the Citadines Raffles Place Singapore serviced residence. The latter also comes under the CapitaLand group umbrella.
In a recent interview with The Business Times, Tony Tan, chief executive officer of CICT’s manager, noted that integrated developments with a combination of office, retail and lodging spaces under one roof could become more common in Singapore in the future.
Manulife US Reit’s hotelisation idea may therefore be a step in the right direction – and the Reit manager deserves kudos for attempting to arrest the problem of falling physical occupancy rates.
In the face of the changing landscape in the wake of the pandemic, the US office S-Reits may need to diversify to survive. And they will need funding to do so.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Seatrium allocates S$200 million for new share buyback programme

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026
Stocks to watch: Mapletree Logistics Trust, Seatrium, Keppel DC Reit, Food Empire

