Merits of Mapletree merger must be seen through longer-term lens
AS the world prepared on Dec 31 (Friday) to join in a chorus of Auld Lang Syne to welcome the new year, the managers of Mapletree Commercial Trust (MCT) N2IU and Mapletree North Asia Commercial Trust (MNACT) RW0U were singing a different tune.
The 2 Mapletree-linked real estate investment trusts (Reits) proposed to merge in a S$4.2 billion deal that will see the combined entity leapfrog its way to become the seventh largest Reit in Asia with a theoretical market capitalisation of S$10.5 billion.
To be named Mapletree Pan Asia Commercial Trust (MPACT), the merged entity will have assets under management (AUM) of approximately S$17.1 billion - combining MCT's 5 Singapore assets with MNACT's 13 properties in China, Hong Kong, Japan and South Korea.
The terms of the trust scheme are straightforward enough and, unlike many of the other Reit mergers, have at least tried to use fair benchmarks for valuations.
MNACT unitholders are to receive a scheme consideration of S$1.1949 for each MNACT unit held. They can elect to receive either 0.5963 new MCT unit at an issue price of S$2.0039 apiece, or a combination of 0.5009 consideration unit and S$0.1912 in cash.
The scheme consideration price of S$1.1949 is in line with MNACT's net asset value (NAV), and represents a 7.6 per cent premium to MNACT's trading price on Dec 27 and a 17.3 per cent premium to its 12-month volume-weighted average price.
For MCT unitholders, the merger will be 8.9 per cent accretive to distribution per unit (DPU) and 6.5 per cent accretive to NAV on a pro forma basis. The scheme issue price of MCT units is at a 19.3 per cent premium to ex-distribution NAV per unit and is equal to MCT's 1-day volume weighted average price on Dec 27 - just before the deal was announced.
Some MCT unitholders, however, are not too pleased about the proposed merger. Their exasperation is understandable.
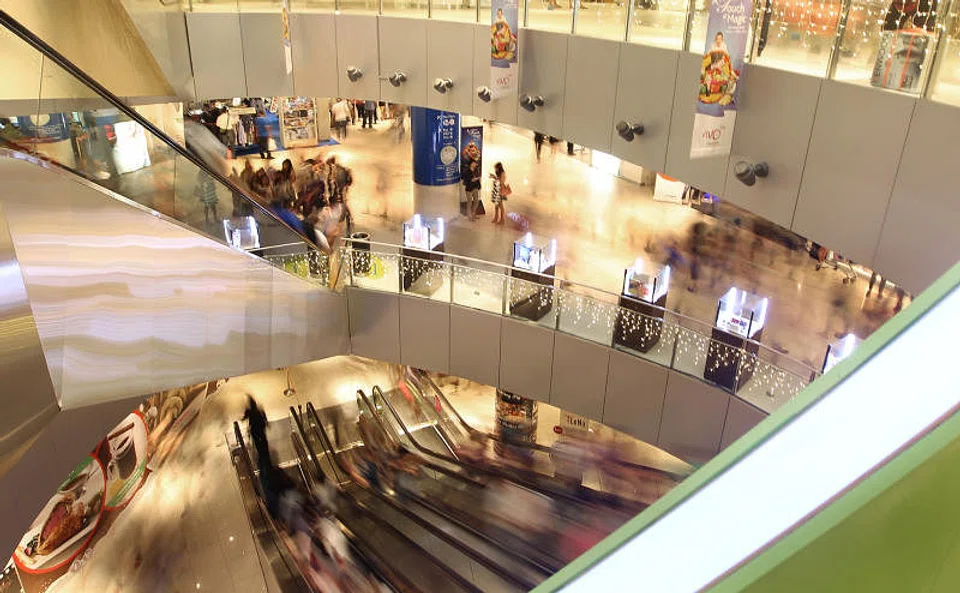
MCT has been a stalwart among the Singapore-listed real estate investment trusts (S-Reits). The pure-play Singapore commercial real estate player, which owns Mapletree Business City I and II as well as Singapore's largest shopping mall VivoCity, has clocked an annualised total return of 12.9 per cent in the 5 years running up to the announcement of the proposed merger.
MNACT, on the other hand, has been struggling with underperforming assets. Over the same 5-year period, MNACT registered an annualised total return of 9.9 per cent.
MNACT's biggest asset, Festival Walk in Hong Kong, had suffered extensive damage due to street protests in November 2019. When it reopened in January 2020 following repairs, Covid hit.
Investors have given the Reit managers a clear indication of what they think of the proposed merger.
On Jan 3, the first trading day after resumed post announcement of the merger, units of MCT tumbled 4 per cent or S$0.08 to S$1.92 - the lowest level since November 2020.
Conversely, units of MNACT jumped 3.6 per cent or S$0.04 to a 21-month high of S$1.15 on Jan 3.
From the point of view of Mapletree, however, now is as good a time as any for the proposed merger.
MCT registered a total return of negative 1.8 per cent in 2021, ranking it among the bottom 10 S-Reit performers. Meanwhile, MNACT saw a total return of 22 per cent last year.
If the Covid-19 pandemic has taught us anything, it is the importance of diversification.
With a Singapore-focused investment mandate, MCT stands the risk of becoming a victim of its own success.
It has lagged its peers in driving inorganic growth due to the limited number of commercial properties in Singapore - including under its sponsor's pipeline - that are attractive enough for a high-performing Reit.
While MCT has done well so far, the question is where the longer-term growth is going to come from.
One of the key merits of the proposed merger would be an investment mandate that will be expanded geographically to include other key Asian gateway markets.
MPACT is expected to have a gearing ratio of 39.2 per cent as at Sep 30, 2021, on a pro forma basis, translating to a debt headroom of S$3.8 billion.
Post-merger, the first order of business for MPACT would be to make acquisitions in the markets where MNACT is present.
While MCT's Singapore properties will account for 51 per cent of the enlarged portfolio, this is expected to go down further as MPACT acquires more assets outside of the city-state.
MPACT is also expected to lower the proportion of its retail assets, which will stand at 46 per cent post merger, while adding more business parks and office assets.
While the merger may seem less than fair to MCT unitholders, the rationale is one that looks at the longer term. To put it simply, the merger could be the only way for MCT to diversify and grow.
This is critical as the Reit positions for the next chapter in a post-Covid world. Perhaps, the time may eventually come for the rest of Mapletree's Reits to be merged too.
Also in the group's umbrella are Mapletree Industrial Trust ME8U and Mapletree Logistics Trust M44U - 2 sectors between which the line has become increasingly blurred.
While the strengths of MCT invariably invokes nostalgia and fond memories, the merger into MPACT represents the moving forward of the Reit into a new era as we leave Covid-19 behind. Auld Lang Syne, indeed.
READ MORE
- Mapletree Commercial Trust, Mapletree North Asia Commercial Trust propose merger
- Mapletree merger not win-win for MCT unitholders
- Hot stocks: MCT down 3%, MNACT rises as much as 3.6% on proposed merger