

Where will the new oil be found to meet demand?
The data will determine whether an oversupplied market will continue to depress oil prices into the future.
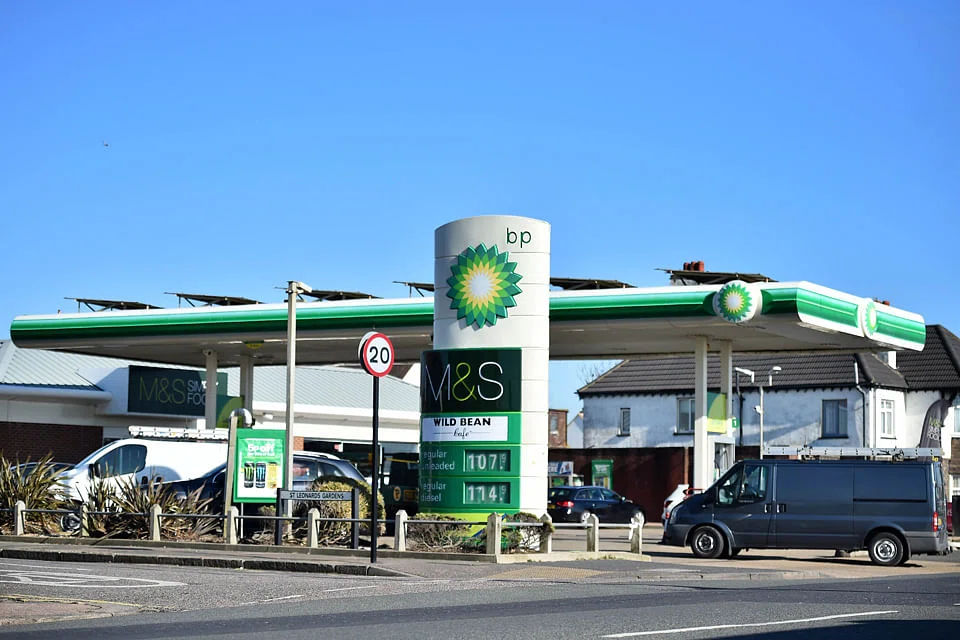
IN 2008, Canadian economist Jeff Rubin stunned the oil market with a bold prediction: With the world economy growing at 5 per cent a year, oil demand would grow with it, outpacing supply, thus lifting the oil price from US$147 to over US$200 a barrel.
The former chief economist at CIBC World Markets was so convinced of his thesis, he wrote a book about it. Why the World is About to Get a Whole Lot Smaller forecast a sea change in the global economy, all driven by unsustainably high oil prices, where domestic manufacturing is reinvigorated at the expense of seaborne trade and people's choices become driven by the ever-increasing prices of fossil fuels.
In the book, Mr Rubin dedicates an entire chapter to the changing oil supply picture, with his main argument being that oil companies "have their hands between the cushions" looking for new oil, since all the easily recoverable oil is either gone or continues to be depleted - at the rate of around 6.7 per cent a year (IEA figures). "Even if the depletion rate stops rising, we must find nearly 20 million barrels a day of new production over the next five years simply to keep global production at its current level," Mr Rubin wrote, adding that the new oil will match the same level of consumption in 2015 as five years earlier in 2010. In other words, new oil supplies can't keep up with demand.
TRENDING NOW
Companies still in search of AI use cases with worthwhile ROI, says Broadcom’s CEO
Beauty World Plaza up for collective sale for S$165 million
Trouble in paradise: Bali runs low on fuel, sparking long lines at pumps
Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion

