

Danger ahead! Five examples of risky central bank politicisation
These instances are far from guaranteed outcomes in the US, but they show where excessive political interference in monetary policy can lead
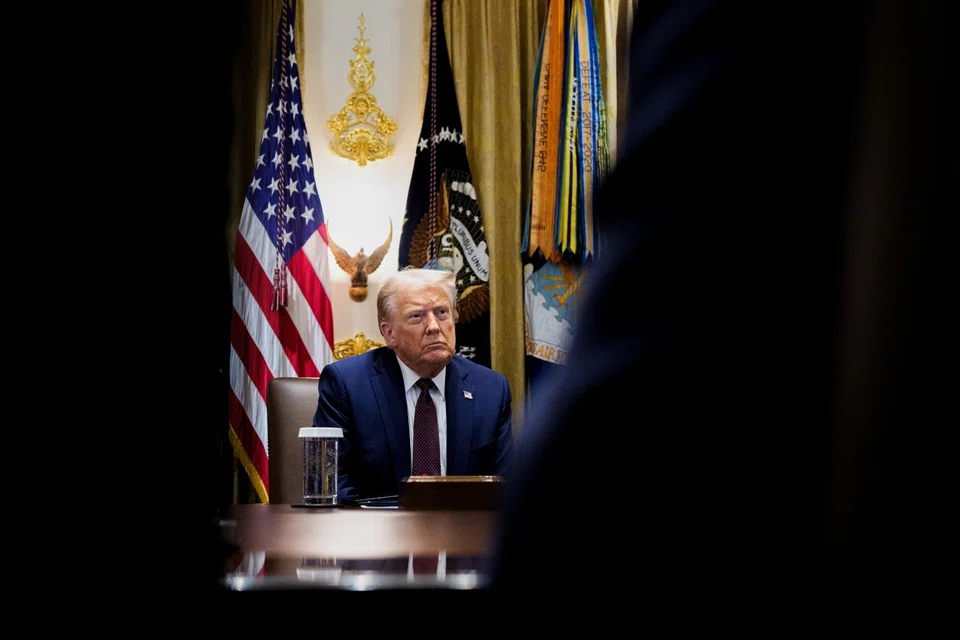
THERE is legitimate debate about the actual independence of modern-day central banks, but almost everyone agrees that overt politicisation of monetary policy – as we appear to be seeing in the United States – is dangerous. Why is that?
Central banks are essentially arms of government, and many worked in close conjunction with national treasuries in response to the global financial crisis and Covid-19 pandemic, so absolute independence is a bit of a myth.
But what US President Donald Trump is currently doing goes well beyond that. By threatening to fire chair Jerome Powell, actively trying to sack Governor Lisa Cook, and attempting to fill the board of governors with appointees sympathetic to his calls for lower interest rates, he is shattering the Fed’s veneer of operational independence.
Examples of the naked politicisation of monetary policy down the years show that it can, to put it mildly, deliver sub-optimal results – loss of credibility, currency weakness, spiking inflation, rising debt, elevated risk premiums, and, potentially, much higher borrowing costs.
These are certainly far from guaranteed outcomes in the United States, but they show where excessive political interference in monetary policy can lead.
Turkey
“Erdoganomics”, the unorthodox economic theories and policies of Recep Tayyip Erdogan, who has been president of Turkey since 2014, are a prime example of politicised monetary policy.
Erdogan, an avowed “enemy” of interest rates, is on record as saying high interest rates cause inflation, and that the way to reduce inflation is therefore to lower borrowing costs.
He fired or replaced five central bank governors between 2019 and 2024, some for hiking interest rates or refusing to cut them.
With inflation and interest rates hovering around 20 per cent in late 2021, the central bank succumbed to Erdogan’s pressure and slashed borrowing costs. The result? The currency collapsed and inflation soared above 85 per cent.
Argentina
Few central banks in the modern era have so clearly been de facto arms of government as Banco Central de la Republica Argentina (BCRA).
Successive governments have leaned heavily on the BCRA to print money to fund their spending, with predictable results. The country has been in and out of economic crises, and battling high, or even hyper, inflation for decades.
The tenure of a BCRA president tends to be short: There have been 13 BCRA heads this century. And there were seven in the first seven years of Carlos Menem’s presidency between 1989 and 1996.
Former president Cristina Fernandez de Kirchner also notoriously fired BCRA chief Martin Redrado in 2010 because he opposed her plan to use US$6.6 billion in foreign exchange (FX) reserves to pay down debt.
India
Pressure on the Reserve Bank of India (RBI) has intensified under the government of Prime Minister Narendra Modi.
In December 2018, RBI Governor Urjit Patel resigned abruptly after just over two years in the job, following months of government pressure to ease lending conditions and allow the government more access to reserves to boost spending ahead of national elections.
In the months before Patel’s departure, Modi also removed RBI board members and appointed his supporters in their place, unnerving investors. This helped push the rupee to a then-record low against the US dollar that October, and annual inflation more than trebled over the following year – 2019 – to nearly 8 per cent.
Japan
The situation here is a bit different – given that Japanese leaders have often been actively seeking a weaker currency and higher inflation – but the cosy relationship between the government and the Bank of Japan (BOJ) has still arguably had a negative impact on the country’s long-term economic health.
The Japanese government and central bank have worked almost as one while completing several FX interventions over the years.
The ties deepened with the roll-out of “Abenomics” in 2012, the economic reforms introduced by then-prime minister Shinzo Abe that included the “three arrows” of fiscal policy, monetary policy and structural reform.
“The magnitude of any market or economic impact from Trump’s political interference could very well be smaller than the ructions of the past. But America’s global heft also means that the worldwide impact of these moves could be much greater. ”
At the heart of Abenomics was unprecedentedly loose monetary policy, even by BOJ standards. The central bank expanded its balance sheet massively – it’s still around six times larger than the Fed’s as a share of gross domestic product – and deployed negative interest rates for years.
Did it work? Many critics argue not, as growth remained sluggish, inequality rose, and Japan is now hamstrung by the world’s largest public debt load.
The United States
Last is, perhaps surprisingly, the United States itself. In the early 1970s, then-president Richard Nixon pressured then-Fed chair Arthur Burns to keep monetary policy loose ahead of the 1972 election, even though inflationary pressures were building.
Nixon also reportedly told Burns in 1969, just after he nominated him, that previous Fed chair Bill Martin was always six months “too late” doing anything. “I’m counting on you, Arthur, to keep us out of a recession,” he apparently said, adding: “I know there’s the myth of the autonomous Fed.”
Burns served as Fed chair for eight years until 1978, during which inflation exploded and did not fully come down until the early 1980s. Many observers consider him to be one of the least successful chairs in the Fed’s history.
It barely needs saying that the United States is unlike any other country. Its economy and capital markets dwarf all others, the US dollar is the world’s reserve currency, and its rates and bond markets are the benchmarks for global borrowing costs.
That means that the magnitude of any market or economic impact from Trump’s political interference could very well be smaller than the ructions of the past. But America’s global heft also means that the worldwide impact of these moves could be much greater. REUTERS






