

Digibank GXS entering consumer loans market at inopportune time
SINGAPORE’S three local banks have just finished reporting their results for the first quarter of this year. No surprise, their net interest margins (NIMs) are still strong.
The higher interest rate environment has allowed the banks to charge more for loans. And although they have also raised interest rates on current accounts and savings accounts, the margin they enjoy is still a significant one.
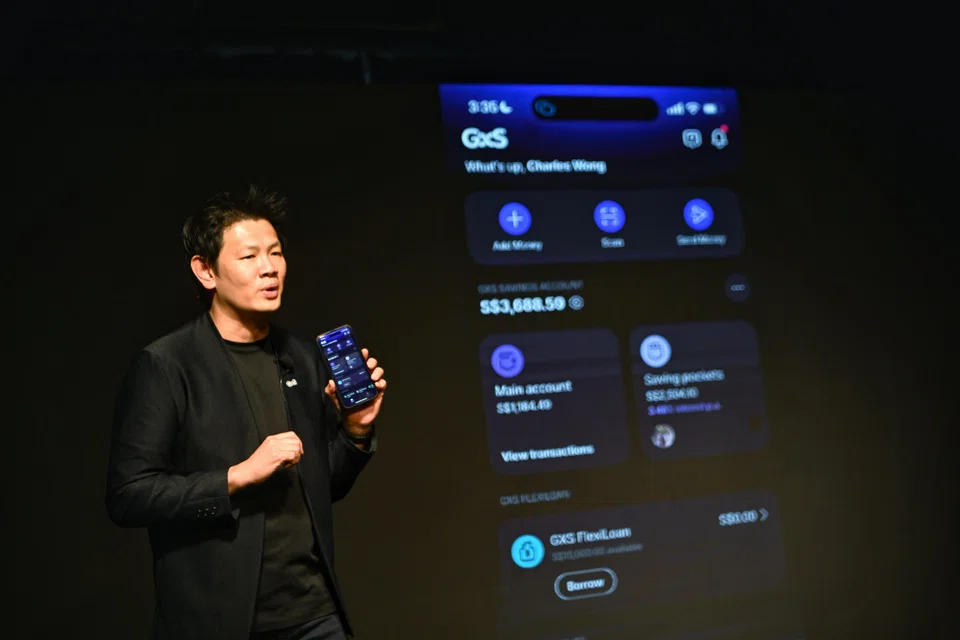
So, when GXS bank announced the launch of its first credit product, a flexible loan offering, it would appear as if the fledgling digital bank is taking the first step towards building a profitable business line.
Yet, the margin on its offering is slim. GXS’ loan starts from 3.8 per cent per annum, while its savings account pays 3.48 per cent. On that basis, GXS would have an interest rate spread of 32 basis points; although on a blended basis, the bank might have a higher rate. (*See clarification note)
It is difficult to compare that spread with the spreads of the other banks, because they have far more products than GXS does. But for simplicity: DBS pays 0.05 per cent on its basic deposit account, and the lowest interest rate charge for personal loans is 3.88 per cent. This works out to a spread of 383 basis points.
Some might argue that it is unfair to make such simplistic comparisons. Indeed, DBS’ NIM is not as high as that. In Q1 FY2023, the group’s NIM was 2.12 per cent. That is still a decent spread. Others might argue that GXS needs to start somewhere, with attractive rates and narrower spreads, to win over customers. But the incumbent banks do this too.
All three offer accounts with tiered interest rates if customers deposit their salaries into their accounts, spend a minimum sum on their credit cards and keep a minimum sum in their accounts. Such incentives serve to lock in the money for the bank and create customer stickiness.
GXS does have one thing going for it – a relatively clean balance sheet that may reassure depositors and investors in the wake of failures at banks such as Silicon Valley Bank and First Republic Bank in the US. But this is little comfort when weighed against the challenges GXS will face in building its asset base in its target retail segment. And not everyone will see GXS’ clean slate as a good thing.
“Trust in the ability of the bank to keep their deposits safe is still a key factor for consumers choosing a bank account – and this trust is not built overnight,” said Alex Kling, associate partner at Bain & Company.
“Incumbents will naturally have an advantage here, making it harder for the challengers to gather deposit share.”
At this point, GXS also has more depositors than it has creditors. This means higher interest rates will hit it harder. Its cost of funding rises faster than its ability to generate interest income.
Meanwhile, Zennon Kapron, director of consultancy Kapronasia, noted that competition for deposits is returning. “(Singapore) is attracting deposits but at a much more expensive rate,” he said.
A peaking of interest rates would help curb such expensive competition. But even then, market watchers, among them Archana Seshadrinathan, expert associate partner at McKinsey & Company, see only “limited upside for net interest margins from the current level”. Margin pressure is likely to continue as the digital banks look set to compete by waiving account and transaction fees, Seshadrinathan added.
Kapron said Australia offers up some lessons for digital banks in developed economies. Both Xinja and Volt collapsed after failing to secure adequate capital. Both were funded by less patient venture capital, whereas Kapron noted that the digital banks in Singapore should have a longer honeymoon period due to their larger corporate backers.
GXS is backed by on-demand platform Grab and telco Singtel. Maribank is backed by e-commerce group Sea. Trust is backed by Standard Chartered Bank and NTUC’s enterprise arm.
Nevertheless, the conclusion may not differ if the newcomers fail to adequately differentiate themselves such that they need not compete only on price. “How long can they continue the experiment before they decide to pull the plug on it?” asked Kapron.
The battle to be sustainable is going to be an uphill one for GXS and its digital bank peers.
*Clarification note: An earlier version of this story stated GXS’ loan charges 3.8 per cent. In fact, 3.8 per cent is the lowest rate. The bank does also pay a lower rate of 0.08 per cent on money that is not placed in savings pockets. Nevertheless, the higher rate of 3.48 per cent is available to any depositor with no lock in and no penalties for withdrawals.
TRENDING NOW

Deal between tycoon friends sparks scrutiny of Philippine power sector

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
China got cool for foreigners. But can they find a job there?

