

‘Dirty’ resources sector needs decarbonisation, not divestment
Sustainability-focused investors must stay engaged to scale up the supply of metals and minerals for the world’s energy transition
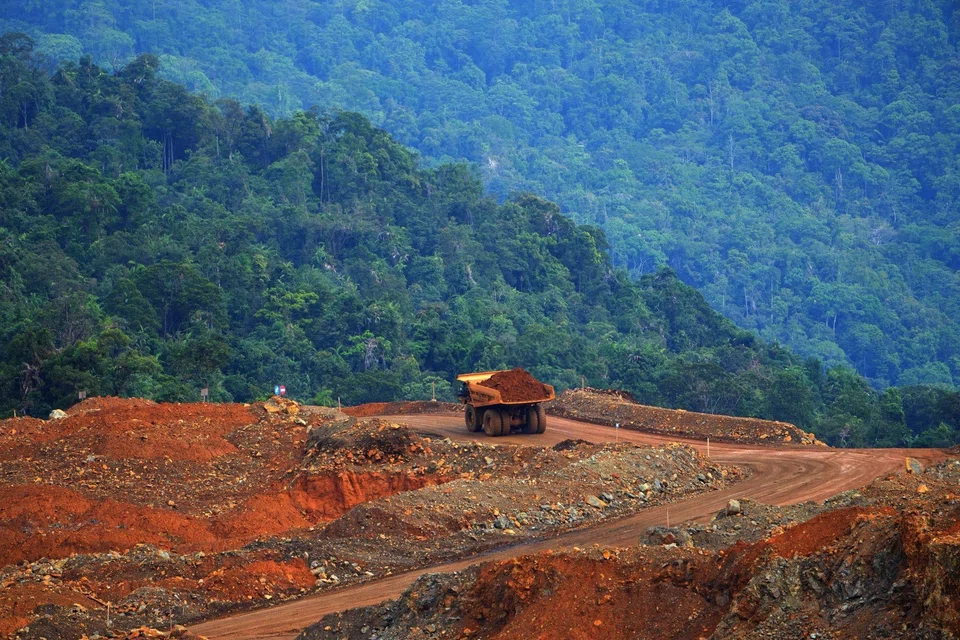
THE metals and mining industry in the Asia-Pacific has a bad reputation among ESG (environmental, social and governance) investors. It is seen as dirty and destructive, or even corrupt and dangerous – at times, it must be said, with good reason.
The resources sector, however, will be crucial to the world’s energy transition. Clean energy technologies require far more lithium, nickel, copper, cobalt and other minerals than their fossil-fuel counterparts – an electric car uses five times more minerals than a combustion engine one, for example – and a supply crunch is looming.
The pathway to net-zero emissions requires immense investment in green technology and infrastructure, all of which will cause global demand for minerals to surge. China alone will need to spend an additional US$17 trillion on green infrastructure and technology in the power and transport sectors to reach its national goal of net-zero emissions by 2060, according to the World Bank.
As Tribeca Investment Partners, we expect demand for lithium to jump more than 40-fold by 2040, while the use of graphite, cobalt and nickel – all critical to electrification and battery storage – will soar at least 20-fold. Benchmark Minerals, a leading resources research group, calculates that at least 384 new mines are needed to meet demand by 2035.
These projections represent an unprecedented opportunity for both investors and the resources industry, but mobilising the investment needed to scale up supply will require some big changes on both sides. Providers of capital need to rethink their exclusionary policies, and resources companies will need to clean up their act.
Divestment does not solve the problem
There are good reasons why sustainability-focused investors must remain engaged with the metals and mining industry. For one, simply exiting from investments in carbon-intensive industries might look good on paper, but it does not achieve anything in the real world. Studies have shown that divesting does not make a meaningful impact on companies’ behaviour.
Divestment could, in fact, worsen the impact of resource extraction on the environment, as assets fall into the hands of companies that are not publicly listed, and therefore are less accountable for the impact on the environment.
Divestment also raises the cost of capital for the resources sector, by making it harder for companies to raise equity or access debt markets. That risks impeding the flow of investment for new projects needed to power clean energy.
Moreover, by remaining engaged, investors have an opportunity to influence strategy. We have seen many examples of investors encouraging boards and management teams to address ESG concerns.
Publicly listed resources companies face greater pressure to decarbonise than unlisted businesses – whether they are privately owned or state-run enterprises. Listed mining companies, in particular, are starting to commit to achieving carbon neutrality by 2050 by repositioning their businesses to operate in a more sustainable manner.
For a mining company, that could mean installing renewable power at extraction sites, converting diesel trucks to electric ones, or shifting operations from coal to gas power.
These steps will not get the world to net zero overnight, but they are important interim measures that will make companies better placed to access capital for more ambitious transition plans in the future.
Climate action is good for business
Within the resources sector, we believe less carbon-intensive metals and mining companies will have a distinct competitive advantage as consumers demand more sustainable products and companies tackle Scope 3 emissions – that is, those associated with their supply chains.
Major United States and European electric vehicle manufacturers, for example, are already looking for battery suppliers that can demonstrate low carbon footprints and high ESG standards.
In Asia, resources companies that can leverage this dynamic by showing leadership on climate and ESG issues will trade at higher multiples and benefit from lower financing costs.
The energy transition is also an opportunity for the region to move up the climate value chain.
Take Indonesia, the world’s biggest producer of nickel. Right now, most of that nickel is exported to China as low-grade pig iron for use in stainless steel. With the right investment, Indonesia’s nickel reserves could be mined more sustainably and processed into higher-value battery-grade exports.
Future regulation, such as Europe’s proposed carbon tariff system, will solidify the connection between carbon intensity and corporate earnings. Finnish oil company Neste, for example, has diversified into developing solutions to combat climate change and is now the world’s largest producer of sustainable diesel and jet fuel. This has helped its valuation rise above its peers to 9.8 times 2024 earnings.
Repositioning resources
Asia’s resources companies have a similar opportunity to parlay bumper profits from high commodity prices to reposition themselves for a net-zero world.
Responsible investors have an important role to play in directing the mining industry towards a more sustainable future. This is why Tribeca is sponsoring Resource Connect Asia’s Future Facing Commodities Forum this year in Singapore.
Metals and minerals are critical to global efforts to tackle the climate crisis – and continued investment will be essential in scaling up the supply of resources needed to power the energy transition. Investors and mining companies need to work together to help the industry transition from a maligned relic of the fossil-fuel age to a key foundation of the future economy.
The writer is head of research for global natural resources strategy and portfolio manager for 2050 strategy at Tribeca Investment Partners.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

From folding clothes to factory work: Why China is sending humanoid robots to school

