

Digital banking meets hard realities in South-east Asia’s emerging markets
Benjamin Cher
DIGITAL banks have sprouted in South-east Asia over the last couple of years, as new and nimble financial players grabbed at opportunities to make a play for “the underbanked”.
Financial inclusion is often cited as a worthy goal, as banks eye new customers out in rural areas. Running a digital network where there are few or no physical bank branches means lower overheads, and digital banks can operate at a fraction of incumbent banks’ expenses.
Governments moved with the new wave. Singapore, Malaysia and the Philippines have given out digital banking licences, while Indonesia has allowed tech companies such as Grab and Sea to buy and transform traditional institutions into digital banks.
Yet, in most markets in which they operate, digital banks have yet to make the kind of impact that they and their investors had envisioned.
Florian Hoppe, partner at consultancy Bain & Company, puts it baldly: “The reason there’s an unbanked population is that they have very little money, and very little access to products. You cannot bank a subsistence farmer, that’s just the reality.”
There is a misunderstanding of what digital financial services can do, he says. “There’s a big chunk of the population in South-east Asia that’s not addressable by digital financial services. There’s just no money, so there’s no economic case for that.”
Sumit Kumar, managing director at consultancy Boston Consulting Group (BCG) agrees, saying there is not a lot of revenue to be gained from that customer segment. Digital banks should instead aim to make banking a different experience for the unhappily banked population in emerging markets, he says.
With typically lower operating expenses, digital players have a cost advantage that they can pass on to customers. Traditional banks’ operating expenses can account for up to 55 per cent of operating income. Digital banks’ costs could be, at most, 35 per cent of their income, Kumar notes.
It’s “the inefficiency of legacy banking” that accounts for that 20-percentage-point cost-to-income ratio difference, he says.
The banking business, however, is significantly more tradition-bound than the “move fast, break things” model that tech companies adopt. A legacy bank’s business model is based on the fundamentals of building up customer deposits and a loan book with low non-performing loans (NPL). Failure is not an option.
Regulators watch the sector like a hawk, and impose rules and requirements that are resolute, with few grey areas to manoeuvre. The last thing regulators want is a bank imploding and sparking off a run on other banks.
Greg Krasnov, founder and chief executive officer of Tonik Bank in the Philippines, understands the situation all too well. The digital bank, operating there since March 2021, started out with a rural bank licence handed out in a regulatory sandbox set up by the Philippines central bank, Bangko Sentral ng Pilipinas.
“People without a deep understanding of banking economics are trying to run their customer acquisition based on digital-economy metrics,” says Krasnov.
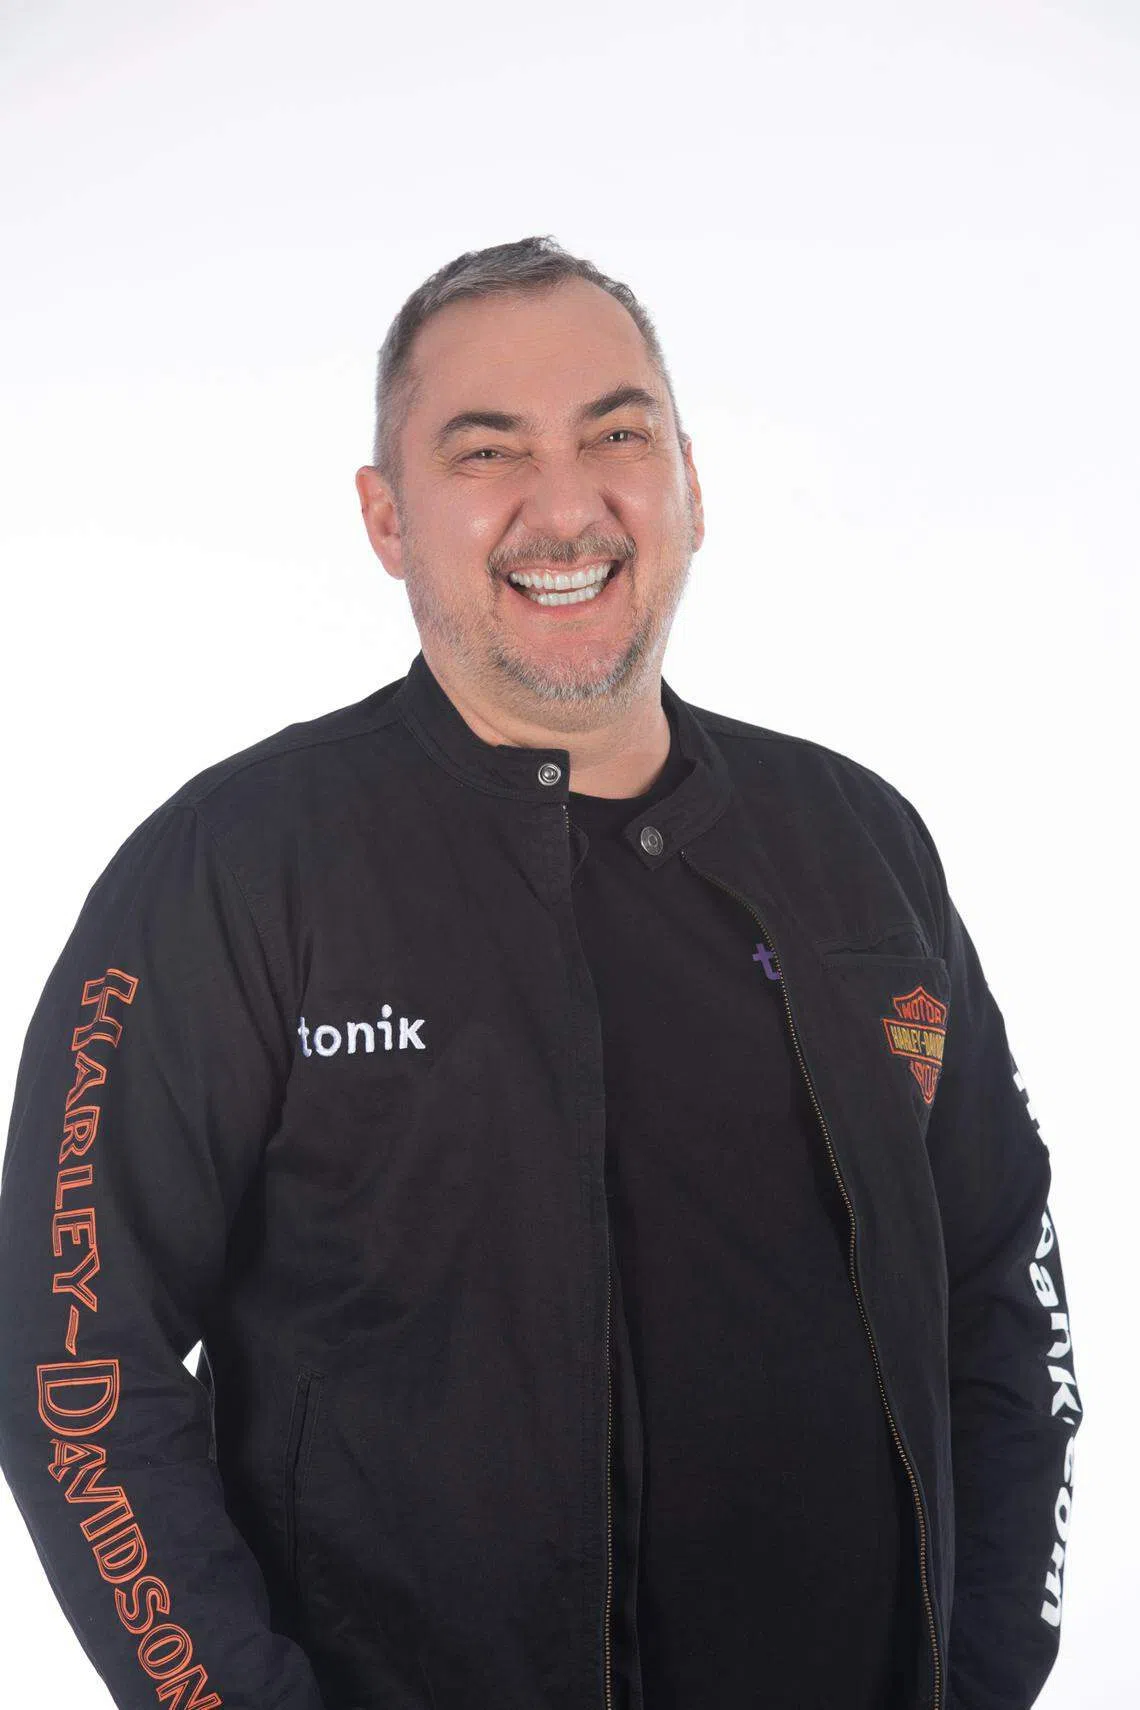
Growing the customer base quickly may not be as beneficial to a bank in the same way that rapid user growth is for a tech company. The number of customers is not as key as credit processes, since loans are the main income stream for banks.
Rather than serve rural villagers on one of the many far-flung islands in the Philippines, Tonik trained its focus on the already-banked. In its first year of operation, it secured US$130 million in deposits and over a million customers – and these numbers barely scratch the surface of the bank-deposit market in the Philippines, estimated at US$300 billion.
“Our average deposit balance right now is about US$1,000 per customer, so these are definitely not the customers taking the money from under the mattress,” says Krasnov.
The reality is that rural areas in emerging markets such as the Philippines suffer from poor or patchy signal coverage outside major cities. Adoption is also hindered by low-level tech. Basic smartphones often do not have enough memory to run Tonik’s app, and users stick to basic services such as messaging and calls, he says.
Digital-native players are finding that customer acquisition has to be done the old-school way – offline.
Going for the offline customer is the recipe for success for GoTyme Bank, also in the Philippines. The bank is a joint venture between Gokongwei Group and Tyme Group, which launched the digital TymeBank in South Africa. Tyme recently relocated its headquarters to Singapore in 2021.
GoTyme’s strategy was to integrate into retail ecosystems, deploying self-service banking kiosks in physical stores, enabling the bank to go after the not-so-digitally savvy customer, says Coenraad Jonker, who chairs Tyme Group.
“To win in emerging markets, you can’t just go after the digitally-savvy customer. You have to go after the full market,” he says.
Offline partnerships have worked well in this regard, says Guillaume De Gantes, senior partner at consultancy McKinsey & Company.
“The big reality on the ground is that a lot of value of the digital transition has accrued to large banks, as opposed to digital banks,” he notes.
Digital banks hoping to thrive in emerging markets will therefore have to partner players with ecosystems to bring customer-acquisition costs down, and to get access to data for credit scoring. Data from utilities payments, for instance, is a better indicator of a credit score than e-commerce shopping habits, says BCG’s Kumar.
He notes that, at current interest rates, the margins digital banks are making would take them five to seven years to break even on the costs of customer acquisition.
If partnerships are the way to go, then the result will be a tussle for such tie-ups, because building a standalone bank is very difficult.
“In the end, partnerships are gold here, because with a partnership comes customer base, data, and, hence, a path to profitability,” says Kumar.
GoTyme Bank launched in October 2022, and now has 2.3 million customers in the Philippines. The bank has a Philippines digital bank licence. (See *Amendment note)
Tyme Group’s Jonker says: “We’ve been blown away by the extent of pent-up demand for our products and services. If you look at the pace at which we see adoption in the Philippines, it really has exceeded our expectations.”
Economics of banking
While there is potential in reaching out to the unbanked, the low deposit amounts mean that a bank targeting this segment would struggle to build up enough capital to give out loans. Lack of data also leaves lenders open to the risk of high NPL numbers, which in turn leads to greater scrutiny from regulators, says Kumar.
Then there is the issue of fraud or identity theft, which happens when loans are taken out in other people’s names. With emerging markets such as the Philippines lacking a national identification system, identity theft is still a big problem, says Jonker.
Tonik offers lending products such as personal loans and in-store lending through partnerships with appliance-store chains such as Automatic Centre and Furniture Store FC Home Centre, and homeware retailer Home Along.
The bank has had to build and constantly calibrate its own proprietary credit-assessment system, which incorporates alternative data such as customers’ data footprint from their smartphones and their behaviour within Tonik’s app.
Two years on, Krasnov says: “You need to take it slow. You need to make sure your risk system is robust and able to handle the differentiation between good and bad. Once you have that confidence, that’s when you really step on it and start scaling.”
This aside, there are rate caps levied by regulators in some emerging markets. The Philippines, for instance, has an effective interest rate capped at 13 per cent per month. In Indonesia, the rate has been capped at between 0.1 per cent and 0.4 per cent per day, depending on the type of loan.
While these limits are for non-bank lenders, banks looking to tap this segment cannot charge higher interest rates than the competition.
“If you think the regulators are constantly reducing the rate cap, it becomes quite unsustainable for anyone to actually go and give lending to this segment, because you cannot afford the NPL and make any money,” says Kumar.
Regulators for now understand that digital banks are not likely to be profitable at the start, but are keeping a close eye on how these banks can turn profitable.
Bain’s Hoppe says digital banks are unlikely to have a major breakthrough in 2024. With incumbents holding large loan books, digital banks are unlikely to displace them anytime soon.
“I think we’re going to start seeing digital banks starting to pick up market share and build a fairly interesting value proposition for a lot of countries,” he says.
Both Tonik and GoTyme still see untapped potential in the region. Tyme is looking to expand into Vietnam this year, with loan products for small and medium-sized enterprises. Tyme’s Jonker is bullish on the potential of South-east Asia, as the demographics, economic growth and level of underserved customers in the market make it a ripe one.
“The profit pools in banking are still very healthy in these markets,” says Jonker.
Progressive regulators are also key to growth, with credit inclusion being the first step, says Tonik’s Krasnov. Providing payment services is not the cornerstone of Tonik’s development in the Philippines; rather, it is an enabler for the bank’s lending and saving products.
“We want our customers to engage with us. Once they are a savings or a loan customer, we want them to stay with us; we want them to do things through our app for a stickier relationship,” he says.
The key to thriving will be managing risks, says Krasnov. After all, banking is still a business that manages risks, rather than take them.
*Amendment note: The article previously stated that GoTyme bank did not have a digital bank licence
TRENDING NOW
Good Class Bungalow market activity picks up pace on ‘realistic’ pricing
Indonesia imposes US$116 million in fines over manipulation of Sinar Mas, Prajogo-linked stocks
Singapore identifies 7 firms responsible for haze fires, notices issued urging action: Grace Fu

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

