

S-E Asia’s startup ecosystem continues to brave funding drought
In this prolonged dry spell, caution is the name of the game for venture capitalists
CHEQUEBOOKS in South-east Asia remain mostly shut, as the startup ecosystem deals with an ongoing funding winter that has lasted over the past two years.
Joe Lu, co-founder of rewards platform Heymax.ai, has his own story of woe that began in 2023. The startup had then just graduated from early-stage venture capital (VC) firm Tenity’s incubation programme, which is focused on fintech.
Heymax.ai had a 10,000-strong customer base and had pivoted into helping users gain air miles; it was time to take the next step.
In the normal course of business, it would have been a cinch to raise seed funding – which is the first round of external funding to get a startup off the ground.
If it had been 2021, investors would have been falling over themselves to put in money. But this time round, they did not respond. Lu says: “We could get meetings, we had initial traction and built a customer base; but investors were kind of waiting on the sidelines.”
Even having four co-founders who had been part of tech giant Meta’s software engineering team could not sway them.
The way investors saw it was, “If we know how to make money, why do we need you?”, laments Lu. “That was a real reflection of the time, when everyone was conservative with their money and (focused on) saving their portfolio companies.”
Not deterred, Heymax.ai continued working on its product and relied on angel investors to spread the word. That helped to convince venture capitalists to step in. Finally, the startup closed a US$2.6 million seed round led by VC firm January Capital in July.
“Combined with the founding team’s experience in large technology companies, we knew from the beginning that they would be able to execute this vision with great finesse,” says Roy Ong, investor at January Capital.
Lu’s problems are not unusual. Funding in the region has fallen to US$1.6 billion in the first half of 2024, a 65 per cent drop from US$4.5 billion in the first half of the previous year, according to a report by data platform Traxcn. This decline was felt across seed- to late-stage startups. It is also a significant plunge from H1 2021’s US$7.9 billion.
The Traxcn report notes that the number of funding rounds have also tumbled to 239 in H1 2024 from 275 in the same period a year before.
Founders struggled to raise money in 2023, according to a survey by venture debt provider InnoVen Capital, with 67 per cent not meeting fundraising goals last year.
Raising money also took longer than expected in 2023, according to 96 per cent of the founders polled, with 67 per cent of them fundraising for more than six months. At the height of the funding boom, this might have taken just weeks.
And, sentiments have not improved much. A substantial proportion of the founders – 46 per cent – believe that the 2024 funding environment will be similar to last year’s. But, 39 per cent are more optimistic and believe that this year’s funding environment will be positive. This is an improvement from the 34 per cent who felt the same in 2023. The uptick could be from seeing some money trickle into startups towards the end of 2023.
Proceeding with caution
Venture capital investors that The Business Times spoke to note that caution is the name of the game among their peers. Global VC firms that had made inroads during the pandemic have also sounded the retreat owing to changes in macroeconomic and geopolitical conditions.
“There is a clear pullback; it’s not that they stopped investing – they want to exit (their investments),” says Neo Weisheng, partner at Singapore-based VC firm Qualgro.
Worsening the dry spell is the fact that VCs too are finding it tough to raise the money needed to back startups they find attractive.
The persistently high interest rates, for one, have led investors to reallocate their capital away from VCs and into asset classes such as fixed income and bonds that generate good returns.
VC firms in South-east Asia are also increasingly getting more questions from their limited partners (LPs) around returns, with the ratio of distribution to paid-in capital (DPI) – a metric that measures how much distribution is paid out – being closely watched.
South-east Asia’s startup ecosystem is not a mature one, and the DPI for more recent 2018 vintage funds is recording a relatively low 13.7 per cent, according to data from insights platform Preqin in January. While funds of that vintage are currently undergoing the liquidation stage, a low DPI does hint at LPs being unable to get their money back to reinvest.
“If no money comes back, then they cannot put more money into work, and that needs to kind of get unclogged before things start flowing again,” says Lim Kuo-Yi, managing partner at local VC firm Monk’s Hill Ventures.
Jeffrey Seah, general partner at MSW Ventures, points out that raising capital in these conditions is certainly no easy task. His VC firm was looking for money last year to invest in early-stage startups with an undisclosed final target. “I can tell you I wouldn’t be able to raise the funds I did if I had gone to the market this year,” he notes.
A report by Preqin shows that over 78 per cent of the VC funds in Asia-Pacific that closed in the first quarter of 2024 took more than 19 months to reach their target sum. For example, AC Ventures’ Fund V raised US$210 million at the final close of the fund in January, missing the targeted US$250 million announced in September 2022.
But there are venture capital firms looking to get financing this year. Australia-headquartered Square Peg will be raising a US$550 million fund in the second half of 2024, its sixth fund. Tushar Roy, a Singapore-based partner at the firm, tells BT that there was no need to increase the fund size in the current market environment.
Square Peg does have a track record of over S$1 billion of returns to investors, putting it in a better place for raising money from LPs, adds Piruze Sabuncu, partner at the firm. “We are in a luckier spot in some ways. We have a very strong relationship with the superannuation funds in Australia; and the other thing we have going on is with the exits,” she notes.
Against this backdrop, VCs have mostly been in portfolio-management mode for a while, looking to save current portfolio companies rather than funding new ventures.
So, even though opportunities have not diminished in the last six months, investors are getting pickier about what and who they will back. Blockbuster deals with funding going into the hundreds of millions are almost unheard of in South-east Asia now.
VCs are no longer investing into hope, says Qualgro’s Neo, but instead need more conviction before entering into a deal. “People are holding on to their investments just because there are just not enough good deals that make sense to them.”
Profitability as a key metric has been a focus for VCs for a while now, ever since the start of the funding winter in 2023. Now it seems that founders are also reframing the key metrics that are presented to potential investors to include profitability.
This might not be a good thing for venture capital firms, as startups will likely have slower growth, which in turn slows down fund deployment for VCs, notes Sabuncu.
What can you offer?
Even as VCs are being cautious about who they are backing, some founders too are becoming selective about whose money they are willing to take, and how much equity can be divvied out to VCs.
They can afford to do this because their startups remain attractive to investors because of their good business fundamentals. But this makes it more difficult for VCs to get into their funding rounds, points out Neo.
Jay Lim, founder of Gopizza, a food-tech startup selling pizzas, tells BT that with each funding round, he made more strategic choices when picking investors, preferring those who would enable his company to expand. But, he adds, it helps that his business has been growing, which has allowed him to be more selective.
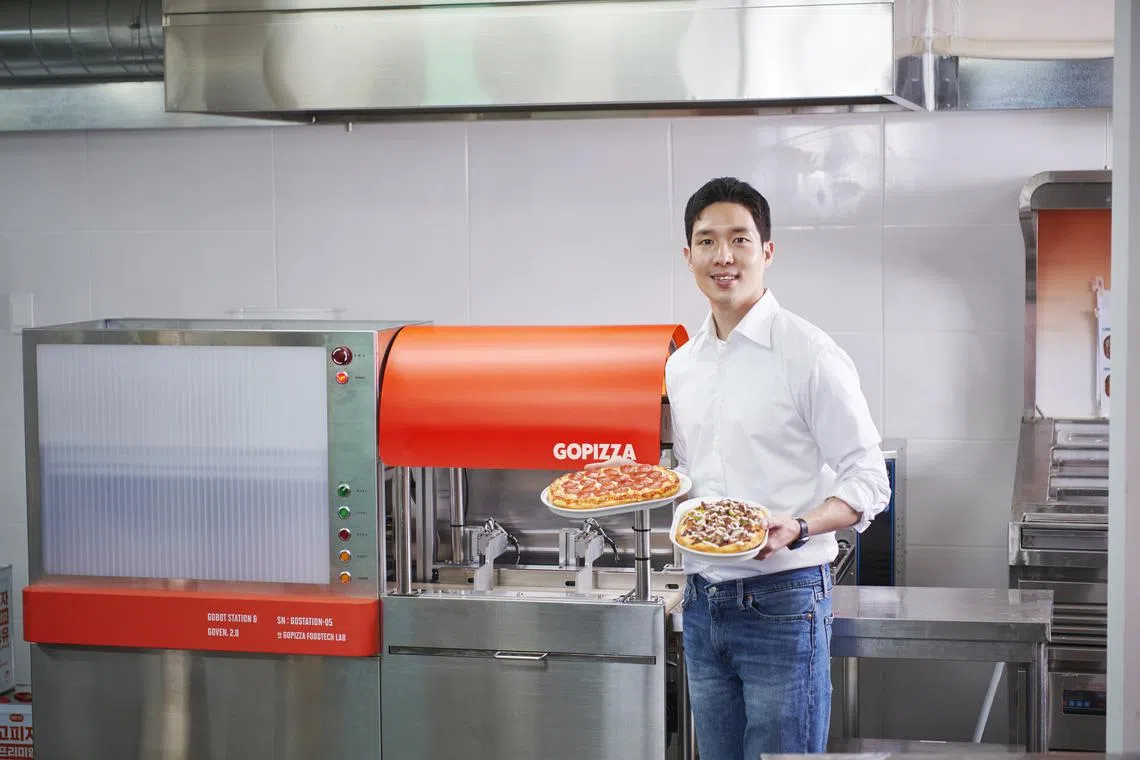
In Gopizza’s Series C round, it succeeded in getting the investment arms of Korean conglomerates CJ Group and GS Group as backers. The startup could thus leverage CJ’s food business and GS’ convenience-store network to scale up in South Korea.
Gopizza also recently closed a US$10 million funding round with Thai conglomerate CP Group’s convenience-store subsidiary CP All. It was another investment round that was of strategic benefit, as the pizza company can tap CP’s frozen-food business to scale up production expertise.
“It was a round only for them; we knew what we could do with CP if they got on board,” says Jay Lim.
Founders have highlighted that support or value-add from investors are now the most important factor in choosing lead investors, according to the InnoVen report. In 2023, 68 per cent of founders said that it was the most important factor, followed by strategic fit at 62 per cent. In 2022, the factors were flipped, with strategic fit as the most important factor at 67 per cent and value-add and support at 56 per cent.
The brand name of VCs is waning in importance, with just 31 per cent of founders seeing it as significant in 2022, and that figure falling to 23 per cent in 2023.
Still, there is a bigger question that looms over both founders and VCs: Can South-east Asia produce the exits needed to generate returns?
Exits, where art thou?
There have been a couple of very big exits in the region, with the listing of Grab and GoTo reaping billions for their investors in 2021 and 2022, respectively. Yet in the subsequent years since, there has been a distinct dearth of exits here.
Currently, the majority of exits in the region are through mergers and acquisitions (M&A) rather than by the traditional route of initial public offerings with larger companies in the US and Europe buying out startups.
But Neo thinks that even these exits are unlikely to pick up any time soon. For companies to execute an M&A deal, both the stock prices and balance sheets have to be in a strong positions, and there has to be positive sentiments that there are growth markets outside of the US and Europe.
“When you have all these three factors you have a strong M&A market; but right now all three factors are not very present, and so we don’t have a very strong M&A market,” he explains.
Also, exits need late-stage investors, of which there is a lack in South-east Asia. This means that while there is more funding at the seed level and Series A and B levels, there is a gap in the funding of late-stage startups raising Series C and above rounds after global VCs pulled out, notes Monk’s Hill’s Lim. For the region’s startup ecosystem to mature, there will need to be exits in a consistent systematic way, he adds.
The next six months will probably remain tough amid macroeconomic uncertainties. But, some VCs are optimistic about opportunities in this period.
Square Peg’s Sabuncu sees potential in companies that raised funds in 2021 and will likely need more money again soon. These firms have hopefully improved their revenue and margins, she notes, which should make raising funds an easier process.
The less frothy and more rational funding environment could also help both startup founders and investors separate the wheat from the chaff, as they look beyond hype and short-term trends to focus on building businesses that can have a real impact.
“The community of founders who put their head down and are working to build their companies at an early stage will continue to be vibrant,” says Neo.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

If AI has a one-in-five chance of destroying us, what do we do with the remaining four?

