

Frasers Property’s big asset shuffle: Controlling shareholder helping it drive value and stay listed
Investors may have to wait for the latent value of its shares to be fully realised in an apathetic market
[SINGAPORE] When Frasers Property (FPL) made its first offer for Frasers Hospitality Trust (FHT) back in 2022, this column suggested that the group ought to consider organising a privatisation deal for itself too.
After reading the recently announced optimisation plan for the properties held under FHT – which FPL succeeded in taking private on its second attempt last year – it seems that the group’s controlling shareholder is more interested in improving the market value of the Singapore-listed property developer than taking it private.
That is not a bad thing, of course – but it could mean that investors will be left waiting a long time for the latent value within FPL to be fully realised.
Under the proposed optimisation plan, certain legacy arrangements put in place to support FHT’s listing will be reversed; and FHT’s interest in S$2.1 billion worth of hospitality assets will be shuffled between FPL and TCC Group Investments (TCCGI), which currently hold 63.3 per cent and 36.7 per cent of FHT’s stapled securities, respectively.
A group of mature hospitality assets worth S$1.1 billion will end up being fully owned by TCCGI, while FPL will have full ownership of Frasers Suites Singapore, an asset worth more than S$300 million.
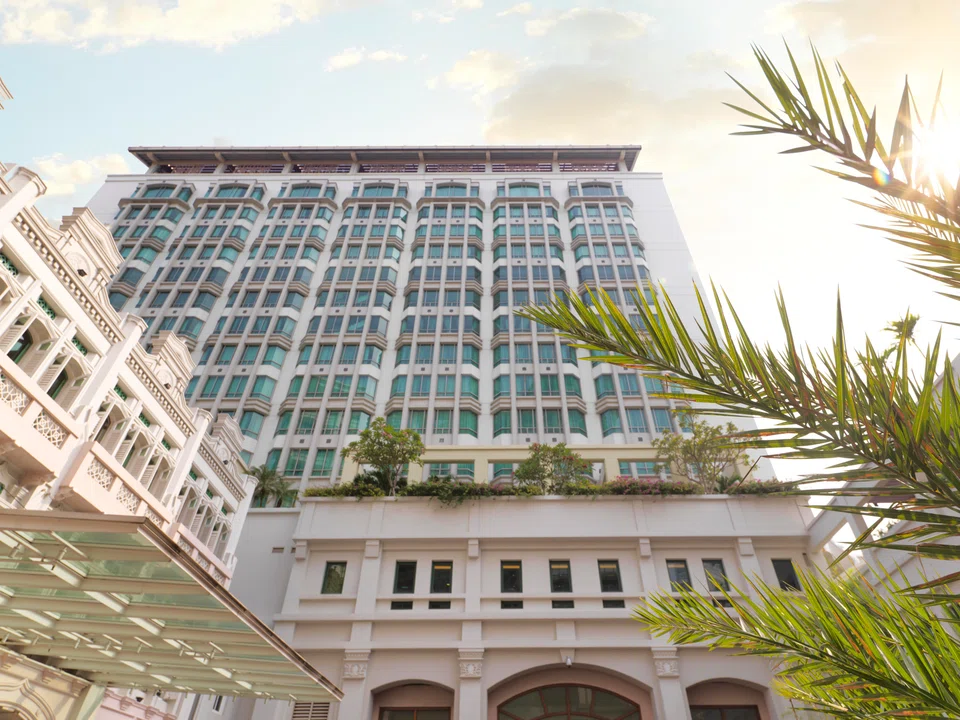
“Full ownership of Fraser Suites Singapore will enable the group to pursue potential redevelopment of the entire Valley Point site, providing further opportunities for value creation over the longer term,” FPL said.
TCCGI will also have a more than 50 per cent interest in S$400 million worth of hospitality assets that have the potential to achieve higher yields through value enhancement initiatives, with FPL holding the balance.
FPL and TCCGI will maintain their existing interests in a further S$300 million worth of assets that have been classified as “non-core” and earmarked for eventual sale.
FPL said it expects to receive S$177.9 million in cash from the various divestments and acquisitions under the optimisation plan. After footing S$78.4 million in fees, stamp duties and other taxes, the group figures it will rake in net proceeds of S$99.5 million.
Controlling shareholder support
For some market watchers, the most significant element of the optimisation plan is the potential redevelopment of Valley Point. For others, it is the fact that FPL will continue to earn recurring income from the hospitality assets it is offloading to TCCGI.
FPL said its balance sheet exposure to hospitality assets will decline from approximately S$3.7 billion to S$2.5 billion, but its assets under management will be maintained at S$4.2 billion.
For me, the most interesting aspect of the optimisation plan is that FPL’s controlling shareholder is lending its support to the public-listed group without any obvious direct benefit to itself.
TCCGI is linked to the family of Thai billionaire Charoen Sirivadhanabhakdi, which also holds 86.9 per cent of FPL through an entity called TCC Assets.
In effect, FPL’s controlling shareholder is taking full ownership of the most fully priced properties under the privatised FHT, and increasing its stake in the ones that may require capital for asset enhancement initiatives.
As my colleague Jude Chan explained in his analysis of the optimisation plan, there was limited interest in FHT’s properties from third party investors. If TCCGI had not stepped in, FPL might have been forced to settle for lower valuations or give up the management of the assets.
FPL said the negotiated transaction price for each of the assets under the optimisation plan was the higher of their latest independent valuation or their implied valuation when FHT was taken private.
Of the five mature assets worth S$1.1 billion that TCCGI will fully own, four of them are being priced at their implied take-private valuations and above their latest independent valuations.
On a portfolio basis, the negotiated transaction prices of the assets FPL is offloading in full or in part to TCCGI are either 6.7 per cent above their latest independent valuations, or 1.6 per cent above their implied take-private valuations.
Meanwhile, FPL is acquiring Frasers Suites Singapore at its latest independent valuation of S$320 million, which is less than 0.7 per cent above the implied take-private valuation of S$317.9 million.
Some market watchers have suggested to me that TCCGI’s support of FPL is not all that remarkable, given that it owns almost all of the listed company’s shares.
By lightening FPL’s balance sheet and putting it in a position to redevelop Valley Point, TCCGI may enable the group to improve its profitability, lift the market value of shares, and perhaps widen its free float too.
Yet, after a fillip when the optimisation plan was announced, FPL’s shares have drifted back down. They closed on Friday (Jul 3) at S$1.07, unchanged from their last close before the announcement, and just 0.45 times the company’s net asset value (NAV) of S$2.40 per share.
What will it take for FPL to meaningfully boost the market value of its shares? Why are they trading so far below the company’s book value in the first place?
Unjustifiably low valuation
Much like other major Singapore-listed real estate groups, FPL’s return on equity has sagged over the years, and weighed on the market valuation of its shares. Unlike its best known peers, however, FPL’s shares have not rerated significantly amid the excitement about the revitalisation of the Singapore market.
During the 12-month period up to the day before the optimisation plan was announced, FPL delivered a total return of 31.7 per cent. City Developments Ltd and UOL Group returned 63.7 per cent and 61.3 per cent over, respectively.
The Straits Times Index returned 39.7 per cent during the same period.
Some analysts think FPL is now trading at an unjustifiably low valuation, and that its shares could rise significantly in the months ahead.
In a report in April, DBS Group Research said it expects resilient performance across FPL’s businesses, and that the redevelopment of Valley Point and Centrepoint could lift its revalued NAV (RNAV) by S$0.53 per share – which is nearly half the current market value of its shares.
Yet, the research house’s target price for the stock is only S$1.50 – or just 0.54 times its estimate of FPL’s RNAV of S$2.80 per share.
The way I see it, this reflects a lingering lack of enthusiasm in the market for property developers as new technologies and shifting preferences cloud the long-term outlook for commercial real estate.
For instance, e-commerce has been reshaping demand for retail and dining spaces for years. The rise of artificial intelligence and remote work are also making the long-term outlook for traditional office spaces harder to discern.
This column has also argued in the past that the residential property development sector is in need of reform, given the negative externalities it is creating for society.
To be clear, I am not suggesting that FPL and its peers are not adapting to change. But they are not doing so with the intensity and scale that is likely to excite public investors, in my view.
FPL may well be about to enhance its underlying value significantly with the backing of its controlling shareholder, but it is not clear how quickly and to what extent this will be reflected in the market value of its exceedingly depressed stock.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

What role can Japan play in Asean’s future?

