

Getting a better grip on Top Glove’s changing fortunes
Anita Gabriel
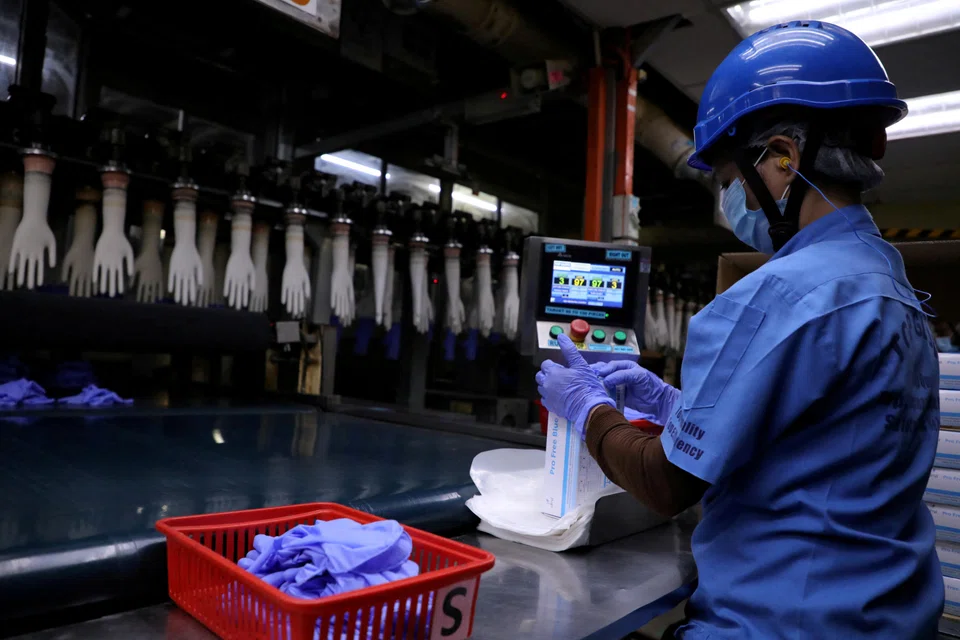
TOP Glove, the world’s largest maker of rubber gloves, announced last week that it had suffered deep losses for the three months ended November. Its latest report card underscores the shifting fortunes of the Malaysia and Singapore-listed company in a sector previously deemed resilient.
The business of manufacturing gloves, an essential healthcare item, has been through some “peaks and valleys”, in the company’s own words. But the cost of doing business has been weighed down lately by a hangover from the pandemic sales rush, rosy margins and bloated inventories.
Top Glove, which has manufacturing operations in Malaysia, Thailand, Vietnam and China, said it made a net loss of RM168 million (S$51.4 million) in the first quarter of FY2023, reversing from a profit of RM186 million in the corresponding period a year ago. Revenue fell 61 per cent to RM633 million over the period.
The culprits for the disappointing results were the dreaded double whammy of lower sales volumes and soft average selling prices (ASPs), owing to waning demand. Customers have high inventory levels, and there is intensifying competition – especially from Top Glove’s Chinese counterparts.
The dismal showing follows a spectacular pandemic performance. Profit hit a record RM7.7 billion in FY2021, versus RM1.8 billion in FY2020, as revenue more than doubled to RM16.4 billion.
Shareholders were handsomely rewarded with a record total annual dividend of 65.1 sen per share – a 452 per cent jump from FY2020’s full-year dividend of 11.8 sen per share. Emboldened by the rosy results, Top Glove raised the frequency of its dividend payments from semi-annual to quarterly.
Having tasted such profitability, investors now appear even more bearish about Top Glove than they were before the pandemic even started.
Top Glove ’s shares on the Singapore Exchange have tumbled 72 per cent in the year to date. It has been booted out of the FBM KLCI 30-stock index – a benchmark for the Malaysian market widely used by investors – following a review.
Its sector peers have suffered similar fates. Hartalega Holdings, for instance, has lost more than 70 per cent of its value this year.
Did investors get ahead of themselves at the height of the pandemic?
In hindsight, it should be unsurprising that some semblance of normalcy would have to return eventually.
That adjustment did not take long. In FY2022, Top Glove’s net profit tumbled to RM226 million as revenue plunged 66 per cent to RM5.6 billion. Over the final quarter ended August 2022, the company logged its maiden quarterly loss since its 2001 listing on Bursa Malaysia (it was listed on the Singapore Exchange in 2016), to the tune of RM53 million – a sharp swing from a profit of RM447 million in the same period a year ago.
The group cited a “normalisation” in the glove sector after two exceptional years of high earnings owing to the pandemic. That normalisation also included the need to adjust – as well as strategise – to withstand an environment bogged down by oversupply and excess stockpiling.
Another pain point was the group’s total production capacity of 100 billion gloves per annum, now sorely under-utilised.
Meanwhile, costs have spiralled owing to a 60 per cent hike in natural gas tariffs and a 25 per cent increase in minimum wages in Malaysia. Global supply disruptions are adding more salt to the wound. These pressures resulted in a negative margin on earnings before interest, taxes, depreciation, and amortisation of 8 per cent in FY2022.
Things could get worse before they get better, although the company’s management has guided that customers could start restocking from as early as Q2 FY2023 as inventory levels get depleted. This could mean more orders, and ASPs could stabilise or decline at a slower pace in the ensuing months.
Maybank has forecast a net loss of RM323 million in FY2023 for the glovemaker. CGS-CIMB Research, which had earlier forecasted a RM42 million net profit for the glove maker in FY2023, now expects it to suffer a loss of RM311 million for the year.
In the bigger scheme of things, it may be worth asking if Top Glove – not unlike many other companies that enjoyed happy days, businesswise, during the pandemic – could have better prepared itself for the inevitable slowdown.
TRENDING NOW

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

CDL to hire dedicated CEO for fund management as it steps up push into private funds

Built on trust since 1964: How this award-winning finance company has grown with its SME customers

VSMC opens US$7.8 billion chip fab in Singapore, bets on ‘physical AI’ demand

