

Golden Agri a safe haven amid uncertainty
Investor sentiment towards the integrated palm oil player has been weighed down even as it has delivered elevated levels of profitability

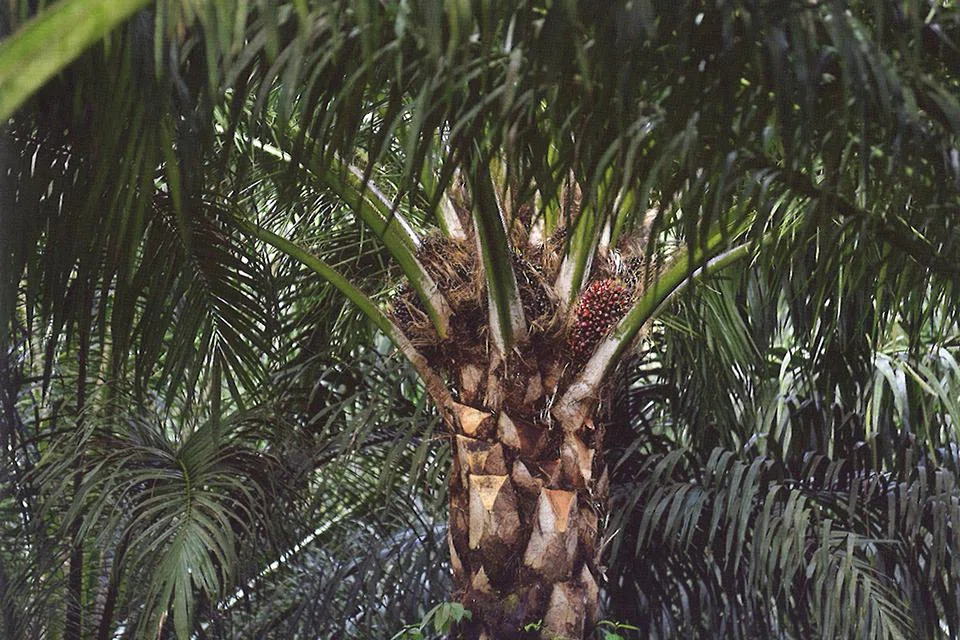
GOLDEN Agri-Resources reported financial numbers last week that made me want to buy its stock – and, I was not alone.
Over the course of two trading days, shares in the integrated oil palm plantation group surged nearly 10 per cent on elevated volume. On Friday (Mar 3), Golden Agri closed at S$0.275 – up 7.8 per cent since the results were released.
Before the market opened on Tuesday, Golden Agri said its earnings for 2022 increased 64.2 per cent to US$782.1 million on a 12.3 per cent rise in revenue to US$11.4 billion. Its “underlying profit” for 2022 – which excludes non-recurring items – was up 52.9 per cent to US$921.9 million.
Golden Agri proposed a final dividend of 0.991 Singapore cents per share, which put its total dividend for 2022 at 1.791 Singapore cents per share. The company paid a total dividend of 1.605 Singapore cents per share for 2021.
Just before the results were released, shares in Golden Agri were trading at less than 3.1 times the company’s reported 2022 earnings, and offered a dividend yield of about 7 per cent.
Is it too late to buy the stock now? How much higher can it climb?
Besides continued robust profitability at its upstream plantations and palm oil mills businesses, Golden Agri said it benefited in 2022 from “exceptional” performance at its downstream processing and distribution businesses. On the face of it, the group’s overall earnings are very likely to decline significantly in 2023 and 2024 as its downstream margins normalise.
At the same time, concerns about palm oil prices weakening from the peak levels they hit in early 2022 have weighed on investor sentiment even as companies across the sector generally enjoyed strong profitability.
Even after its bounce last week, Golden Agri has delivered a total return of minus 10 per cent (dividends reinvested) over the past 12 months. The Straits Times Index returned 3.6 per cent during the same period.
As a result, valuations in the palm oil sector are not demanding. Golden Agri is currently trading at a more than 50 per cent discount to its book value. Forecasts by OCBC and RHB suggest Golden Agri shares are still priced at only about five or six times its 2023 and 2024 earnings.
OCBC puts the fair value of the stock at S$0.31, while RHB has a price target of S$0.34.
Going private?
The long-term profitability of commodities producers is notoriously hard to predict, of course. Companies such as Golden Agri arguably trade at single-digit earnings multiples for a good reason.
But this brings me to another investment angle on the stock: the possibility of a general offer for the company.
If companies such as Golden Agri are unable to garner a decent valuation in the public market, going private could be a way for their controlling shareholders to unlock value.
Golden Agri’s elevated profitability over the past two years has put its balance sheet in a very strong position. In a presentation deck accompanying its results announcement, the company noted that its net debt as at end-2022 was just US$142 million versus US$970 million as at end-2021.
Golden Agri’s 2021 annual report stated that entities linked to Indonesia’s Widjaja family held a deemed interest in nearly 50.6 per cent of the company’s shares.
Much would depend, however, on the Widjaja family’s view of Golden Agri’s profitability over the next couple of years. A successful privatisation bid would also hinge on the Widjaja family being prepared to offer a high enough price to minority investors.
Golden Energy and Resources (Gear) – another Widjaja family-controlled company – unveiled plans late last year to delist itself on terms that some analysts and minority investors (including myself) have said are inadequate.
While Gear is still working through the process of formally putting the transaction before its shareholders, its shares have already climbed above the proposed all-cash consideration of S$0.846 per share – fuelled by the strong financial performance of its businesses and widespread expectation that the terms of the delisting will be improved.
Gear closed on Friday at S$0.905.
Some investors may also remember that Indofood Agri Resources (IndoAgri) was the subject of a lowball general offer back in 2019.
Its parent group attempted to buy all the shares it did not already own at S$0.28 each – which was a 64.9 per cent discount to IndoAgri’s book value at the time. The offer price was later raised to S$0.33 (cum dividend). But the offeror ultimately failed to cross the 90 per cent threshold.
While IndoAgri’s profitability has improved dramatically since 2019, its shares have barely budged since the offer fell through. The stock closed Friday at S$0.315.
This is just 6.4 times IndoAgri’s 2022 earnings, and a 61.1 per cent discount to its book value as at Dec 31.
Some observers may interpret this to mean that minority shareholders of IndoAgri should have meekly accepted the lowball offer back in 2019. The lesson I choose to draw from this episode is that companies such as IndoAgri do not belong in the public market, but minority investors have to be adequately compensated when these companies go private.
Risks abound
Many readers of this column may not share my views about Golden Agri, or agree with the manner I have gone about evaluating the attractiveness of its stock.
In particular, some readers will probably feel it foolhardy to invest in a company on the back of blowout earnings in a single year. Such “nowcasting” could well land a long-term investor in trouble down the road.
Yet, the bounce in Golden Agri’s shares last week versus the sell-offs suffered by DBS and UOB immediately after reporting record earnings for 2022 last month holds lessons for investors trying to navigate the complexities of structurally higher interest rates, heightened geopolitical uncertainties and continuing technology disruption.
Against the current backdrop of widespread uncertainties, it is perhaps the most closely followed and richly priced stalwarts that are most at risk of disappointing investors. Supposedly risky commodity stocks with deflated valuations that might continue to have the wind at their backs could turn out to be safe havens of sorts.
TRENDING NOW

Looking beyond looming CEO succession, should UOB potentially pursue a transformative merger?

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Family offices ‘kept captive’ by relationship managers turn to independent advisers, direct deals
MAS holds monetary policy settings, pausing after two straight tightenings

