

Golden Energy’s proposed break-up, delisting looking more miserly after Stanmore’s big run
Ben Paul
WHEN the break-up and delisting of Golden Energy and Resources (Gear) was announced in November, some analysts said the company’s minority shareholders were getting a raw deal.
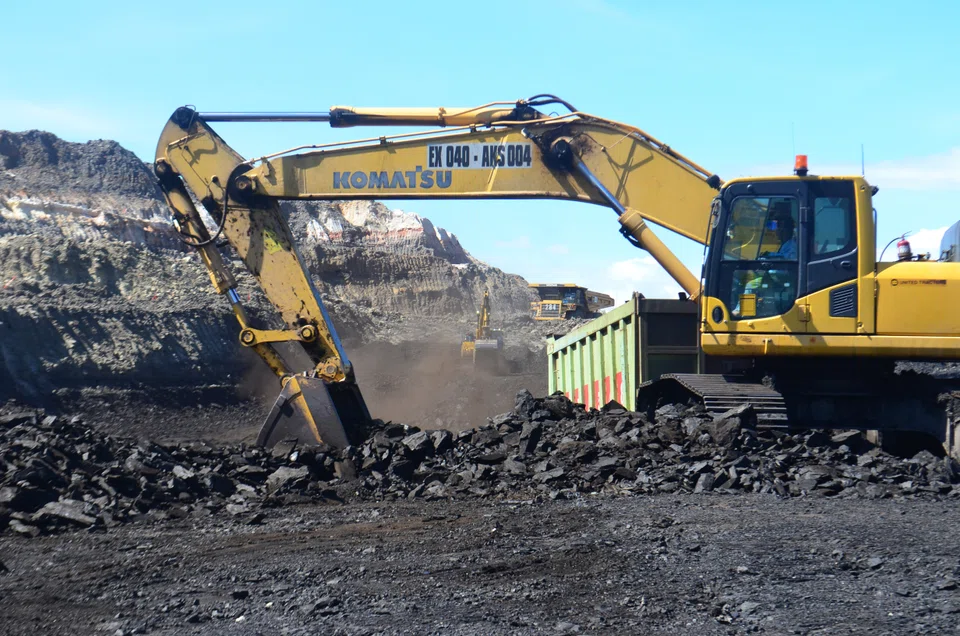
With the steep rise in the Australia-listed shares of metallurgical coal producer Stanmore Resources – in which Gear holds a 64 per cent stake – the terms of the whole corporate exercise now look even more miserly.
There are two elements to the proposed deal. Gear will first do a distribution in-specie of its 62.5 per cent stake in Indonesia-listed thermal coal producer Golden Energy Mines (Gems).
Gear will then delist itself from the Singapore Exchange, with an exit offer price of S$0.16 per share.
Shareholders of Gear have two choices when it comes to the distribution in-specie of Gems. They can elect to receive 1.3936 Gems shares for every Gear share they hold; or a cash consideration of 7,664.8 rupiah (which prices their entitlement to 1.3936 Gems shares at 5,500 rupiah per share).
Shareholders of Gear who opt to receive Gems shares will be getting a total effective consideration of S$1.045 per share (based on the market price of Gems shares of 7,100 rupiah at the time of the announcement).
Shareholders of Gear who take the cash option will be getting a lower total effective consideration of S$0.846 per share.
This obviously discriminates against small investors, who are likely to prefer receiving their entitlement to the Gems shares in the form of cash.
Gear is 77.5 per cent-owned by Indonesia-listed Dian Swastatika Sentosa (DSS), which is in turn 59.9 per cent-owned by Sinar Mas Tunggal.
Since the announcement of the deal, the market price of shares in Gems has slipped 3.9 per cent to 6,825 rupiah.
But that is still 24.1 per cent more than the 5,500 rupiah cash consideration.
The other problem with the deal is that the exit offer price of S$0.16 per share does not fully reflect the value of Gear’s remaining assets, which include the 64 per cent stake in Stanmore and a 50 per cent stake in gold miner Ravenswood Gold Group.
In particular, the market price of Stanmore shares has jumped from A$2.99 when the deal was announced to A$3.61 on Jan 30. This has inflated the market value of Gear’s stake in Stanmore by almost S$330 million – or some S$0.13 per share.
In other words, the appreciation of Stanmore shares since the deal was announced alone is nearly equivalent to the exit offer price for Gear.
The offeror is a privately held Singapore company called Duchess Avenue that is ultimately owned by Lanny Tranku – the spouse of Indra Widjaja, a senior member of the family that controls Indonesia’s Sinar Mas group.
Arun George, an analyst at Global Equity Research, who publishes on Smartkarma, said in a Jan 20 note that the exit offer price is 52 per cent below the value of Gear’s stake in Stanmore.
Using Stanmore’s closing price on Jan 20 of S$3.66, he said the value of Gear’s 64 per cent stake in the metallurgical coal player was S$1.9 billion – or S$0.73 per Gear share.
After carving out Gems and adjusting for net debt, Gear would theoretically be worth S$0.33 per share on the back of its stake in Stanmore alone – versus the exit offer price of S$0.16 per share.
Interestingly, Gear said on Jan 20 that the long-stop date for satisfaction of the exit offer conditions has been extended from Apr 9 to Aug 9.
The timeline for Gear to obtain shareholder approval for its delisting has also been pushed to Jul 9. It was originally supposed to have been obtained within three months of the announcement of the deal.
Gear said the deadlines had been extended to provide DSS with more time to obtain the necessary approvals from its shareholders.
George said in his Jan 20 note that an “alternative explanation” for the delay is that the Widjaja family’s offer for Gear is looking increasingly unattractive in the light of Stanmore’s share price rally. The way he sees it, there is now a “good chance” the Widjaja family will hike the exit offer price in order to win over investors.
Many shareholders of Gear will probably be hoping he’s right. Gear closed at S$0.785 on Monday, Jan 30.
The writer owns shares in Golden Energy and Resources
TRENDING NOW

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

CDL to hire dedicated CEO for fund management as it steps up push into private funds

Built on trust since 1964: How this award-winning finance company has grown with its SME customers

VSMC opens US$7.8 billion chip fab in Singapore, bets on ‘physical AI’ demand

