

Growing disconnect between stock market and underlying economy
The fundamentals of the domestic economy, which point to steady but unspectacular growth, do not really justify unbridled optimism
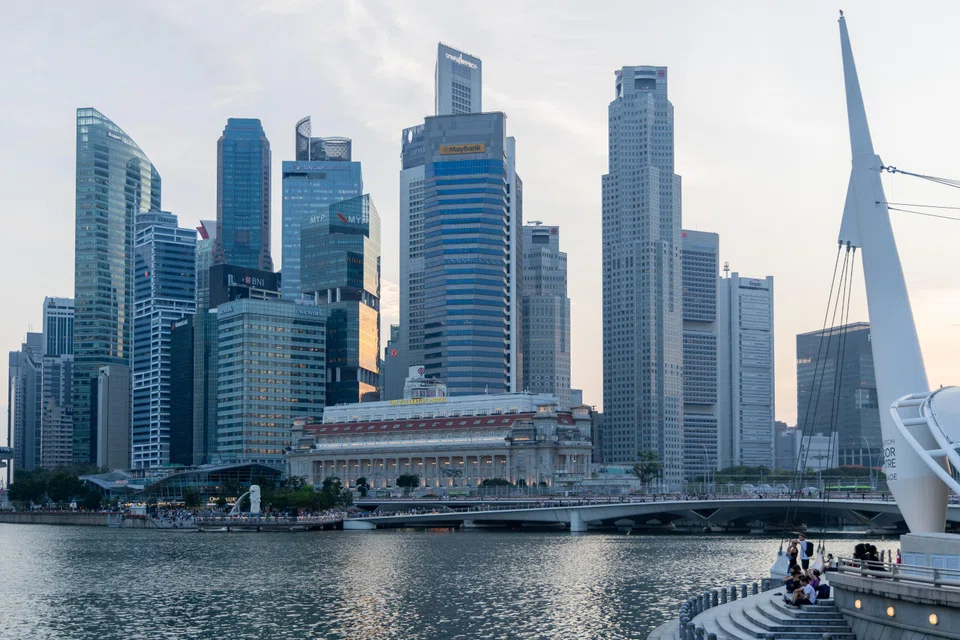
THE local stock market has been going great guns in recent months, with the Straits Times Index (STI) rising to new all-time highs, boosted mainly by strong gains in the banks – most notably, DBS.
Yet, the domestic economy is sluggish, although the recent quarterly data has led private-sector economists to raise their full-year forecasts slightly to between 3.2 and 3.5 per cent.
Globally, the picture is the same: The latest World Bank estimates indicate that by 2027, global gross domestic product growth may average only 2.5 per cent in the 2020s – the slowest pace of any decade since the 1960s.
This apparent contradiction of a booming market alongside a tepid economy mirrors a trend seen in many other places, such as the US, where equities continue to defy soft or indifferent macroeconomic indicators.
One major reason behind this disconnect is liquidity. The US Federal Reserve’s prolonged period of monetary accommodation from 2008 until 2022 has flooded global markets with cheap money, and although US rates were raised in 2022 in response to surging inflation, liquidity remains abundant due to 14 years of “quantitative easing”.
A second reason for the market’s strength is, ironically, the very fact that the economy isn’t too hot, which is fuelling expectations that the Fed will have to cut interest rates sooner or later to stimulate business activity.
This is the familiar “bad news for the economy is good news for the market’’ theme, which has played out many times over the years.
Here, the market rally is partly underpinned by expectations of lower interest rates and falling bond yields, as well as optimism over the Equity Market Development Programme (EQDP) unveiled by the Monetary Authority of Singapore, which promises an injection of S$5 billion.
Part of that money has already been disbursed to three fund managers that will invest in local stocks other than that of the STI’s 30 companies. The launch of two new market indices has also stoked interest in non-STI stocks, helping to lift prices.
But while liquidity and optimism can elevate stock prices, they do not necessarily translate into real economic growth; nor do they lead to the average household being better off.
The underlying structural problems which are plaguing the domestic economy remain: an ageing population, high operating costs, weak productivity gains, a persistent wage and wealth gap, disruptions from artificial intelligence, and the threat posed by US tariffs.
In the US, a similar pattern has existed for years. Tech giants such as Nvidia, Tesla, Apple, Amazon, Microsoft and Meta have propelled the major indices to record highs, even as inflation remains sticky and labour markets remain weak amid the destabilising effects of recent policy shifts, especially new tariffs.
As a result, the stock market has increasingly become more a barometer for the tech industry and the global capital flows that the industry is attracting, than a reflection of true national economic health.
This doesn’t mean the upswing in stocks will end any time soon. There is sufficient momentum built up this year to ensure more upside, plus the authorities will surely announce more EQDP-related initiatives to sustain interest.
But it’s important to recognise that the fundamentals of the domestic economy, which point to steady but unspectacular growth, do not really justify unbridled optimism to the extent currently driving stocks.
Those who chase the rally without regard to valuations or earnings sustainability may find themselves exposed when the tide turns. Last week’s correction should be an early warning signal.
TRENDING NOW

Why US$100 oil, 5% US yields affect Singdollar, ringgit differently vs other Asean currencies
Singapore fintechs struggle to find finance and tech talent

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

Why Tan Aik Keong of digital solutions specialist Agmo wants to make himself less indispensable

