The hefty (BTO) price of being a romantic
EVERY quarter, I get the same question from a very well-meaning colleague: “When are you going to BTO?”
After the latest May release of HDB Build-To-Order (BTO) flats, he posed the question to me again.
Each time he asks me that, I tell him that I worry if things are moving too quickly, and he chides me for being too much of a romantic.
“It always makes sense to get an HDB flat early, you should have been trying for one years ago,” he will say, even though I met my partner just two years ago. He will then go on insisting that I do the maths, that it is a no-brainer.
As much as I hate to admit it, he is not wrong. If I were brutally focused on the numbers, I would have said “I love you” on the second date and asked “BTO ai mai (would you like to BTO)?” on the third.
There are definitely several benefits to buying a BTO flat early. Most importantly, the price of one rises with each passing year.
Mid-point prices for a four-room flat stood at S$395,000 and S$415,000 in two Tengah estates released in May. Meanwhile, a similar flat in a Tengah estate released in May 2021 sold for S$329,000. That’s more than a 20 per cent difference in just two years.
In an inflationary environment, one could reasonably expect rents and resale prices of physical properties to rise, which makes them decent hedges.
Headline inflation in Singapore averaged 6.1 per cent in 2022, while HDB resale prices rose by 10.4 per cent. When headline inflation stood at 6.6 per cent in 2008, HDB resale prices also rose by 14.5 per cent.
Of course, past performance does not predict future results, and there have been a number of cooling measures put in place in recent months. Still, it is a good idea to own property as inflation rises.
Then, there is the issue of waiting for a flat.
By now, there have been many well-publicised stories of people who applied for a BTO flat numerous times in mature estates to no avail.
Couples, especially those who wish to stay in mature estates, should try to give themselves sufficient runway to secure these flats, which may also have later completion dates.
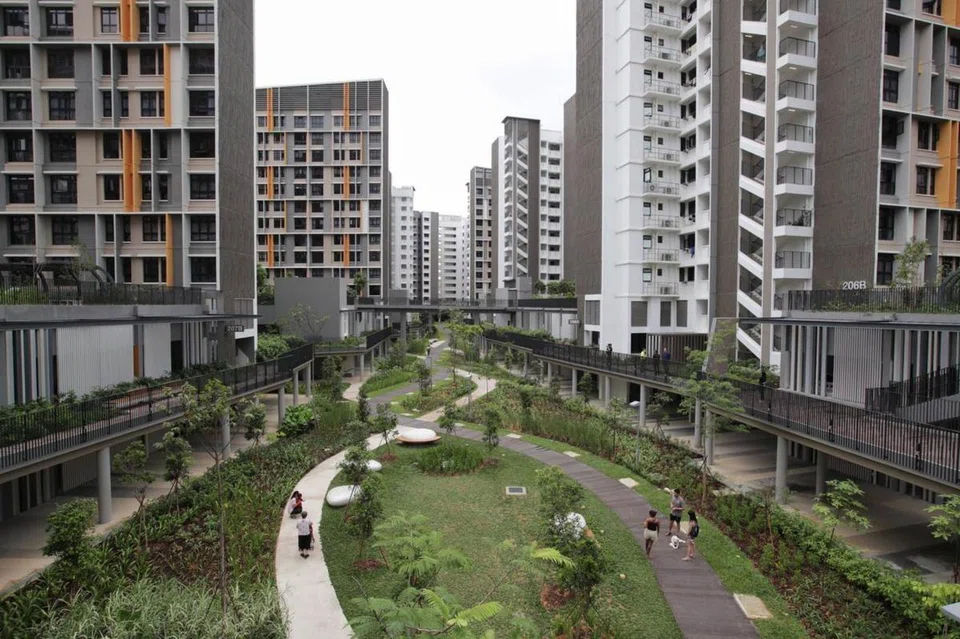
Notably, the prime location public housing project Ulu Pandan Glades in Queenstown had an estimated waiting time of five years and eight months. Other BTO projects in the area have similarly long wait times as well.
If all else fails and you need to consider the resale market, the costs climb even higher.
Ulu Pandan Glades’ four-room flats may be available at subsidised prices of S$541,000 to S$711,000, but comparable resale units quoted for the project go for S$860,000 to S$996,000.
I am not suggesting that anyone insist on purchasing a flat in a mature estate, but the difference in price is the opportunity cost of putting off balloting for a BTO flat.
The point is that you would surely feel worse bankrolling someone else’s BTO gains while your peers get to stay in a prized estate for the same price you paid for a less prime location.
I should also point out that graduates from higher-paying courses such as law and computing cannot afford to wait.
According to the 2022 Graduate Employment Survey, National University of Singapore graduates in the 75th percentile of courses such as computer science and business administration already had starting salaries of S$7,000 and above.
If a couple were to earn more than a combined S$14,000 with their starting salaries, they would breach the BTO income ceiling and would have to resort to the resale market, unless they had booked flats before graduating.
My colleague Leslie Yee noted in a recent article that couples who purchase resale flats because they breach the income ceiling can face worse price-to-income ratios compared with lower-earning couples who manage to get BTO flats.
Miss the forest for the trees
I do not think that I am that big of a romantic, but I should point out that HDB asks you for your relationship to the person with whom you are applying for a flat.
To qualify as a couple, you have to at least answer that you are fiance and fiancee. That should give pause to people who are just starting out in their relationships.
In the last two years, I have found that there are costs to being late to the party.
My well-meaning colleague will note that even if you break up after booking a flat, the costs are only 2.5 per cent of the downpayment of a BTO flat, assuming both parties share the cost equally and had booked a flat under the staggered downpayment scheme.
Still, I would argue that the ultimate cost of moving too quickly is the loss of an ideal partner.
It would be such a waste to lose someone simply because you did not take the time to build a strong relationship first. Finances and long-term plans can already be tricky topics, and they could be trickier yet if you do not fully understand your partner before delving into thorny issues.
I can say that I have changed a lot since I started dating my partner two years ago. We were very careful to make sure that we could communicate clearly and understand each other’s life goals before we applied for a flat.
Could we have applied for a BTO flat safely on the third date? Not a chance. I think I would have scared her away. I would then have to live with the regret of losing someone whom I could have loved very much and shared a life with.
Faced with such difficult decisions, we can only trust our gut and make the best of what we have.