

The hidden carbon accounting costs of tariffs
A flawed methodology amplifies both environmental and financial risk
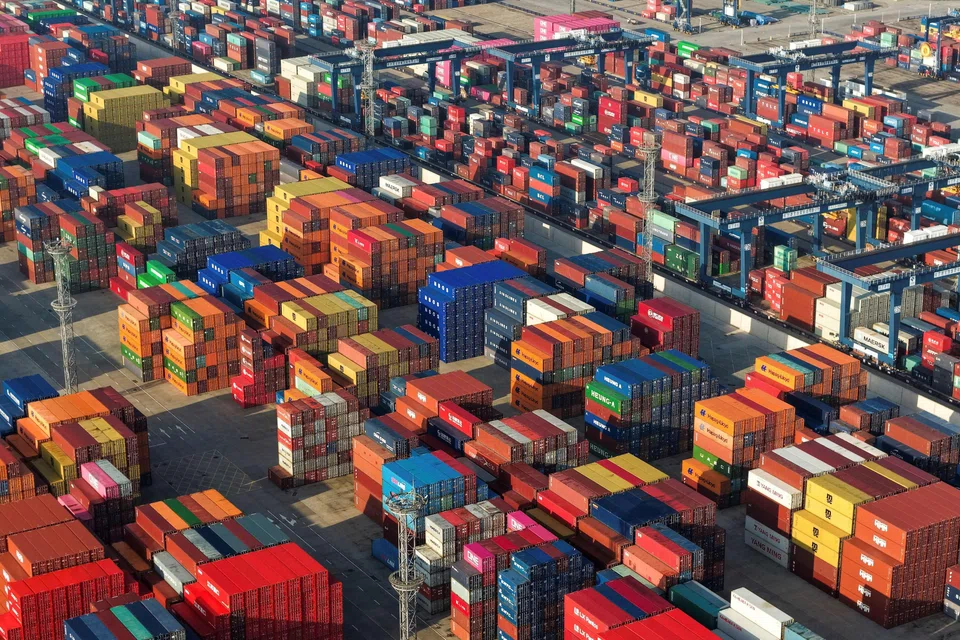
AMID rising global trade tensions, businesses across Asia are confronting not just supply chain disruption and rising costs, but also an underappreciated consequence: distorted sustainability reporting.
While much attention has been paid to the macroeconomic impact of tariffs, the less visible but equally serious effect lies in how tariffs distort carbon accounting – specifically when businesses rely on spend-based emissions estimates.
Trade uncertainty and regional economic impact
Across Asia, recent volatility in tariffs has had wide-ranging effects.
In Australia, tariff-related uncertainty has weighed on the national outlook, the Reserve Bank of Australia said. In China, gross domestic product growth slowed slightly, despite initial concerns, as trade tensions persisted. In India, growth projections were revised downward, despite remaining among the region’s fastest-growing economies.
Closer to home in South-east Asia, the Asian Development Bank estimates tariff impacts could reduce growth by up to half a percentage point annually.
These macroeconomic signals underscore a common corporate response: businesses are recalibrating supply chains, cost structures, and market strategies to navigate the disruption.
But there is another layer of hidden cost emerging, one that threatens the credibility and financial integrity of sustainability efforts.
Tariffs and the hidden flaws in carbon emissions estimates
Most companies begin their carbon accounting journey using spend-based calculations, where emissions are estimated based on the monetary cost of purchased goods or services. This approach is simple and widely adopted, but not equipped to handle tariff-induced cost fluctuations.
The problem lies in how tariffs raise the apparent cost of imported goods. When those inflated costs are plugged into spend-based emissions models, they artificially elevate the associated carbon footprint.
Since many commonly used datasets for carbon estimation are not agile enough to reflect real-time tariff changes – or handle them consistently – businesses are left with distorted, often inflated emissions data.
For example, many electronics and semiconductor components are manufactured in Malaysia, Vietnam, China, and Taiwan. They are often then routed through Singapore and other logistics hubs for tariff optimisation, repackaging, or re-invoicing.
The resulting paperwork alone can increase the declared value of a shipment by as much as 15 per cent, despite there being no real change in energy use or physical emissions. A company that tracks transport emissions would already have accounted for them in the books.
When using spend-based carbon accounting, a higher invoice value equates to higher “embedded carbon”.
That means tools misread financial uplift as emissions uplift – leading to overstated emissions, misaligned decarbonisation goals, and unnecessary or excessive carbon offset purchases. In short, a flawed methodology amplifies both environmental and financial risk.
The strategic risk of inaccurate ESG data
Poor emissions data has a cascading effect across the business.
Misdirected investments in decarbonisation technologies, misunderstood risk exposure in climate-sensitive sectors, and overpayments in voluntary carbon markets are common consequences.
Inaccurate environmental, social, and governance (ESG) metrics can also erode stakeholder trust, from investors to consumers, and impair access to financing or partnerships, especially as regulators and capital markets tighten expectations around climate disclosures.
Put simply, spend-based emissions models can create enterprise risk if left unchecked.
The case for activity-based emissions calculations
An effective alternative lies in activity-based calculations, as defined by the Greenhouse Gas Protocol. These rely on measurable physical inputs – such as kilogrammes of goods purchased or kilometres travelled–multiplied by appropriate emissions factors.
Unlike spend-based methods, activity-based models are tariff-agnostic. A 50 per cent tariff doesn’t affect the weight of a shipment or the distance it travels. They are also more precise and offer a truer picture of operational emissions. Strategically, they highlight real decarbonisation opportunities and align better with performance and profit metrics.
Despite their benefits, activity-based models are not yet mandated. Global standards such as the European Union Corporate Sustainability Reporting Directive accept either method. But for companies serious about decarbonisation – and shielding themselves from price-based distortions – activity-based approaches offer strategic clarity.
From compliance to competitive advantage
Using robust operational data isn’t just about reporting accuracy – it’s about unlocking value.
Businesses that transition to activity-based carbon accounting stand to improve their ESG credibility, avoid unnecessary costs, and make smarter sustainability investments.
As global trade complexity grows, the hidden costs of mismeasurement cannot be ignored. In a world where both carbon and capital are increasingly constrained, the shift from spend- to activity-based calculations is a strategic imperative.
Businesses that recognise and act on this now will be better placed to make sustainability profitable – and profitability sustainable.
The writer is president and managing director at SAP South-east Asia
TRENDING NOW

Higher rates, weaker spending: Is the Philippines entering stagflation?
Ex-Nvidia CEO misled top lawyer on affair with Chinese businesswoman, sources say

‘I’ll be buying more’: Singapore investors pour into Nvidia shares on Jensen Huang’s exit
Nvidia approaches Arm CEO Haas as employees seek Huang's return, reports say

