

Higher rates inflict pain on borrowers but economy, not just banks, benefits
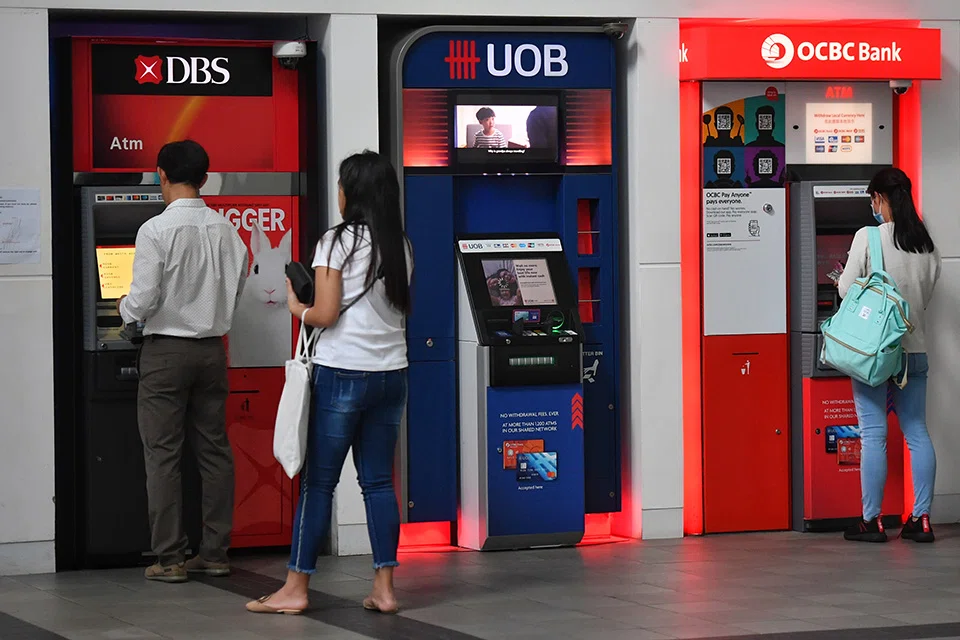
THE three Singapore banks listed on the local bourse are basking in a period of favourable interest rate movements, drawing positive reactions from the market. Borrowers may be a little less happy, but those offended by the banks’ healthy margins should also consider that strong banks help support a strong economy.
For Q3 2022, DBS posted a 32 per cent increase in net profit to S$2.24 billion. Net profit at OCBC rose 31 per cent to S$1.61 billion. And UOB posted a 34 per cent gain in net profit, to S$1.4 billion.
Contributing to profit growth were improving net interest margins (NIMs). On a quarter-on-quarter basis, DBS’ Q3 NIM rose 32 basis points to 1.9 per cent. OCBC’s was up 35 basis points to 2.06 per cent, and UOB’s up 28 basis points to 1.95 per cent. Year on year, their NIMs have risen by between 40 and 54 basis points.
The NIM is the difference between the interest income generated by banks from credit products – such as loans – and the amount of interest paid out by banks to deposit holders.
For some perspective, net interest income as a share of total income in Q3 was 66 per cent, 67 per cent and 70 per cent, respectively, for DBS, OCBC and UOB.
The banks may see their NIMs expand further. DBS, for one, expects its NIM to reach around 2.25 per cent by mid-2023, assuming that the United States Federal Reserve’s federal funds rate peaks at 4.75 per cent. In its outlook for 2023, the bank projects its return on equity (ROE) to be comfortably above 15 per cent.
Hiking loan rates
Given their healthy profits, borrowers may wonder why the banking trio does not go slow on growing NIMs by being gentle in raising loan rates. Some might argue that shareholders should be contented with DBS, for example, posting an ROE closer to 10 per cent instead of 15 per cent.
Many borrowers, whether individuals or businesses, are burdened with paying higher interest costs. The three-month compounded Singapore Overnight Rate Average rose from about 0.2 per cent per annum at the start of 2022, to about 2.9 per cent as at value date Nov 28, 2022. Recently, DBS, OCBC and UOB upped their fixed-rate home loan packages past the 4 per cent mark. DBS’ fixed-rate packages are at 4.25 per cent a year, with tenors of two to five years.
Of course, borrowers should be prudent and take into account potentially higher borrowing costs when signing up for new loans. An argument could be made, however, that if banks go slow in raising loan financing costs, businesses and individuals will have more to spend on investment and consumption, which helps the economy. Moreover, higher debt costs can exacerbate inflationary pressures.
At the same time, borrowers in Singapore do have options. Competitive forces help to keep NIMs in check – banks cannot aggressively raise loan rates while squeezing deposit rates, without risking losing customers.
In fact, financial institutions such as HSBC, Standard Chartered, Citibank Singapore, CIMB and Maybank often have to compete harder because they do not have a home advantage. Borrowers can therefore shop around when looking for a new home loan or refinancing an existing one.
Business sustainability
Banks, meanwhile, need to look after various stakeholders. These stakeholders include not just customers but also shareholders, who would cheer rising interest income that contributes to stronger profitability. Higher profitability can, in turn, drive share price appreciation and dividends.
Indeed, the share prices of DBS, OCBC and UOB have outperformed the Straits Times Index (STI), up about 7 per cent, 9 per cent and 14 per cent, respectively, versus the STI’s increase of around 5 per cent, between end-2021 and Nov 29, 2022.
Perhaps what matters is that boards and top management of banks grow profits and build sustainable businesses responsibly. Use the strong profits and support of capital markets to attract and retain talent, create jobs, invest in technology, enhance customer experience, strengthen risk management and grow via bolt-on acquisitions.
The locally listed banks operate from strong positions. Earlier this year, UOB announced deals to buy Citigroup’s consumer banking businesses in Indonesia, Malaysia, Thailand and Vietnam; and DBS inked a deal to buy Citigroup’s Taiwan consumer banking business.
Having strong local banks helps grow Singapore’s financial sector and enhances robustness in the banking system, as the banks can better handle any financial shocks. Having high-quality businesses on the local bourse such as the banking trio also helps those looking to invest for their retirement needs.
As business thrives, it will be important for the boards and management teams of the banking trio to behave humbly. The banks have benefited from factors such as the Singapore government’s various Covid-related stimulus packages, sound banking regulations as well as the city-state’s significant net in-flows of capital this year, because of its stability and social cohesion.
The bank chiefs are generously remunerated. With the trio poised to post strong full year numbers for 2022, may plenty of restraint be shown in the remuneration of the head honchos. This would be an effective way to show social solidarity and good corporate citizenship.
TRENDING NOW

Higher rates, weaker spending: Is the Philippines entering stagflation?
Ex-Nvidia CEO misled top lawyer on affair with Chinese businesswoman, sources say

‘I’ll be buying more’: Singapore investors pour into Nvidia shares on Jensen Huang’s exit
Nvidia approaches Arm CEO Haas as employees seek Huang's return, reports say

