

India’s growing population and rising consumption present investment opportunities
Discernment, discipline and operating capabilities required to generate attractive returns
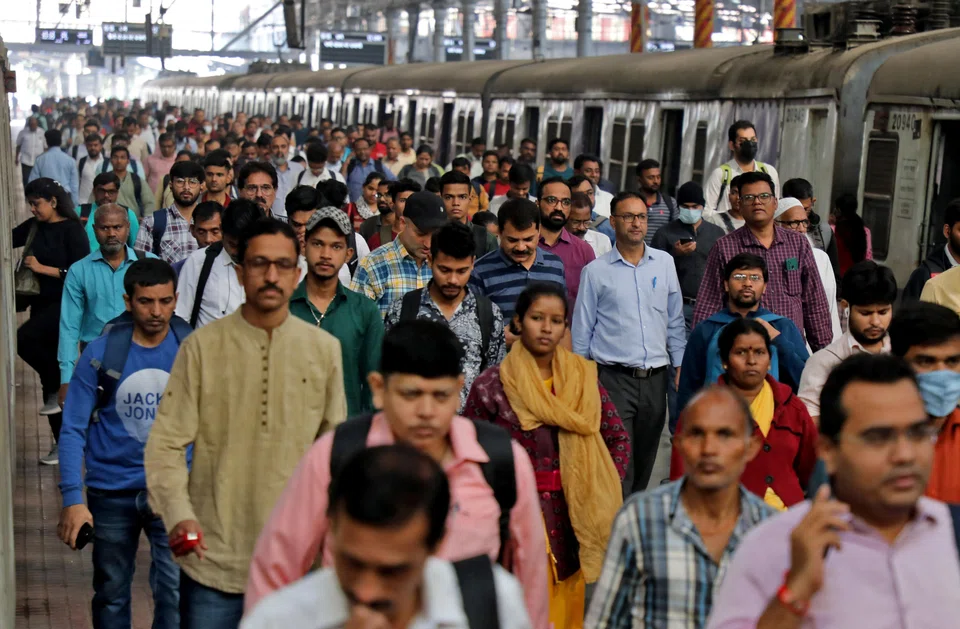
INDIA is expected to become the world’s most populous country this week. According to the United Nations, India’s population will hit 1,425,775,850 by Apr 15, surpassing that of China, the current frontrunner. The country’s population is then forecasted to reach 1.5 billion by 2030, and peak at 1.7 billion around 2064.
This in turn is expected to fuel a surge in consumption, the driving force behind the country’s rapidly expanding economy. India grew the second-fastest globally in 2022, and is set to take the lead this and next year, with its gross domestic product projected to increase by 6.1 per cent in 2023 and 6.8 per cent in 2024. The country’s consumer sector, which already accounts for around 60 per cent of its economy, is projected to expand at an even faster pace, with a compound annual growth rate of 9 to 10 per cent over the coming decade, to hit US$2 trillion in 2032. Notwithstanding near-term headwinds such as inflation and the depreciation of the rupee, India will also be the world’s third-largest economy by then, behind only the US and China.
Significantly, the composition of India’s consumption basket is expected to evolve. As education and income levels continue to rise amid the further development of the country, spending on higher-value goods and services will increase.
Three characteristics of the country’s population bode well for its consumption outlook.
Age, access and aspirations
India’s population is relatively young. The median age of people in the country is 28, with more than 42 per cent of them under 25. Millennials and Generation Z, whose peak years of earning and spending are still ahead of them, account for around 52 per cent of India’s population, compared to 47 per cent of the world’s.
India’s population is incredibly well-connected to the Internet, particularly via smartphones. The country has over 837 million Internet users and around 600 million smartphone users, with the latter expected to reach one billion by 2026. And thanks to having the world’s fifth-cheapest mobile data rate (US$0.17 per gigabyte), India also has one of the world’s highest per capita consumption of mobile data (19.5 gigabytes per user per month) and now accounts for over 20 per cent of global mobile data traffic. The digital arena has therefore become fertile ground for brands to engage consumers.
Indians are also increasingly showing a preference for branded products and services sold via organised channels and marketplaces. Deepening smartphone penetration across the country has provided netizens in second- and third-tier cities with as much exposure to brands as their peers in first-tier cities, leading consumers in small towns and big metropolises to have similar aspirations. Coupled with India’s improving e-commerce and payment infrastructure, this is fuelling a rise in online shopping. Accordingly, the country’s online shopper base of over 150 million people currently is forecasted to more than double to around 350 million people by 2026, and its digital consumer economy is projected to expand from US$538 billion in 2020 to US$1 trillion by 2030.
Categories, companies and capabilities
Given the robust macroeconomic fundamentals underpinning India’s consumer sector, investors have ploughed more than US$96 billion into around 4,000 deals in the sector over the past eight years. These account for some 40 per cent of all private investments in the country during that period. The vast majority, or around 95 per cent, of the capital deployed in the sector has been invested in relatively young companies that are still growing.
To make superior risk-adjusted returns though, investors need to be able to sift through the hype, discerning the wheat from the chaff. While the myriad attractive opportunities in India’s consumer sector may be apparent enough, it is tough to identify the companies and founding teams that hold the most promise and go on to realise their potential, especially amid the volatility and global uncertainties these days.
Categories that are supported by immutable consumer trends, long-term demand drivers, and structural tailwinds which are set to persist are more likely to stand the test of time. They are also better insulated from the vagaries of economic cycles and more conducive for generating all-weather returns.
Companies operating in such categories are therefore better poised for lasting success. The ones with the most growth potential are those with differentiated offerings, strong brands, and compelling narratives that resonate with their target consumers, as well as enduring competitive advantages. Those with prudent customer acquisition costs, loyal customers, and healthy unit economics are also more likely to achieve and sustain profitable growth, particularly if they have high repurchase rates.
To enjoy strong upside from investments in such companies, it is important to be mindful about entry valuations and ensure that they reflect the risk-reward profile of a business at each stage. India is also a market that relies less on leverage, and investors need to generate returns by working closely with portfolio companies to drive operational improvements and earnings growth as consumption continues to rise.
Discerning and disciplined investors with deep consumer insights, proven category expertise, and extensive operating capabilities are best positioned to reap rewards in India’s consumer market, which offers many more years of secular growth ahead.
Anjana Sasidharan is a partner at L Catterton, a global consumer-focused investment firm.






