

Singapore properties’ safe-haven premium shields S-Reits from Iran war headwinds
The Republic’s attractiveness to businesses and individuals will grow in a chaotic world
CONFLICT in the Middle East is driving higher inflation as elevated energy costs hurt businesses and consumers.
Many Singapore real estate investment trusts (Reits) will be hit by higher energy prices. Property operating expenses could rise, thus hurting net property income (NPI).
Crucially, higher inflation may dash hopes of the US Federal Reserve slashing interest rates, even with the looming change in leadership at the Fed.
Rate sensitivity
Reits are highly rate-sensitive. Lower interest rates mean lower financing costs, which help boost distribution income.
Meanwhile, higher interest rates raise a trust’s borrowing costs and lower the value of its properties, as higher capitalisation rates are used to value the said properties.
Under the income capitalisation method, a property’s assumed NPI is divided by the capitalisation rate to derive a property’s value. A property’s value and the capitalisation rate used are inversely related.
Property valuation declines, in turn, hurt Reits by raising gearing ratios possibly beyond permitted levels.
Crucially, many investors pile into yield plays such as Reits in a low-interest-rate environment, while underweighting Reits when rates rise.
In perspective, the five-year Singapore government bond yield was 1.7 per cent per annum on Apr 10, versus around 1.5 per cent per annum at the start of March and about 0.5 per cent per annum in April 2013.
Indeed, if interest rates trend higher over the long run due to factors such as rising fiscal spending and an ageing population, investor interest in Reits could wane.
The local bourse’s first Reit initial public offering (IPO) of 2026 saw UI Boustead Reit , which owns assets in Singapore and Japan, make a weak debut, trading below its IPO price.
Meanwhile, Lendlease Global Commercial Reit’s recent preferential offering drew valid and excess applications totalling 62.2 per cent of the new units on offer.
Over at CapitaLand Ascendas Reit , its recently launched equity-raising for gross proceeds of about S$903.5 million saw private placement and preferential offering units priced at the low end of the issue price range.
Going forward, might equity fundraising by Reits on the Singapore bourse slow down?
Nonetheless, despite the Iran war and rising geopolitical tensions, investors may be wise to back locally listed Reits with Singapore-centric property portfolios over the long term.
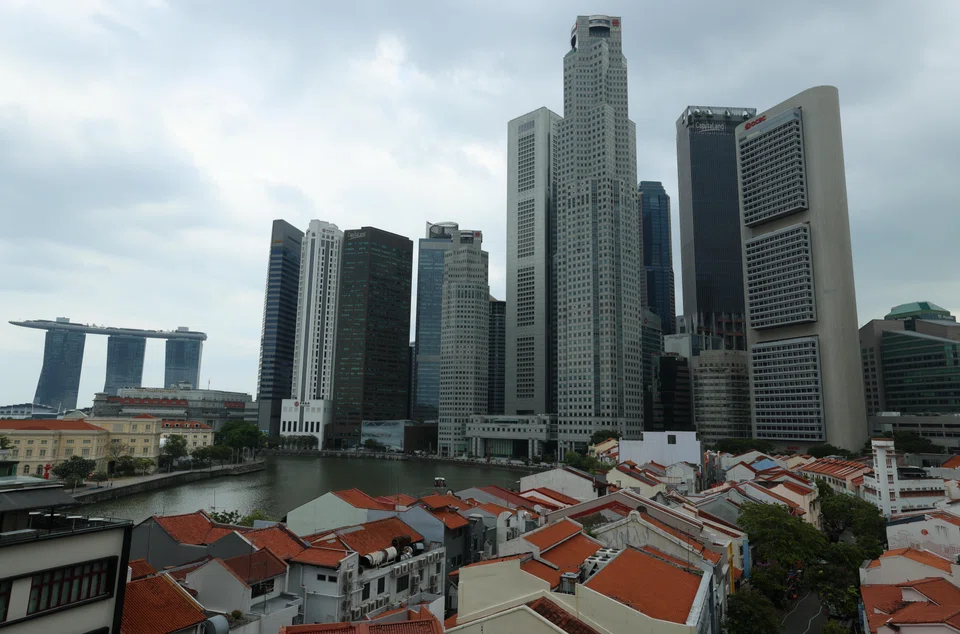
Physical properties here are valuable safe-haven assets and the Republic’s safe-haven premium could rise.
By buying Reits that predominantly own high-quality properties in the Republic, investors get exposure to good-grade Singapore investment properties.
Reits are subject to strict guidelines and have high levels of disclosure. The trusts are tax-efficient instruments and some trusts enjoy good trading liquidity.
Also, numerous Reits are backed by strong sponsor groups that provide asset-acquisition pipelines.
Moreover, a Reit investor benefits from having professionals manage the underlying properties.
Arguably, a golden age for Singapore physical properties beckons in a world rife with geopolitical conflicts.
Space users
One, in a chaotic world, Singapore’s pull as a place for people to live, work and play in might increase. The Republic offers stability and is in a peaceful neighbourhood.
Think of high-value-add businesses expanding here because talent wants to be based in safe and socially cohesive Singapore. Also, businesses making large capital investments over a multi-year time frame could view the Republic highly favourably.
Under the above scenario, premier office, business park, manufacturing and logistic spaces here will benefit.
Perhaps, the city-state’s stability and security will lead to it hosting more meetings, incentives, conferences and exhibitions – or Mice – activities.
Also, more international visitors, including high-spending ones, may visit Singapore for peace of mind, especially as many initiatives are under way to enhance the city-state’s tourism offering.
Hospitality and retail properties here will be major beneficiaries, should the above trends play out.
The Republic has been growing strongly in wealth management. Troubles flaring in other regions could add impetus to Singapore’s growth in wealth management. Such growth will boost demand for residential, office and high-end retail spaces, as well as luxury hotels.
Many Reits own high-quality Singapore properties. Such properties will see strong leasing demand should businesses and individuals place a growing premium on the Republic’s value proposition.
Strong demand from space users can, in turn, drive revenue growth, which may contribute to higher NPI and distribution income for Reits.
Investors
Two, while the capitalisation rates used to value physical properties here are generally low across the different property asset classes, capitalisation rates could remain stable or be compressed even if interest rates rise.
Amid heightened global uncertainties, investor demand for all types of physical properties here might grow as investors seek safe-haven assets.
Owning chunky Singapore physical properties gives investors exposure to the Singapore dollar, which is seen as a strong currency due to the nation’s fiscal strength and stability.
Also, supply gluts typically don’t exist as the supply of physical properties across asset segments is generally well-managed.
Foreigners seeking Singapore physical property may largely focus on non-residential properties, given that non-permanent resident foreigners and entities pay hefty additional buyer’s stamp duty (ABSD) to buy any home here.
Also, wealthy local residents looking to buy investment properties here may target non-residential properties as they face high ABSD rates when buying second or subsequent homes.
Over the long term, competition among investors for premier non-residential properties here could rise, thus driving up the value of such properties.
Therefore, Reits owning strong Singapore property portfolios could see their book values rise. And unitholders may occasionally enjoy a one-off boost in their distribution per unit if trusts sell assets and distribute gains to unitholders.
Given that the Republic’s physical properties may be among the best safe-haven assets in an increasingly troubled world, investors won’t go wrong investing in Reits that own strong Singapore property portfolios.
The days of investors flocking to Reits due to ultra-low interest rates, and trusts expanding rapidly through acquisitions financed by cheap debt are over. However, Reits owning high-quality Singapore properties can prosper because the allure of such properties will grow in a disorderly world.
TRENDING NOW

One-third of Singapore-listed firms at risk in severe AI downturn: MAS

‘Not done’: Keppel CEO Loh Chin Hua transformed the group, but says there’s ‘still a lot to do’

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

‘We don’t want to stay as we are’: CEO Patrick Ng builds a more resilient Huationg

