

It’s time to overhaul the Singapore stock market
A sustainable and effective way, more than a quick shot in the arm, is needed to revive struggling equities exchange
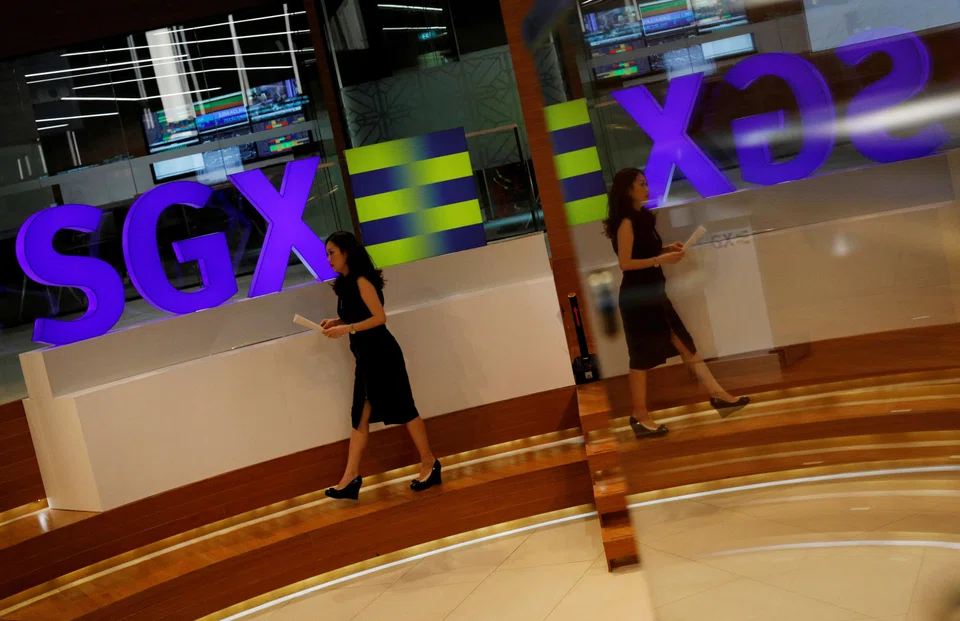
SINGAPORE’S equities market is clearly facing significant challenges.
Last year marked the worst year for listings since the Singapore Exchange (SGX) opened its doors in 1999. It had just six initial public offerings (IPOs) in 2023, down from 11 in 2022. Funds raised came up to S$47.2 million, a whopping 92 per cent decline from the year before.
This is part of a longer trend. As at July 2024, the total market capitalisation of companies listed on the Singapore bourse was S$815.2 billion, down from S$1.1 trillion in December 2017.
By comparison, the combined market capitalisation of companies listed on Nasdaq and the New York Stock Exchange grew by about 127 per cent and 21.7 per cent, respectively, from January 2018 to March 2024.
Closer to home, Indonesia was among the world’s top five IPO markets last year, with 79 new listings.
In stark and happy contrast, the Singapore Exchange Securities Trading’s market for real estate investment trusts (Reits) continues to shine.
From 28 listed Reits in 2012, there are now 40. Singapore was, last year, the fourth-largest Reit market in the world by market capitalisation.
In August, the Monetary Authority of Singapore (MAS) announced the setting up of a high-powered review group that would recommend measures to revive the Republic’s struggling equities exchange.
It is chaired by Minister for Transport and Second Minister for Finance Chee Hong Tat, and includes heavyweights from corporates, private equity and civil service. Creating the review group was a signal to the market that the government is serious about tackling the ailing stock market.
Without jumping ahead of the review group’s findings, here are a few perspectives as a lawyer who has been working on IPOs and other capital markets projects for more than 30 years.
The markets issue
We have a bifurcated market – divided between large corporates, such as local banks and Reits that institutional investors happily pile capital into, and small companies that suffer from low liquidity and investor interest.
In the past decade, brokerage fees have been reduced and stockbroking houses have cut research teams. Newly listed companies do not garner much research interest and therefore don’t get investor attention. This keeps these companies in a low-liquidity, low-valuation space, perpetuating the impression that an IPO may not be worth doing.
Recent delistings and privatisations of companies that were very much part of the stock-market success story – Eu Yan Sang, Osim, and lately the attempt to privatise Great Eastern – have further dampened sentiment. Reasons cited include low liquidity and poor market valuations.
On the international market, many companies with huge losses at the time of IPO still managed to list successfully. Think Airbnb, Uber and Tesla (which started turning a profit only nine years after listing).
This is because investors in a market focused on tech and other emerging business segments look at “growth over profit”, and value two metrics: potential for growth and the size of the market the company is entering.
This mindset is far removed from a traditional market such as Singapore’s, where assessing a company based on its price-to-earnings (P/E) ratio naturally requires IPO aspirants to be profit-making.
Another factor that contributes to lower liquidity in the Singapore market is online trading. A retail investor can pump funds into tech stocks listed and trading at more aggressive valuations in the United States from his mobile phone in Singapore.
Given the ease of cross-border investing, it may not be viable for the Republic to develop a stock market that tries to be the Asian rival of Nasdaq.
Perhaps a better approach is to develop the SGX into a more specialised market, such as a regional “go to” bourse for top South-east Asian companies in industries that Singapore investors understand.
We could also be a natural and neutral listing venue for companies not wishing to get into the cross hairs of fraught US-China relations.
Regulations
Market participants complain about the onerous process of applying for a listing in the Republic, notably unending questions lobbied by regulators and copious paperwork.
Even Catalist listings, which should be a shorter process as the offer document is cleared by the listing sponsor, can involve several rounds of detailed questions with responses running to hundreds of pages.
But the laborious process still sees some lemons – or duds – launching IPOs.
YuuZoo, an e-commerce and social media company, completed its reverse takeover in 2014 but shortly thereafter ran into problems. Its 2015 and 2016 revenues were found to have been overstated, and its former chief executive officer has since been charged for breaches under the Securities and Futures Act. This underscores the point that no amount of documentary verification can catch all cases of fraud.
Singapore’s stock exchange is in name a disclosure-based regime where caveat emptor is supposed to be the operating principle, having moved away from a merit-based process in 1998. But, in practice, there is still a patriarchal impetus to protect the public, especially retail investors.
Full adoption of a disclosure-based regime would require a number of changes.
First, there has to be effective public education so that caveat emptor really applies.
The regulator can then simplify the listing process by asking questions targeted at ensuring full disclosure rather than as a disguised merit-based evaluation, and thus enabling quicker time to market for IPOs.
Finally, where there are violations, the enforcement process must be rigorous, robust and speedy.
Currently, the SGX’s enforcement arsenal is thin, with little power beyond a rap on the wrist or disqualification from listed directorships, which would not faze foreign bad actors.
It also has the power to delist errant companies, but this has adverse implications for minority shareholders – usually the class that needs protection.
In addition to beefing up regulatory enforcement rights and changing rules for a fairer playing field for all shareholders, where offences have been committed, the investigation and prosecution should be done quickly to enhance public confidence in the market.
For a disclosure-based model to work, stakeholders must be equipped with the power to hold the company and its directors accountable. Changes to the law to facilitate self-help action by minorities are needed.
Presently, shareholders not engaged in management or represented on the board have scant access to information. An activist shareholder wishing to write to other shareholders about a complaint has no avenue to contact them, as the scripless trading system means that most, if not all, shares are registered in the name of the Central Depository.
We should consider having a legal avenue for a shareholder to apply to the courts for an order to disclose information. Statutes should provide for more effective class action lawsuits.
As a corollary to this, a modest form of conditional funding arrangements for expensive court cases would allow litigation funders to provide financing where the payout is based on success (and not a percentage of damages awarded). Funding of this nature is already permitted for international arbitration.
Horizon scanning
The MAS review group has been given a broad remit – to strengthen equities market development in Singapore. It may well conclude that certain major exchanges will draw the lion’s share of companies in specific industries.
The question would then be: What is Singapore’s natural advantage and what should its equities market of the future look like?
I hope the group will cast its review net wide and resist the temptation to just give the market a quick shot in the arm. Let’s overhaul the system in a sustainable and effective way.
The writer is joint managing partner at TSMP Law Corporation






