Link by link: How the region can strengthen its supply chain capabilities
Current supply-chain trends are positive for South-east Asia, but it cannot be assumed that they will continue or, if they do, at the same pace
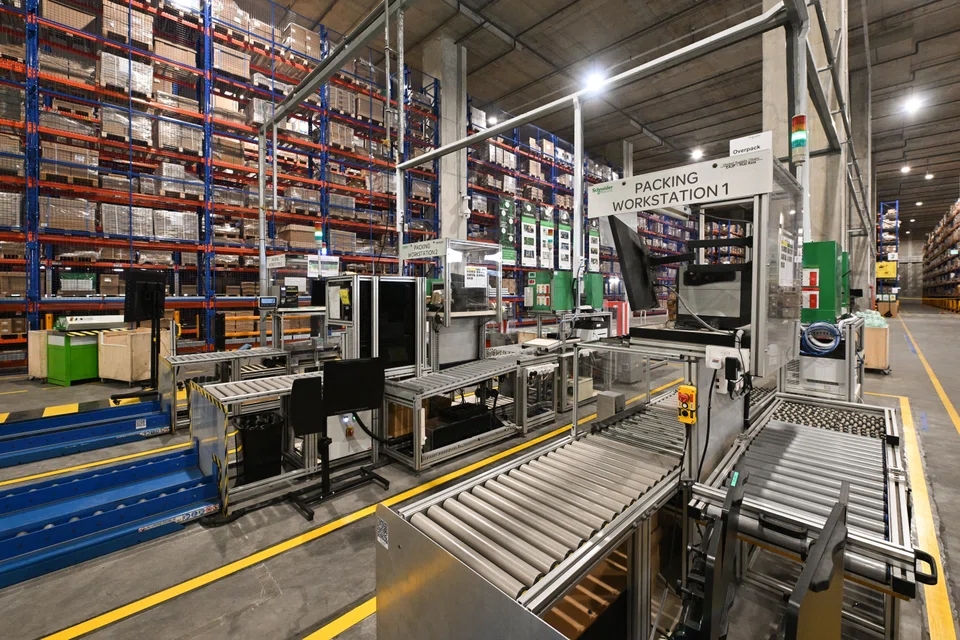
ONE of the many lessons of the pandemic is that companies that diversified their supply chains – for example, by contracting with two or more sources for materials – rode out the economic storm better. In Asia, this strategy is sometimes known as “China+1” – meaning that while China will remain critical, there is increased scope for other Asian markets.
Supply chain disruption is inevitable, given the growing complexity of the global economy. One electronic parts maker told us, “When we move two or three parts, we create tens or hundreds of new supply chain links around the world.”
Due to economic, political and regulatory factors, supply-chain diversification is gaining traction, with companies across Asia adopting the China+1 approach. It is telling that foreign direct investment (FDI) in greenfield manufacturing in China dropped 17 per cent from 2019 to 2023, while it rose 20 per cent in South-east Asia.
Indonesia and Vietnam are particularly high performers, with FDI rising strongly in both countries. As a result, their exports have grown, with Vietnam excelling in electronics and Indonesia in metals and chemicals. Malaysia has also done well, with exports rising an average of 7.7 per cent a year since 2019; standout sectors include semiconductors and automotive.
Most of the goods are, however, not going far; almost 90 per cent of South-east Asian exports stay within the Asia-Pacific region, an indicator of how closely-knit regional economies are.
China+1 is usually considered as a move by global manufacturers out of China. But the region is also attracting considerable investment from Chinese manufacturers moving production out of their home market. Chinese FDI to South-east Asia reached US$24 billion in 2023. It is a real +1 strategy of outsourcing portions of production and moving it closer to raw materials, demand or less-extensive labour.
These trends are positive for South-east Asia, but it cannot be assumed that they will continue or, if they do, at the same pace. One major challenge is infrastructure. Building manufacturing and other facilities and ensuring that goods and services can get from Point A to B is essential if the region is to support exports and develop its supply chain capabilities.
Governments have stepped up. Since 2010, Vietnam has markedly upgraded its transport infrastructure, and another US$117 billion in investment is planned by 2030, including the Long Thanh International Airport. In Malaysia, funding is in the works to expand Penang International Airport and to redevelop Subang Airport. Major projects in Indonesia include the Jakarta-Bandung high-speed railway and the expansion of Patimban Port. Thailand is expanding the Bangkok airport and the Laem Chabang deep seaport.
These four countries alone have announced US$255 billion in infrastructure investment. In addition, private companies are also taking action, by developing a common export infrastructure. As one institutional investor in Indonesia noted, manufacturers are beginning “to build their own roads, ports, full logistics operations – all next to each other”. That might be an invitation to global infrastructure players to offer efficient consolidation.
McKinsey estimates that just for Indonesia, Malaysia, Thailand and Vietnam, there is still a US$63.6 billion gap between existing or announced infrastructure investment and what could be needed to meet future trade flows. This is a challenge – and an opportunity for private investors and logistics companies.
For example, Thailand has ambitions to become a major player in the burgeoning market for electric vehicles; finding battery storage solutions is important, and could be a space for private investment to move into.
Vietnam has moved briskly towards greater containerisation; keeping up the pace would help move its electrical components more efficiently.
Indonesia could benefit from investments in digital and analytics capabilities to support its downstream processing industries. For logistics companies in particular, there appears to be untapped potential in areas such as warehousing, port infrastructure, and brokerage services. Filling those needs could be profitable for companies – and is essential for South-east Asia to meet the moment.
In addition, the role of sophisticated logistics hubs such as Singapore is getting more complex. An executive in a major freight forwarding company noted, “Industries that need high standards of data protection, such as e-commerce, will tend to place hubs in locations that have a strong legal framework and can protect the privacy of their customers. Furthermore, our supply-chain planning and optimisation capabilities are becoming more important, and such teams require talent to be concentrated in one place. This concentration of talent is hard to replicate quickly outside of developed locations such as Singapore.”
China is and will continue to be the most important player in Asia for some time to come. To offer some context, China’s exports in 2023 were almost double that of all of South-east Asia’s. But when it comes to economics, change is the only constant. We believe the region’s increasing economic clout and the global emphasis on future-proofing supply chains makes it a promising choice for supply chain diversification. The challenge for business leaders and governments is to ensure that they are ready for it.
The writers are from McKinsey & Company’s Singapore office. Stas Melnikov is an associate partner and Mukund Sridhar is a senior partner.