

Manulife US Reit recapitalisation: Placement of new units to Mirae should be priced at NAV
This would limit the dilutive impact on existing unitholders, and demonstrate Mirae’s credibility as a sponsor
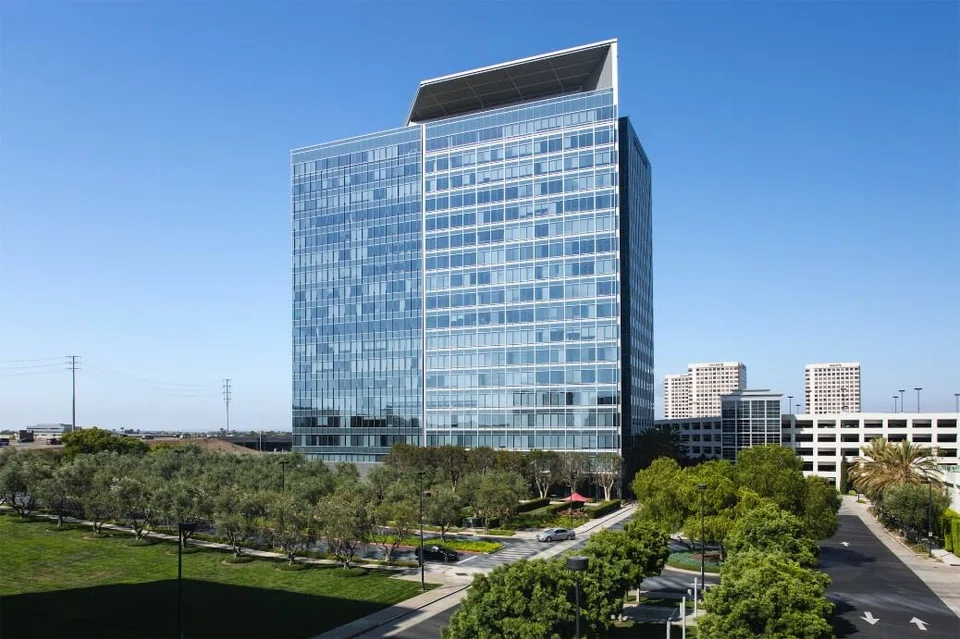
THE terms of Manulife US Reit’s much-anticipated rescue by Mirae Asset Global Investments could be unveiled in just a few weeks.
A firm deal could well trigger a snap-back in the market price of the US office real estate investment trust’s (Reit) units. But the scale of any rebound – and the extent to which investor confidence recovers – will probably depend on how much dilution the deal inflicts on unitholders.
The manager of Manulife US Reit said in its Q1 2023 operational update on May 11 that due diligence related to the transaction with Mirae had been substantially completed, and that the key terms were in the process of being negotiated.
“We are working expeditiously and aim to update unitholders with the finalised proposal by Q2 2023,” the manager added.
The deal is expected to involve Mirae acquiring the manager, and taking up a placement of new units in the Reit.
Interestingly, Mirae does not appear subject to the same 9.8 per cent ownership cap as the Manulife group. This could increase the dilution risk for unitholders of Manulife US Reit, depending on the specific terms of the deal.
Units in Manulife US Reit have been on a downward slide since its manager was forced by a leak in March to confirm that a deal with Mirae was afoot.
Manulife US Reit closed on Friday (May 19) at US$0.138 – a discount of nearly 75 per cent to its net asset value (NAV) as at Dec 31 of US$0.55 per unit.
The manager of Manulife US Reit has said that any private placement of new units to Mirae will be subject to the approval of unitholders. But the manager has also presented the deal as the only viable option.
When the terms of the deal are announced, eliciting a rebound in the Reit’s market price, unitholders will probably feel enormous pressure to give their consent, despite the dilution they will suffer.
Potential dilution
The problem that Manulife US Reit faces is that the value of its office properties has declined, and its gearing is now bumping up against the statutory ceiling of 50 per cent. This prevents it from drawing down more debt to modernise and enhance its properties, or even fund its leasing costs.
Last month, Manulife US Reit said its sponsor group had agreed to take a property called Tanasbourne off its books for US$33.5 million. Besides this transaction, the Reit has not been able to raise any funds through asset sales.
The manager said in its Q1 2023 operational update that it had attempted three asset dispositions between April and November 2022. But these deals were scuppered by rising interest rates and potential buyers being unable to obtain funding.
Manulife US Reit has also not sought to raise funds through a rights issue. The manager has said this is because the sponsor group’s support for such an exercise would be capped at 9.8 per cent, which may create concerns for potential underwriters.
Instead, investors have been told that the best way forward is for Mirae to acquire the manager and lead a recapitalisation of the Reit.
Analysts covering Manulife US Reit appear to have accepted this narrative.
DBS Group Research said in a report last week that an equity injection of some US$175 million would be sufficient to bring Manulife US Reit’s gearing down to 40 per cent – a level that would provide it with room to withstand a further 20 per cent devaluation in its assets.
The big question is how much of this potential equity injection will come from an initial placement to Mirae versus a subsequent rights issue to all unitholders; and at what price all these new units will be issued.
DBS Group Research said in its report that raising US$175 million by issuing new units at US$0.14 per share would result in Manulife US Reit’s distribution per unit (DPU) being diluted by 44 per cent.
On the other hand, issuing the new units at a 10 per cent discount to US$0.14 would result in greater DPU dilution of 47 per cent.
But units in Manulife US Reit may have already priced in this possible dilution. DBS Group Research said in its report that the Reit is currently trading at a “fully diluted” yield of about 19 per cent.
The research house sees the Reit trading up to US$0.24, a level that would imply a fully diluted yield of 11 per cent.
Will this rebound mark the beginning of a long-term recovery in Manulife US Reit, led by its new sponsor Mirae? Or should the Reit’s long-suffering unitholders use it as an opportunity to sell?
Gesture of commitment
This column said last month that Mirae might be making a mistake in acquiring control of Manulife US Reit. Besides having to support the Reit through its current downturn, Mirae would also be turning itself into a target for the investor disgruntlement currently directed at the Manulife group.
Much of the decline in Manulife US Reit this year has arguably been due to a growing realisation that its current sponsor was not going to provide it with the support it needed, and that the entry of a new sponsor group would result in significant dilution for unitholders.
As Mirae appears to be moving forward with its plans to take control of Manulife US Reit, it should perhaps offer the Reit’s unitholders a gesture of its long-term commitment.
Here is one suggestion: Mirae should agree to inject fresh equity into Manulife US Reit through a placement of new units priced at the Reit’s current NAV.
This might seem to be a big ask, given the steep discount at which Manulife US Reit is currently trading versus its NAV. But Mirae would only be paying the equivalent of the professionally appraised value of the Reit’s underlying property assets – which any committed Reit sponsor ought to be willing to do.
By injecting fresh equity into Manulife US Reit at book value, Mirae would also be limiting the dilutive impact of its investment on the Reit’s existing unitholders and demonstrating its credibility as a sponsor.
Indeed, providing Manulife US Reit with equity capital on terms that the market currently will not would be reminiscent of the manner Mapletree Investments handled the merger of Mapletree Commercial Trust (MCT) and Mapletree North Asia Commercial Trust (MNACT) last year.
To win over reluctant investors on both sides of the deal, Mapletree Investments backed a S$2.2 billion preferential offering by MCT at slightly over S$2 per unit – which was above MCT’s market price at the time. This enabled MCT – which has since been renamed Mapletree Pan Asia Commercial Trust – to pay MNACT unitholders the equivalent of book value for their units in cash.
Being able to claim it is as committed as any leading Singapore Reit sponsor would help Mirae greatly in garnering the investor support Manulife US Reit needs to chart a path to recovery and become an effective asset securitisation vehicle once more.
The writer owns units in Manulife US Reit.
TRENDING NOW
Nvidia preparing to oust CEO Jensen Huang who had second affair with exec: reports
8M Real Estate said to be buying about 50 shophouses for around S$500 million
MSCI removes more Indonesian stocks, dealing fresh blow to market amid reform push
Swiftdata, owner of Nvidia-linked Megaspeed, lists address occupied by interior design firm

