

MAS may want to nudge banks to standardise fintechs’ access to API for the benefit of SMEs
Smaller fintechs in Singapore have little leverage to push incumbents to remove restrictions on customer data; MAS could play a significant role
[SINGAPORE] A recent report by think tank Fintech Nation on the lack of API access possibly stifling small and medium-sized enterprise (SME) lending points to a dysfunction in the financial sector.
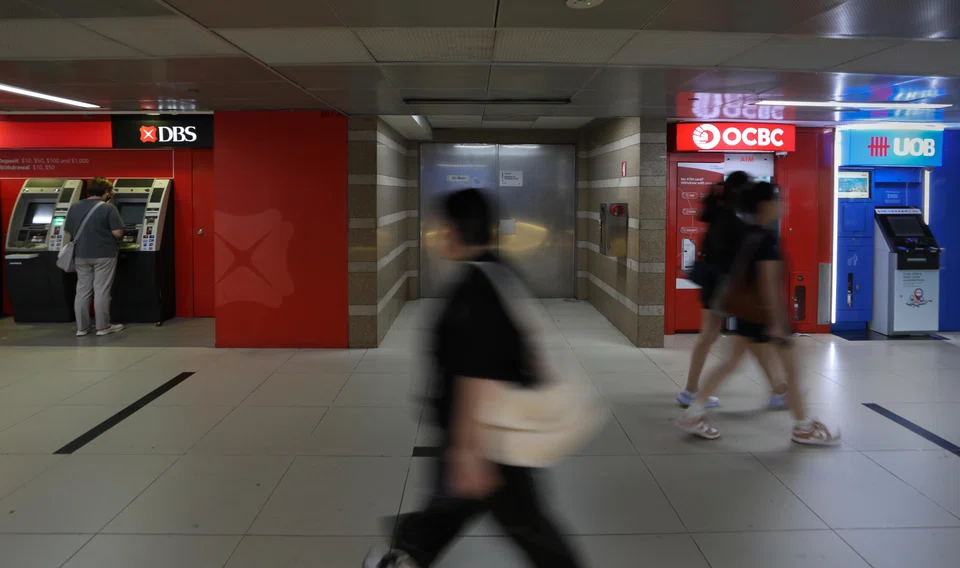
API refers to application programming interface, a protocol that allows for two different software programs to talk and exchange data. At the moment, the major banks in Singapore grant API access to only certain platforms, making it difficult for fintechs to get credit information on their customers.
Thus, despite the Singapore financial sector’s advanced digitalisation, SMEs that are seeking loans from fintech SME lenders are forced to download and send PDFs of financial statements of bank accounts. This results in the fintechs having to invest in manpower to tackle the manual process of reformatting these statements just to assess if the SME can be extended a loan. If they had API access, they could have pulled the data digitally from local banks.
The Monetary Authority of Singapore (MAS) could thus find itself in a quandary.
Despite the regulator having laid out guidelines for a more open financial services sector, traditional banks are gatekeeping digital access to their customers’ data even though consent has been sought and given for these fintechs.
While Fintech Nation’s report was a way to highlight the dysfunction, there are a number of concerns from traditional banks over providing API access, ranging from security and privacy to costs and competition.
It is thus clear that prerequisites are needed to determine if a fintech can qualify for API access to the traditional banks in Singapore.
These include determining the critical mass of SME customers needed, choosing the security and data-privacy prerequisites for API access, and even deciding the cost of doing an API call. Without any compliance checklists, fintechs are in the dark on what can be done to negotiate API access.
This is certainly an area where MAS can step in to nudge the industry to decide what is the best model that would satisfy the banks’ concerns and allow for more SME financing.
The regulator has done this before, in nudging the buy-now-pay-later industry to self-regulate with a code of conduct and a separate credit bureau.
The financial services sector has not been averse to sharing customer information with one another.
For example, there is the Singapore Financial Data Exchange, where retail customers can give consent and see their entire investments and savings in one dashboard in any banking app they frequent.
When it comes to industry inertia, the regulator is the only one that can push incumbents to move and take action.
In most David-and-Goliath situations, the smaller player has little leverage to make the incumbents move.
Traditional banks say that there are competition concerns over opening up API access to fintechs, as SME customers could potentially get a loan from these lenders instead of the bank. While these concerns are valid, the onus is on the sector to work out a win-win situation.
This could be anything from charging fintechs for API calls on a bank’s SME customers to working out a partnership that would allow customers, who might not be as credit-worthy to a bank, to be funnelled into these fintechs.
It is now up to the regulator to be the one to draw all these parties to the discussion table to figure out a palatable solution that both banks and fintechs can live with.
TRENDING NOW
Nvidia prepares to oust Jensen Huang after news of second affair, with executive: reports

Higher rates, weaker spending: Is the Philippines entering stagflation?
Special dividend for SIA’s 80th anniversary? CEO says extra payout will need board’s nod
Genting Singapore Q3 net profit falls 42.2% to S$54.7 million on softer premium gaming

