

Mirae should think twice about Manulife deal
Singapore’s leading Reits sponsors are setting tough standards, and investors are becoming increasingly knowledgeable and independent-minded

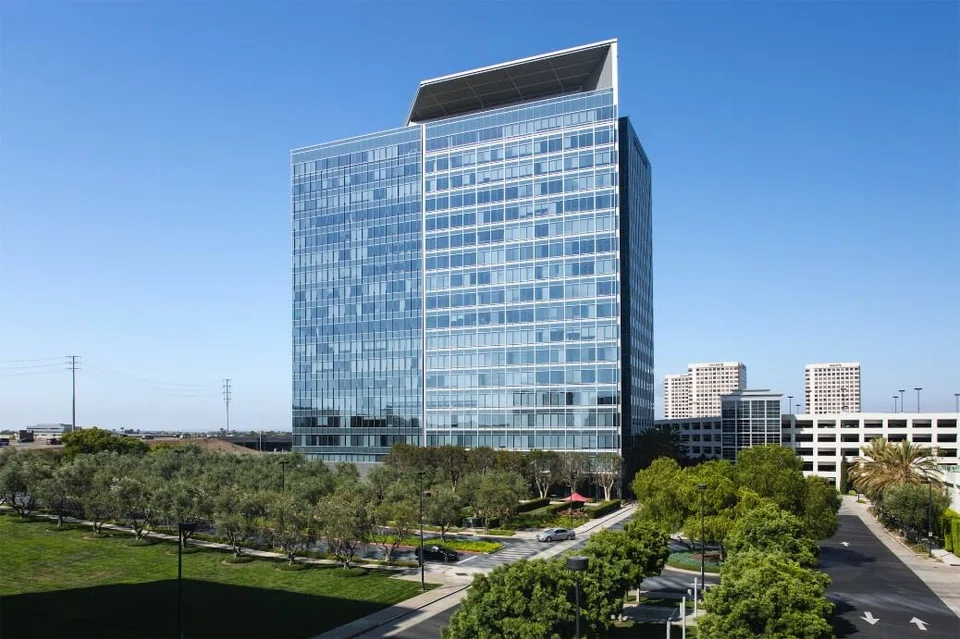
THE brief positive reaction in the market last month to news that Manulife US Reit’s manager might be acquired by Mirae Asset Global Investments was something of a surprise to me.
While Manulife US Reit has performed very poorly with the backing of the Manulife Group, any new sponsor group that forks out a substantial amount of money for the manager will likely be motivated to rapidly expand the real estate investment trust (Reit)’s portfolio – which could mean dilutive placements and rights issues.
It was also surprising to me that Mirae was reportedly the “preferred bidder” for the Manulife US Reit platform, and that it had beaten out a number of other candidates. Why is there so much interest in acquiring control of a Reit with a deflating property portfolio, excessive gearing and units trading at a deep discount to book value?
Mirae would arguably be far better off forming its own Reit platform from scratch. It would be able to pull together a portfolio of properties attractive to investors, and assemble a capital structure optimised for growth.
More importantly, Mirae would not be putting its brand name and reputation on the line by taking on Manulife US Reit’s disgruntled unitholders.
With leading sponsor groups in Singapore’s Reit sector setting tough standards, Mirae should give itself the best possible chance of making a good first impression in this market. Avoiding a potentially messy entanglement with a struggling Reit would be a sensible first step.
Selling assets makes sense
Despite the fillip of excitement following the news about Mirae, the market price of Manulife US Reit continued sliding over the past month. On Thursday (Apr 6), it closed at US$0.21 – an appalling 62 per cent discount to its book value of US$0.55 (excluding distributable income) as at Dec 31.
Clearly, raising additional equity at this point would not make sense from the perspective of unitholders. With rising interest rates, a slowing US economy, and the continuation of hybrid work arrangements, it is possible that the value of Manulife US Reit’s property portfolio will be marked down further.
A more appropriate course of action for Manulife US Reit would be to sell its weakest properties. This would crystallise a portion of its book value, and reduce its currently high gearing – which stood at 48.8 per cent as at Dec 31, just short of the statutory ceiling of 50 per cent.
With reduced gearing, the Reit would have some breathing room to pursue strategic initiatives to lift the income potential of its remaining assets. It might also enable the Reit to acquire assets in more promising fields.
Another alternative would be for Manulife US Reit to liquidate its entire portfolio. Even if the assets fetch slightly less than current book value, unitholders would probably get much more than if they were to sell their units in the market.
The obvious consequence of this is Manulife US Reit’s manager would lose its source of income. In effect, the unitholders would be cashing out at the expense of the sponsor group.
Regulatory scrutiny warranted
By contrast, the sale of Manulife US Reit’s manager would enable the sponsor group to cash out while investors are left holding units trading at deeply discounted prices.
On Mar 15, the manager of Manulife US Reit confirmed it is in discussions with Mirae about a “potential transaction”. It said the deal may see the Korean asset management group acquiring the manager and subscribing to new units in the Reit.
But Manulife US Reit’s manager denied on Mar 17 that the transaction would be worth a reported 200 billion won (S$206.4 million). It said the non-binding proposal from Mirae does not contain any reference to such a figure.
Tellingly, it added that the only monetary amount in the proposal relates to the purchase price for the manager.
Given that the interests of Manulife US Reit’s sponsor group and unitholders might not be aligned under a potential deal with Mirae, some regulatory scrutiny is probably warranted.
For instance, Singapore’s market regulators could examine whether it is entirely appropriate for Citigroup Global Markets Singapore to be involved in any deal that involves the sale of the manager.
On Nov 25, 2022, the manager of Manulife US Reit said Citigroup had been appointed as its financial adviser. It stated then that Citigroup would assist a strategic working group formed by the manager to review various options to enhance unitholder value.
Rising standards for Reits
Manulife US Reit is not the only Singapore-listed Reit attempting to improve its viability. Other Reits have successfully repositioned themselves over the last few years with the support of their respective sponsor groups.
Back in September 2020, the manager of CapitaLand Retail China Trust unveiled an expanded investment strategy that would see the Reit diversify its portfolio to include offices, business parks, logistics facilities and data centres. It was renamed CapitaLand China Trust in January 2021.
CapitaLand Mall Trust (CMT) also expanded beyond retail properties in 2020 by acquiring CapitaLand Commercial Trust through the issue of new units.
To sweeten the controversial deal, the manager of CMT waived its acquisition fees of some S$111.2 million. CMT subsequently changed its name to CapitaLand Integrated Commercial Trust.
Then there was Mapletree Commercial Trust (MCT)’s acquisition of Mapletree North Asia Commercial Trust (MNACT) last year. To win over reluctant investors on both sides of the deal, Mapletree Investments backed a S$2.2 billion preferential offering by MCT at slightly over S$2 per unit that enabled MCT to pay MNACT unitholders in cash instead of new units.
MCT was renamed Mapletree Pan Asia Commercial Trust, and it is still trading nearly 10 per cent below the price it issued new units to Mapletree Investments last year.
Meanwhile, Reit investors are becoming increasingly knowledgeable and independent-minded. Minority unitholders of Frasers Hospitality Trust last year rejected an offer from its sponsor group, even though the offer price was a premium to book value.
In 2020, dissident investors led by Quarz Capital Management scuppered the proposed merger of Sabana Industrial Reit and ESR-Reit. Since then, Quarz has continued to pressure Sabana’s manager to focus on delivering value to investors organically.
Ahead of Sabana’s annual general meeting (AGM) on Apr 25, Quarz is rallying unitholders to vote against the resolution authorising the Reit manager to issue new units.
Manulife US Reit – which is due to hold its own AGM on Apr 20 – faces a long road ahead to once more become a useful asset securitisation vehicle for its sponsor group. Mirae should carefully consider if it is paying an appropriate price for the Reit’s manager, and whether it has the resources and fortitude necessary to support the Reit through its rehabilitation.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Morgan Stanley investment-bank list leaked in email boo-boo

Could Grab CEO Anthony Tan’s US$30 million share purchase be aimed at reassuring investors?

From folding clothes to factory work: Why China is sending humanoid robots to school

