

More disclosures tied to value creation could be just the ‘culture shock’ the market needs
Entrenched mindsets that fester in short-term thinking about corporate governance could exact a steep cost
[SINGAPORE] When the market regulator proposed enhanced disclosures by company boards to promote value creation and investor engagement, murmurs of push-back predictably started to echo through the financial district.
This is understandable. Deep-seated corporate behaviour and entrenched cultures are incredibly difficult to shake – and for years, segments of the local market have operated comfortably behind closed doors, treating executive compensation as a private matter divorced from long-term shareholder returns.
While the reaction to the proposals to raise standards for transparency is entirely expected, it is also fundamentally wrong.
For one thing, the Singapore stock market is currently enjoying a rare moment of optimism.
The Straits Times Index – representing Singapore’s 30 largest blue-chip stocks – is pushing higher; it has advanced 27.9 per cent in the past year.
The iEdge Singapore Next 50 Index, or the next 50 largest and most liquid counters on the Singapore Exchange (SGX), has climbed 32.7 per cent.
Capital is flowing to asset managers through the government’s Equities Market Development Programme (EQDP), which has brought a massive S$6.5 billion war chest into play.
Trading volumes are also showing real signs of life. In March, the total securities market turnover value on SGX rose 78 per cent year on year to S$52.8 billion, and the securities daily average value grew 62 per cent to S$2.4 billion.
The real work ahead
It is tempting to look at these green shoots and declare the revival a resounding success.
State-backed liquidity acts as premium fuel, naturally lifting prices and generating excitement, but throwing money at a problem does not fix the underlying structural faults.
If the corporate engine leaks, that fuel simply burns away without moving the needle on shareholder returns.
This brings us to the real work ahead. What Singapore Exchange Regulation (SGX RegCo) is gunning for is essentially a change in culture.
Last week, the frontline regulator proposed new rules demanding that listed companies disclose the exact metrics used to determine executive remuneration. Crucially, companies must explain how this remuneration aligns with long-term shareholder value creation.
The proposals further push for clearer dividend policies and better investor relations practices.
Yet, critics say these rules are too onerous.
Some of the feedback is that the new regulations will increase compliance costs, especially for smaller companies already struggling with tight operating margins. There are concerns that this will devolve into a box-ticking exercise.
But dismissing better governance as a costly administrative burden misses the point.
A box-ticking approach is a choice made by lazy boards, rather than an inherent flaw in the regulation itself. If a listed company views the act of explaining how its chief executive creates value as an unreasonable burden, investors should ask very hard questions about what exactly they are funding.
The argument regarding smaller companies is equally flawed. Transparency does not require a massive budget. It requires honesty and a clear strategy from the top.
Small and medium-sized enterprises make up a significant portion of the local market. They cannot be given a free pass on basic governance under the guise of cost-saving. When companies go public, they accept the obligation of public scrutiny.
The latest proposals must be viewed as part of a broader, sustained strategy to fix the market’s core culture.
Consider the recent push to encourage forward guidance. Asking companies to provide a clearer picture of their future earnings met with similar groans. Critics argued it was too difficult or too legally risky.
However, if executives are required to lay out their strategic targets, their pay should naturally reflect whether they actually hit those targets.
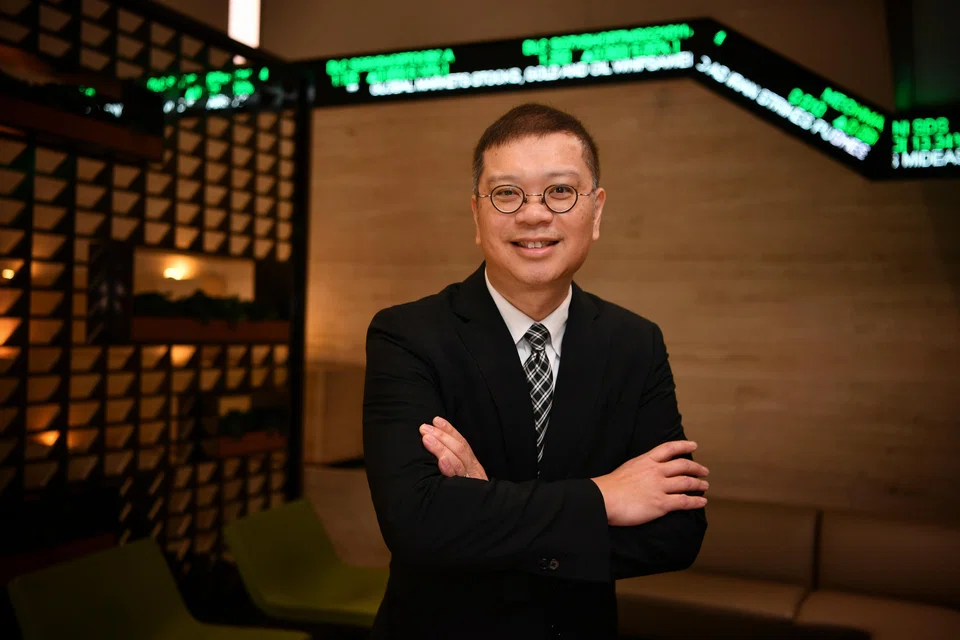
As SGX RegCo chief executive Tan Boon Gin pointed out at the media briefing to unveil the proposals, high-quality investor relations supports value creation by signalling intentions and increasing trust. Good communication ensures the market accurately reflects a company’s performance, effectively closing the valuation gap.
If a company does not pay dividends because it is in a growth phase and needs to reinvest its profits, it should state this clearly. Investors can then decide whether they agree.
Regulation does not drive profitability per se. But it forces boards to sit down, look hard at their structures, and justify them in plain English. The ultimate goal is to ensure management and board have their heads in the right places.
A sharp comparison
Some market participants want SGX RegCo to be even more prescriptive, suggesting that we emulate Japan’s demand for concrete plans to move price-to-book ratios above one.
However, Japan’s value-up programme has been more than a decade in the making. Singapore is only at the beginning of this journey.
Tan drew a sharp comparison to the Japanese city of Seki, which has built an 800-year ecosystem for crafting the world’s best blades.
“I’m not saying that we’re going to need 800 years,” he quipped, but noted that the impact that regulation has on value creation will take time to yield results.
Market participants need time to build capabilities, alter their practices, and develop networks. Entrenched corporate behaviour does not change overnight. But we must not let the current wave of liquidity distract us from this essential groundwork.
The EQDP gives the market a much-needed jolt of energy, providing the breathing room necessary to make hard structural changes. If we cave to the short-term complaints of those who prefer the comfortable old ways, we will waste this opportunity.
A quick bump in liquidity is the easy part. Building an ecosystem in which companies consistently deliver structural value is the true test – and we have a long way more to move.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

