More structure needed before MAS’ proposed transition credits can fuel coal’s phase-out
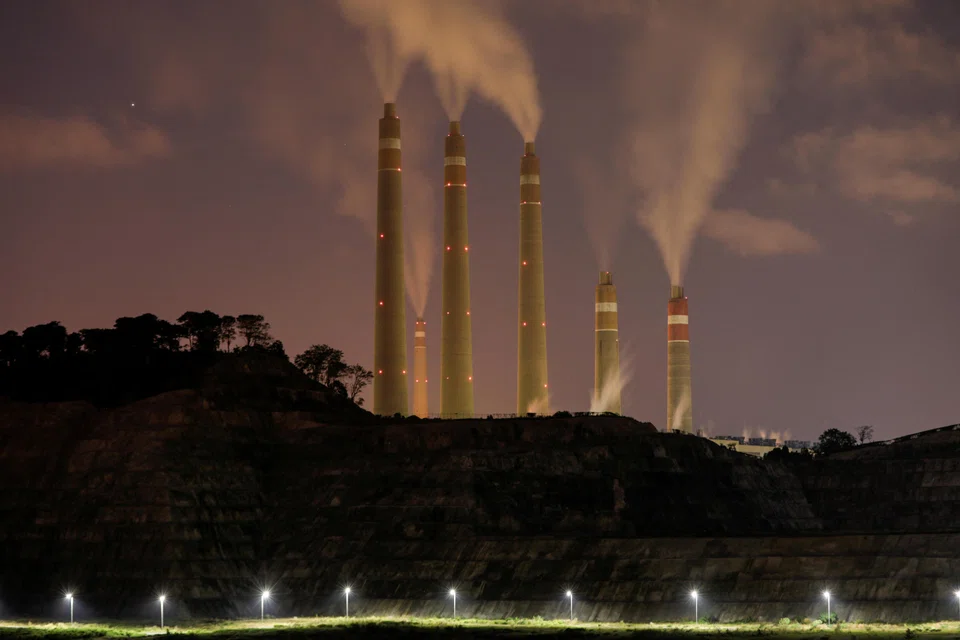
IMAGINE you’re an investor in one of the 2,000 or so coal plants in South-east Asia.
The coal plant is still relatively young (the region has one of the youngest fleets of coal plants in the world), and you’ve got a power purchase agreement with the government to provide electricity for another 15 years. You’ve spent considerable sums of money building this plant, and that purchase agreement is how you’re going to make back your investment.
Asking you to retire your plant five years early would be asking you to take a loss, so there’s no way you’re going to do that.
But what if you didn’t have to lose money? You could potentially recover the lost income if you could sell credits for the emissions avoided by retiring the plant early, and those credits attract a high-enough price.
That’s the idea behind “transition credits”, which the Monetary Authority of Singapore (MAS) is exploring.
In a working paper jointly authored with McKinsey & Co, the financial regulator estimated that a hypothetical 1 GW coal plant in Indonesia with 15 years to go on a power purchase agreement has a net present value of about US$310 million. Retiring the plant five years early would reduce that value to about US$240 million, leaving an “economic gap” of about US$70 million. That represents how much investors would lose from phasing out the coal plant.
If the coal plant were replaced with renewable energy, selling credits for the avoided emissions could be enough to cover that gap if the credits were priced at about US$11 to US$12 per tonne of avoided emissions, based on the model.
Wild cards
Whether transition credits will take off may come down to a few factors.
The first is the level of support among regional governments not simply for transition credits but for coal phase-out as well. One of the key principles of high-quality credits is that the emissions reduction should be sufficiently “permanent”.
One proposed safeguard for permanence is that the host jurisdiction, where the coal plant to be retired sits, must commit to having no new coal plants beyond what is already planned. This sounds great on paper; but in practice, it might be challenging to enforce.
The strength of the host jurisdiction’s commitment ultimately rests on the government of the day; and in developing countries, political risks are high on the list of “What can screw things up?”.
The paper also deliberately takes a neutral approach towards standards and methodologies, acknowledging that there are independent efforts on those fronts from the Coal to Clean Credit Initiative, Gold Standard, the US Energy Transition Accelerator and the World Bank. The MAS framework is meant to work with any methodology.
Too many competing standards and methodologies can hinder getting a critical mass of projects and credits to create a viable asset class.
One potential source of friction lies with the question of what is considered to be an acceptable replacement source of energy for coal.
One side of the debate argues that lower-emitting alternatives, such as natural gas or co-firing, should be allowed because not every part of the world is physically or economically able to support renewables at this time. The other side argues that allowing non-renewable, lower-emitting replacements locks in new sources of emissions that will eventually create new but similar phase-out challenges as coal.
This can be a delicate matter with existential implications. Standards that are too harsh may not attract enough phase-out projects. Those that are too lenient will not attract enough capital from wary investors. The wrong calibration could make or break coal phase-out.
Timing it right
One complication with transition credits is that they can be issued only when the phase-out begins, while the projects themselves might start much earlier. This means that the capital available from credits might become available only after it is actually needed.
One possible solution offered is to carry out a ramped phase-out, in which lower-emitting sources gradually replace coal. This would allow some credits to be issued earlier than in a situation where all the coal assets are decommissioned at a single point in time.
However, this would still mean that most of the benefits from credits are skewed towards the end of the project.
An innovation that received special mention in the paper was advanced market commitments (AMCs), as currently seen through Frontier.
Frontier, which was started by Silicon Valley stalwarts such as Google and Meta, takes a page from vaccine development economics.
The way it works is that Frontier’s members commit to an annual budget for buying carbon credits. Frontier then assesses carbon credit suppliers on behalf of the members and cuts deals to purchase credits that meet its standards. For credits in the future, Frontier might undertake offtake contracts to purchase at an agreed price upon delivery.
That mechanism provides some capital, but more important is the certainty for producers of carbon credits, which can help to reduce the risks inherent in long-term projects.
Testing it
MAS has issued a call for partners to help test transition credits, and is looking to launch one or more pilot projects. The “data and experience” from these projects will then be used to refine the concept with the goal of rolling out large-scale implementation.