

Not just fun and games: How mobile games have become big business
Mobile gaming is booming as companies find new ways to get consumers hooked – and to open up their wallets
MOBILE games are now dominating the gaming industry, with companies finding fresh ways to milk revenue from consumers.
But while the segment has become a force to be reckoned with, industry players have noted that the ease of spending can easily lead to mounting costs for these consumers – an issue that regulators are increasingly concerned about.
In 2023, the mobile gaming market was worth around US$108 billion globally, with the segment comprising the bulk (56 per cent) of total worldwide consumer spending on video games, based on a report from mobile market data provider data.ai and IDC.
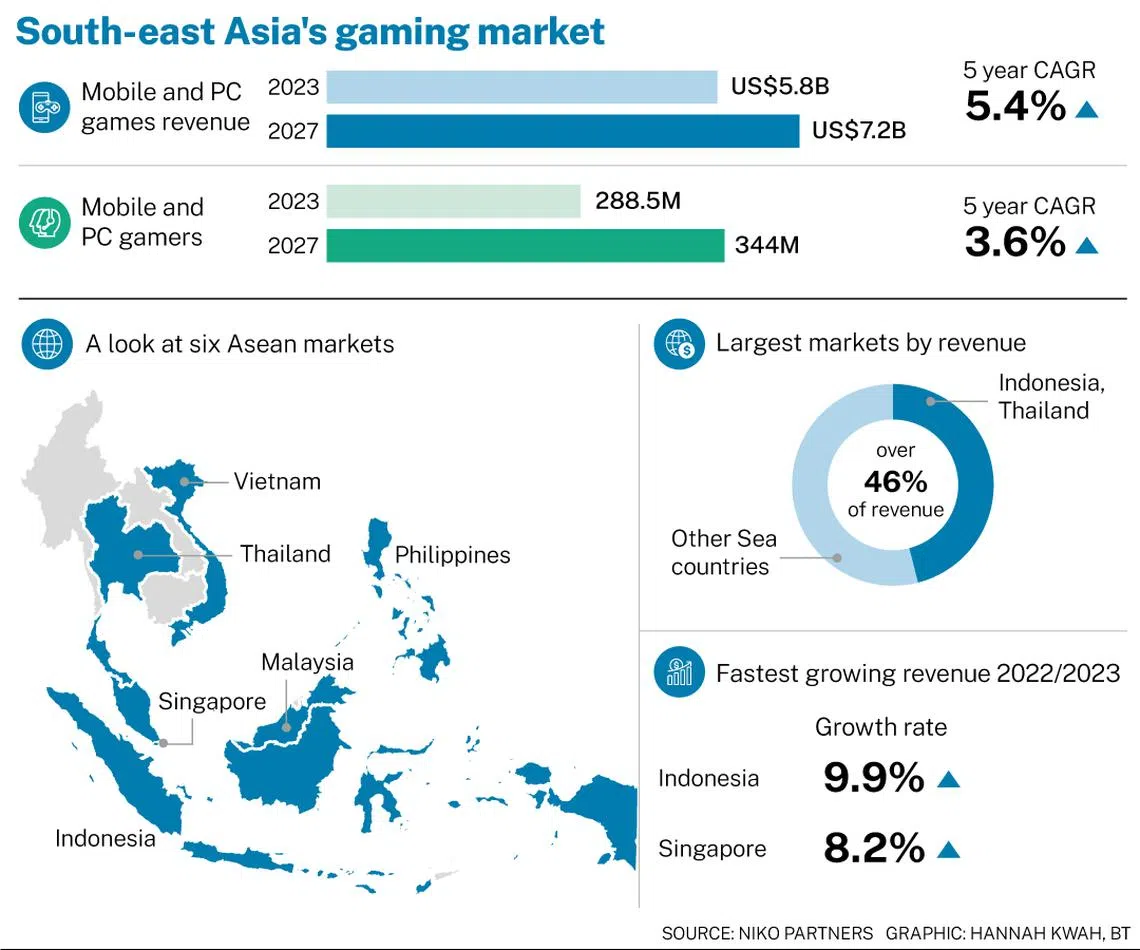
Closer to home, the mobile gaming market of six South-east Asian countries – Indonesia, Malaysia, Singapore, Thailand, the Philippines and Vietnam – was worth US$3.8 billion in 2023, with Singapore contributing 16 per cent, according to Darang Candra, Niko Partners’ director for East Asia and South-east Asia research.
Young adults aged 25 to 34 make up the largest demographic of mobile gamers, says James Walton, Deloitte Asia Pacific’s sports business group leader. This is because they tend to have the spending power to make in-game purchases and enjoy the social aspects of mobile gaming.
Pay to win
Some popular games that may sound familiar here include online battle arena title Mobile Legends: Bang Bang, developed by ByteDance subsidiary Moonton; Israel-based Moon Active’s town-building game Coin Master; as well as Genshin Impact, an action role-playing game by Chinese company Hoyoverse.
One thing these games all have in common is that they are free to play – at least on the surface.
In fact, most mobile games operate on a “freemium” – an amalgamation of free and premium – model, says Bain & Company partner Willy Chang, who leads the firm’s private equity and technology practices in South-east Asia.
This means that they are free to play, but players can spend money to purchase things such as perks to provide an edge in gameplay, or items that allow them personalise their in-game appearances.
“In-game monetisation is by far the largest monetisation model (for mobile games) at more than 95 per cent, versus upfront game purchases,” says Chang.
But since they are free to play, these games must earn revenue by enticing players to spend money on virtual items.
Nowhere is this more evident than in the “loot box” or “gacha” model adopted by many mobile games, where players can spend real or virtual currency (which can often be obtained with real money) to receive random in-game items. Since the items received are based on chance, players are enticed to spend more to get the particular item they want.
The term “gacha” is derived from the toy vending machines originating from Japan.
Gacha mechanics represent the most common gameplay model in mobile games, says Johnny Jan, chief executive and executive chairman of Singapore-listed game development company Winking Studios , which has worked on major mobile titles including Genshin Impact and Activision’s Call of Duty: Mobile.
He notes that they represent a primary source of revenue for game publishers, and that a “significant proportion” of the games Winking Studios is currently involved in incorporates such elements.
Yet not all games bank on the gacha model, which has features of a lucky draw.
In Singapore, Sea’s gaming arm Garena, through its flagship mobile game Free Fire, makes use of in-app currency purchases to sell items such as outfits and accessories for their characters, as well as a seasonal pass that gives gamers more perks and rewards as they play.
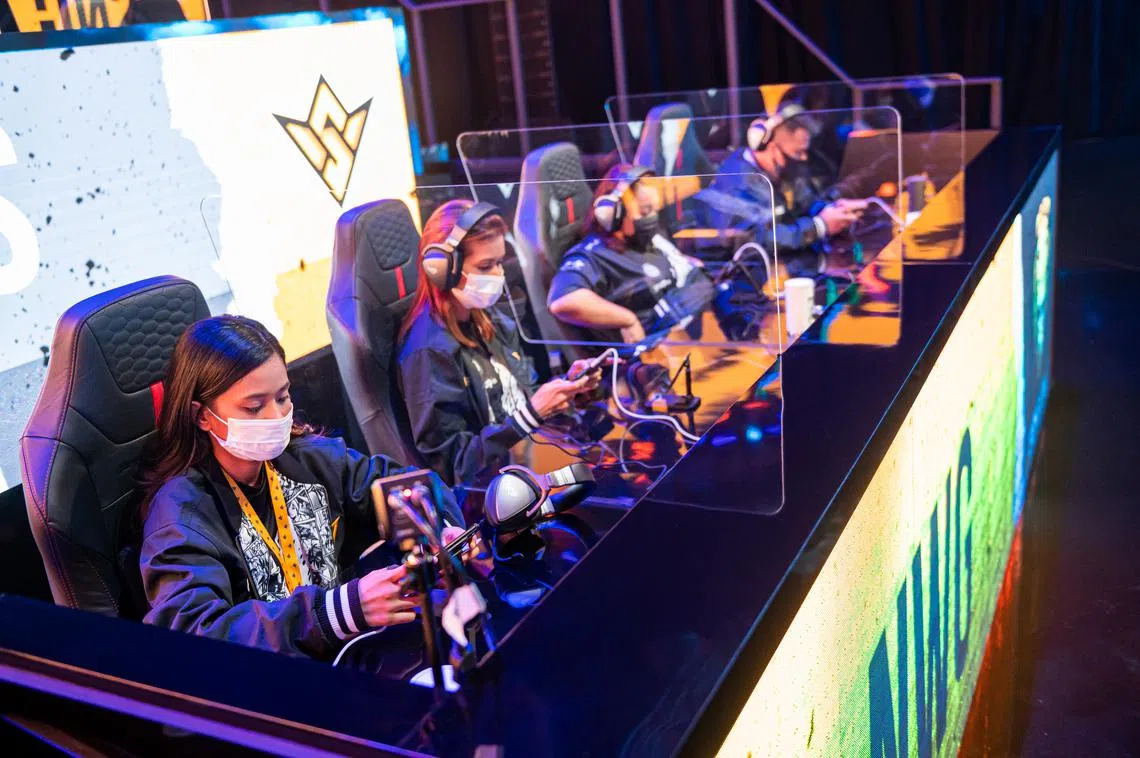
Market intelligence company Sensor Tower had reported that Free Fire was the most downloaded game globally in 2023.
The company remains bullish on its digital entertainment segment, guiding for double-digit growth in its game user base in the coming year.
Pay to play
Beyond Garena, the largest home-grown developer by far, many independent labels’ mobile offerings are on a much smaller scale, with less resources in terms of manpower.
Local games studio LandShark Games’ Paul Naylor says this could be due to larger companies making the bulk of the money in the mobile games industry, compared to independent studios that may not have the bandwidth to sustain “freemium” game models.
Such a model is usually used by games with live service operations, which require constant updating to stay relevant.
In this vein, smaller studios in Singapore have started pivoting to mobile games that require players to purchase upfront.
This is similar to the model employed by most computer and console games, but comes with a much cheaper price tag.
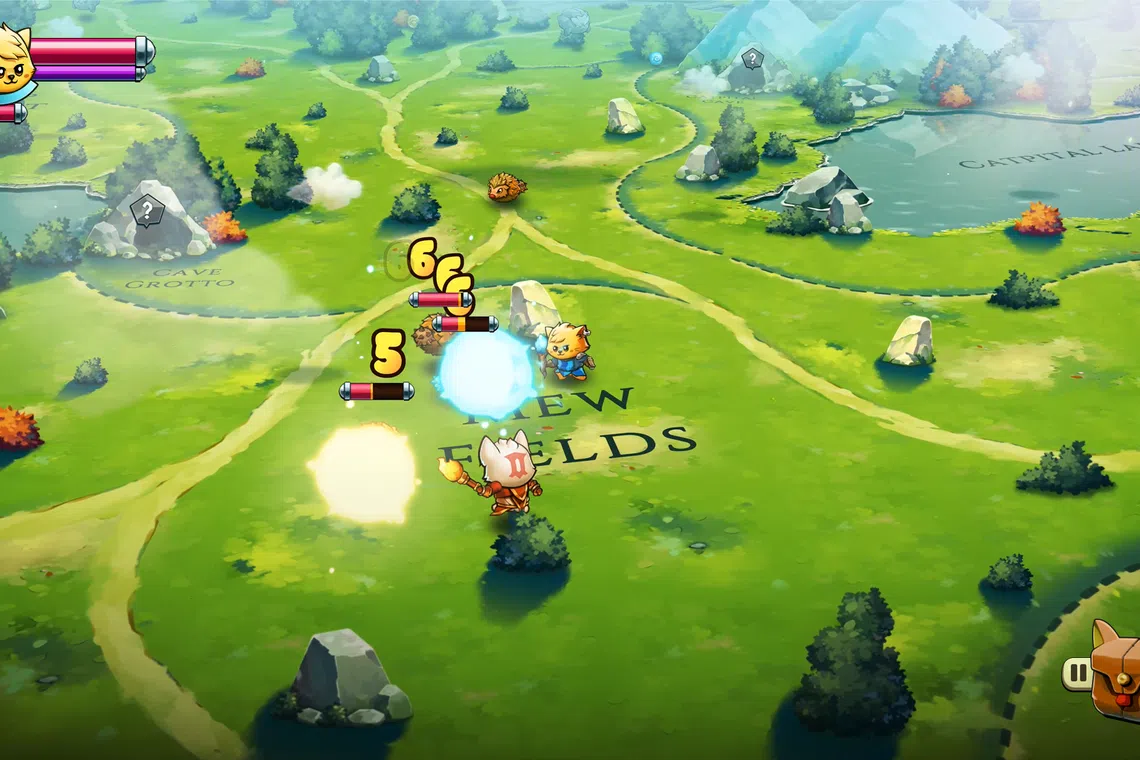
For example, open-world exploration game Cat Quest and its sequel, created by The Gentlebros, are priced from US$12.99 to US$14.99 on computers and consoles, but around US$5.99 on mobile.
Desmond Wong, chief executive of The Gentlebros, says the perceived value of games on the app store is “slightly different” from games on computers and consoles, hence the marked difference in price.
This comes as people are less inclined to pay for mobile games as many of them are free. Furthermore, apps in general tend to be inexpensive.
“It was the difference between selling the game or not selling at all… we have to price the game to fit the (segment) we are selling to,” he says.
Shawn Toh, chief executive and design director of studio BattleBrew Productions, says that having a live service game is tough, and may be an aspect many smaller studios cannot afford to support.
“For mobile long-term free-to-play (games), you may have a long, steady stream of revenue coming in, but so do your expenses (pile up),” he notes.
Mobile motivation
Mobile gamers are often regarded as casual gamers, especially compared with gamers who play on consoles or personal computers.
But LandShark Games’ Paul Naylor and Kim Tay Naylor note that casual mobile gamers may be the ones spending the most time and money on their games.
This is as micro-transactions in mobile games can add up over the year, and it is possible for casual users to spend significant amounts of money, they add.
Deloitte’s Walton says: “There is an inherent allure of collectibles in these games, and the ease of making in-app purchases helps as well.”
Mobile game players agree. Ashikin Ali, who plays Genshin Impact and augmented reality collection game Pikmin Bloom, says she is driven to spend by the aesthetics of the game characters.
“If the game is offering a special costume or character with a design that is visually appealing to my preferences, I am likely to spend money, especially if it is only available for a limited time,” says the 27-year-old who works in heritage management.
“The idea of owning these items, even virtually, is satisfying and, in a way, contributes to my self-expression.”
She spends around S$10 to S$150 per month, depending on whether the games she plays have collectibles or characters that appeal to her, but will not spend if there is no appealing collectible.
Vivian Chen, artificial intelligence and society associate professor at Erasmus University Rotterdam in the Netherlands, says: “If you’re hooked to a certain good mechanism (in a game), you’re likely to stay on.”
Taking chance-based games as an example, Dr Chen says the rewards through this system are an attractive mechanism for gamers because of the high surprise factor once they receive the coveted item.
Dr Chen, whose research includes work on social interactions with games and its communities, adds that the rewards achieved through the chance-based mechanism is also a way of showing off a status in the game.
“There’s this whole idea of ‘I’m somebody because of this item’, and I think that association is very strong in general among gamers,” says the professor.
Winking Studios’ Jan says this is especially so for socially-oriented games. “Some players aspire to be the most outstanding characters within the community,” he says.
“Although they may constitute just 1 per cent of the player community, they typically possess significant spending power. The amounts they spend… are sufficient to fund game publishers’ continuous development of high-quality game content to satisfy the remaining 99 per cent of players.”
Not child’s play
With the increased consumer spending for games, certain countries have taken a stricter stance towards discouraging game time and spending or are expressing concerns about the consequences.
China, for example, implemented rules that heavily curbed online play time for children under 18 years old to three hours a week.
Game developers were also barred from providing services to minors in any form outside of these hours, and must ensure they have real-name verification in place.
Dr Chen says that younger gamers may not fully understand the monetisation methods in the games and therefore do not know the financial implications of spending on these games.
There is also the common association that people draw between chance-based game models and gambling, even if the loot box mechanism may not be quite the same thing.
“Young gamers probably would need a bit more literacy and explanation… which could prevent any sort of higher negative consequences in life,” she says.
Deloitte’s Walton says that there is no structured regulation at the moment specifically targeting chance-based games in South-east Asia.
Should they be introduced, they should encourage responsible gaming practices while ensuring the long-term viability of the region’s gaming ecosystem, he adds.
“It’s a fine balance between protecting consumers and promoting a vibrant and innovative gaming industry.”
New spending channels
As the popularity of mobile games booms, more payment companies are hoping to get a slice of the pie.
Bain’s Chang says credit cards are usually the main avenue of spending: “Broadly speaking, purchases can be split into in-app versus out of app. In-app goes through the Apple App store or Google Play store, so generally this has been whatever payment method is tied to the gamer’s iOS or Android profile.”
Apple and Google take around a 30 per cent cut of the payment to applications, regardless if they are for games or other apps. This generally means that in-app purchases become more expensive.
The hefty cut – and the fact that games have to be downloaded through these platforms – has led to conflict between government bodies and the tech giants.
Most notably, South Korea passed an amendment to its Telecommunications Business Act in 2023, which prevents large platform holders from forcing developers to use their first-party in-app payment systems.
Developers have also chafed at the huge cuts. Epic Games, maker of the popular battle royale video game Fortnite, sued Google in 2020, claiming that the Google Play store constituted an unlawful monopoly and aimed to bring its own third-party store to Android phones.
A United States jury ruled in Epic’s favour, with Google aiming to appeal.
Despite the apparent monopoly of the app stores, some markets that have a lower card penetration will go through out-of-app channels to pick up their in-game purchases, says Chang.
These are largely where gamers are more price-sensitive, and will take the effort to go to publishers’ websites or to third-party web stores and top up credits there, using e-wallets, cards, bank transfers and carrier billing.
Such third-party stores include Codashop, operated by Singapore-headquartered Coda; as well as Indonesia-based Dunia Games and UniPin.
A white paper by Coda and Niko Partners had estimated that 21 per cent of all mobile games revenue in South-east Asia came through purchases outside the app. In some markets, the number is even higher.
Coda’s chief technology officer Michael Feldkamp told BT that game developers and publishers will opt to work with third-party payment providers to offer a better price for users, as their fees are lower than the cuts taken by Apple and Google.
While he declined to give exact figures for the fees charged, he says the amount is competitive and publishers see it as “good value”.
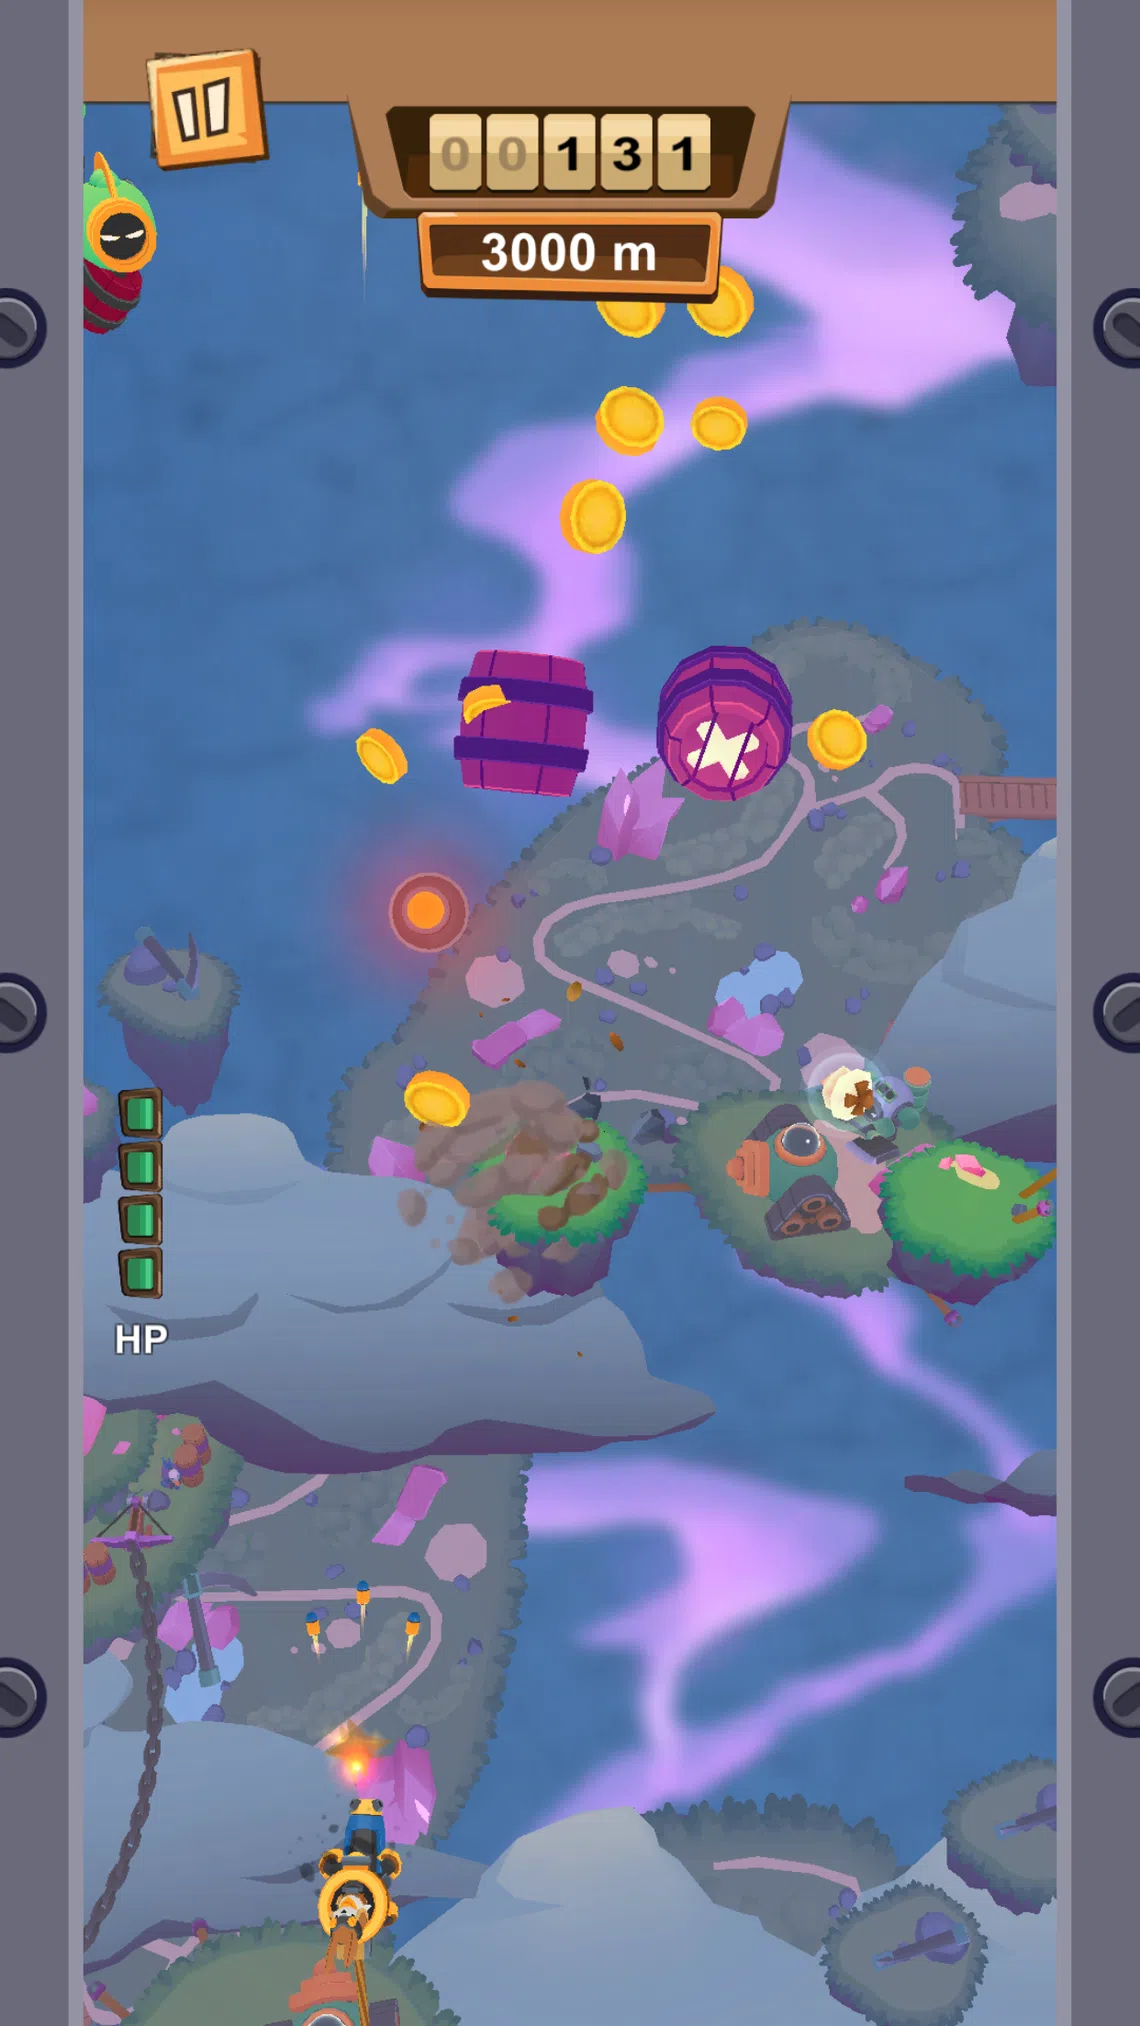
Ultimately, industry experts note that South-east Asia has looser regulations for mobile game monetisation compared with peers in North Asia. This is likely to bolster further growth in the mobile game industry in this region.
Even as the mobile games industry carries on its upward trajectory, it remains to be seen how companies will be affected as pushback from larger bodies to protect groups of more vulnerable individuals continues to play out.
With mobile gaming bringing in big money, regulators will need to be mindful about striking a balance between protecting consumers and cultivating the growth of a dynamic and innovative growth engine of the economy.






