An overhaul of Malaysia’s pension system is long overdue
Tan Ai Leng
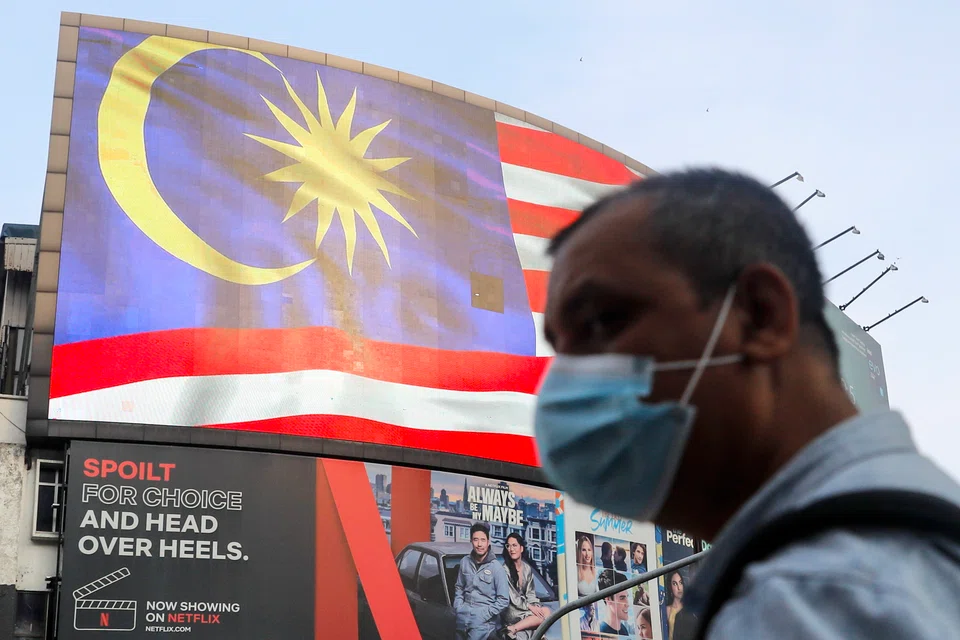
BARELY a week has passed since forming his new Cabinet, and Malaysia’s new Prime Minister Anwar Ibrahim has already displayed a steely determination to fix the country’s economy with a series of initiatives and announcements. There is one pressing issue, however, that has yet to be addressed by the new administration, and that is the reform of the pension system.
The 75-year-old Anwar, who also named himself finance minister, has wasted no time to make a number of major announcements since taking charge, including a review of the national 5G network project and the RM7 billion (S$2.1 billion) flood mitigation project awards, all cabinet ministers taking a 20 per cent pay cut, as well as a review of the current blanket subsidy mechanism.
All these are in line with the election manifesto issued by Pakatan Harapan, the coalition that Anwar leads, to improve Malaysia’s economy, fight corruption and prevent leakages.
One area that should be at the top of the new administration’s to-do list is to address Malaysia’s pension crisis, which could potentially lead to social problems if neglected for too long.
Between 2020 and 2022, the government allowed Employees Provident Fund (EPF) members to withdraw money from their retirement savings under four different programmes. This has resulted at least RM145 billion being taken out so far.
As a result, more than half of the EPF’s 12.7 million members have less than RM10,000 in their retirement savings, while about a quarter have below RM1,000.
If the above figures are not alarming enough for urgent action to be taken, perhaps the following numbers will.
Based on EPF’s estimates, 96 per cent of its members do not have enough savings for a living income pension, while 73 per cent do not have enough even for a poverty-level pension.
Currently, employees’ mandatory contribution to EPF is 11 per cent of their monthly salary, while employers are required to contribute 12 per cent (or 13 per cent for monthly salaries of below RM5,000).
Malaysia is not the only country that allows their citizens to withdraw their pension savings, with Australia and Chile also having similar initiatives in place for their people.
In contrast, Singapore’s Central Provident Fund (CPF) has seen a record number of people who topped up their retirement savings account. In 2021, 294,000 members made a total 668,000 top-ups, amounting to S$4.8 billion.
Of course, there is no single solution to address this massive issue in Malaysia. For one, it requires the government to make some tough decisions, such as making changes to the retirement age, revising EPF contribution rates upwards, or even setting up a new fund to provide additional social security support for the lower income groups.
It is understandable that many politicians would prefer to avoid talking about this issue, as the solutions may well be unpopular to the electorate. This could also explain why the other political parties did not highlight pension reforms in their manifestos ahead of last month’s general election.
According to the World Bank, one in five people in Malaysia will be 65 and above by 2056, which effectively makes the country an ageing society. If seniors do not have sufficient funds for their retirement, they have little option but to rely on either the public healthcare system or their children for support. Either way, the country will have to pay a heavy price.
I once spoke to a fund manager on this topic. His interpretation was that while most politicians understand the problems facing Malaysia’s pension system, they have the mindset that this is a long-term challenge that can be dealt with by a future government.
However, the reality is that time is not something that Malaysia has much of. This is where Anwar and his Cabinet will be put to the test – to grow the economy in the current challenging environment, ensure all Malaysians can benefit from the government’s policies, and at the same time, having a viable system in place that allows everyone to retire as comfortably as possible.