

Paragon’s value lies in the opportunity for CICT to transform an ageing gem
The trust has the means and expertise to add value to the trophy Orchard Road asset
[SINGAPORE] Astute real estate investment trust (Reit) managers rejig Reit portfolios to boost returns to unitholders.
The manager of market leader CapitaLand Integrated Commercial Trust (CICT) is doing just that with the trust’s proposed purchase of a 100 per cent interest in Paragon and sale of all of Asia Square Tower 2.
Grade A office space and ancillary retail space at Asia Square Tower 2 in the Marina Bay precinct is being sold at an agreed property value of S$2.476 billion – 9.9 per cent above the independent valuation of S$2.252 billion as at end-2025.
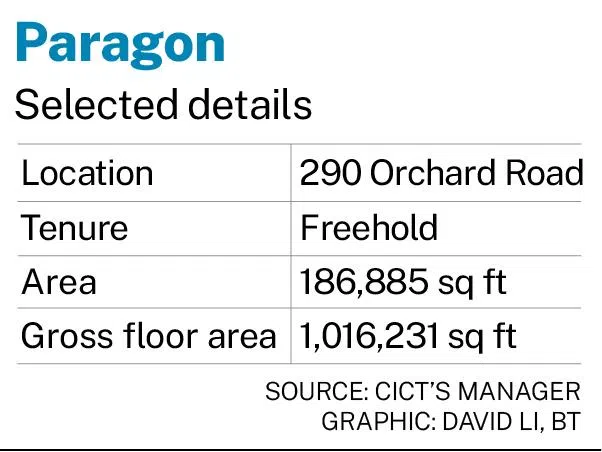
Paragon, located along Orchard Road, is being purchased at an agreed property value of S$3.9 billion. The property has a total net lettable area of around 714,900 square feet (sq ft), comprising about 491,800 sq ft of retail space and 223,100 sq ft of medical suites and offices.
CICT’s net entry yield for Paragon is 3.9 per cent per annum while its exit yield for Asia Square Tower 2 is 3 per cent per annum. And the manager expects CICT to enjoy an uplift in distribution per unit (DPU).
Still, over the long term, what is truly exciting is that Paragon is high-quality real estate that has potential for transformation.
King of Orchard Road
One, snaring Paragon will give CICT a commanding presence in Singapore’s premier Orchard Road shopping belt.
The trust’s portfolio includes Orchard Road area assets – Ion Orchard, Plaza Singapura and The Atrium@Orchard.
The street’s position as a leading retail destination is being challenged at home and abroad.
At home, The Shoppes at Marina Bay Sands is capturing luxury retail shoppers, while numerous large suburban and city-fringe malls satisfy a wide range of the needs of residents.
Abroad, mega malls have sprouted up across many major Asian cities.
Nonetheless, do not discount Orchard Road’s prospects as a retail and lifestyle destination.
Orchard Road has plenty of retail space – scale will help the street stand out at home and be competitive internationally.
Its retail and lifestyle spaces can benefit greatly from Singapore drawing wealthy migrants and high-spending international visitors.
As a beacon of stability in a chaotic world, Singapore is well-positioned to grow as a wealth management and business hub, thereby drawing more wealthy individuals and top talent to become permanent residents and citizens.
As a safe and efficient destination, the Republic, which is investing heavily to improve its tourism offering, can attract more international visitors.
In short, major trends support Orchard Road’s development as a retail and lifestyle destination.
As the street’s leading retail landlord, CICT will enjoy a significant competitive edge.
It can be the partner of choice for major retailers seeking space in the Orchard Road area. Also, the trust can position its various Orchard Road assets to complement one another and reap synergies from its malls in the area, sharing knowledge with one another and collaborating on marketing efforts, among others.
Transformation potential
Two, Paragon offers a tremendous value-add opportunity for CICT.
Whereas CICT owns 50 per cent of Ion Orchard, the trust is looking to buy 100 per cent of Paragon.
Paragon was opened in 1986 and its latest significant asset enhancement initiative was in 2009.
This ageing asset has size and occupies a great location.
No party is probably better able to do a major asset enhancement or redevelopment of Paragon than CICT.
The trust has scale – its enlarged portfolio value after buying Paragon and selling Asia Square Tower 2 will be around S$28.7 billion.
It is a leading and experienced mall owner in Singapore. By having full ownership of Paragon, the trust is well-placed to bring the asset to its full potential.
Given its scale, CICT can fund major upgrading works at Paragon, possibly by working with partners, and cope with any adverse impact to DPU while carrying out upgrading works.
Importantly, the trust can leverage CapitaLand Group’s property development expertise, which includes integrated developments and malls.
CICT’s manager is owned by CapitaLand Group’s investment management arm, CapitaLand Investment .
The Urban Redevelopment Authority’s Strategic Development Incentive Scheme encourages the rejuvenation of older buildings in strategic areas into new, bold and innovative developments that will positively transform the surrounding urban environment.
Properties that qualify for the scheme may enjoy additional gross floor area, more flexibility in land use and greater development intensity among others.
Perhaps, redeveloping Paragon as a single site can be sufficiently transformative to qualify for incentives under the scheme.
Freehold status
Three, while many Singapore properties held by Reits are not freehold, CICT is buying the freehold interest in Paragon.
The trust could potentially have paid less and made an even more DPU-accretive deal by acquiring a leasehold interest in Paragon.
Nevertheless, there is value in owning a prized chunky freehold property in Orchard Road.
An owner of a freehold property is under less time pressure when working on major asset upgrading or redevelopment plans.
Crucially, major freehold Orchard Road commercial properties command a scarcity premium.
CapitaLand Mall Trust, which was renamed CICT in November 2020, completed the acquisition of freehold Plaza Singapura at a purchase price of S$710 million in August 2004.
As at end-2025, Plaza Singapura’s valuation was S$1.443 billion – more than double the purchase price and representing steady growth at a compound annual growth rate of close to 3.5 per cent.
As major freehold Orchard Road commercial properties are scarce, such assets may draw irresistible bullish offers in future should investors place a growing safe-haven premium to Singapore assets in a tumultuous world.
Paragon’s medical space is an added attraction. Supply of medical space is relatively tight while demand for such space is driven by an ageing population and rising medical tourism. Paragon is located close to the well-established Mount Elizabeth Hospital.
CICT is betting big on commercial property in the Orchard Road belt. Might it try to get a stake in the possible redevelopment of Hotel Properties Ltd’s Orchard Road area trio of Forum The Shopping Mall, voco Orchard Singapore and HPL House should such an opportunity arise?
While it is paying a rich price to buy Paragon, CICT is getting a sizeable asset which has full occupancy at a decent yield. It will also secure an asset with enormous scope for transformation.
Ultimately, adding Paragon to its portfolio while exiting Asia Square Tower 2 enhances CICT’s yield and growth trajectory, thereby strengthening its investment case.
The writer owns units in CICT






