Recession risks rise for global economy
Recent monetary policy decisions by key central banks signal a rapidly changing outlook
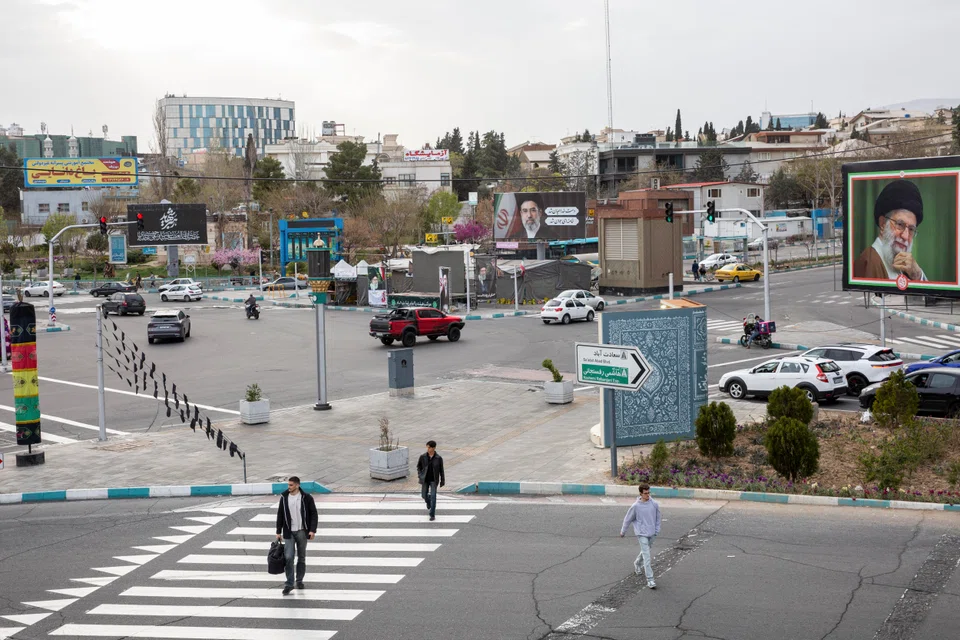
ON THE eve of the US and Israeli military campaign against Iran just under four weeks ago, the outlook for the global economy was relatively benign. Today, recession risks are rising in what the International Energy Agency (IEA) calls the greatest ever shock to the vast global energy sector.
The rapidly deteriorating outlook is even being called an “armageddon scenario” for the energy landscape. Goldman Sachs last week warned that “the persistence of several prior large supply shocks underscores the risk that oil prices may stay above US$100 for longer in risk scenarios with lengthier disruptions and large persistent supply losses”.
While this is alarming enough for the global economy, Iran has determined that it faces an existential threat and seems to have decided that its best course of action is to inflict as much pain as possible on global financial markets. It has vowed to try to cause the price of oil to soar to US$200 a barrel if the war with the US and Israel continues.
Previous oil spikes
Persistence of oil at US$100 a barrel would be challenging enough for the world economy, let alone anything so much higher. The factual basis for this is shown by a look back at previous oil spikes which fuelled inflation and undermined growth.
The typical increase in the consumer price index (CPI) in the US economy, which remains key to global growth, has been between 1.5 and 2.1 per cent during oil price jumps over the last two decades.
For instance, between March 2007 and June 2008, during the economic boom preceding the subprime lending crash, oil prices rose from US$66 to US$140 a barrel (West Texas Intermediate). This helped fuel a US CPI jump from 2.8 per cent to 4.9 per cent during the approximately 15-month period.
This oil price spike brought about the start of the US recession in summer 2008, a couple of months before the downfall of Lehman Brothers and the great financial crash of 2008-2009.
During the robust economic boom in China from May 2010 to April 2011, oil prices rose from US$74 to US$113 a barrel with a US CPI jump from 2 per cent to 3.5 per cent during the approximately 11-month period.
More recently, from November 2021 to May 2022, a period that was immediately before and after Russia’s invasion of Ukraine, the rise in oil prices was from US$66 to US$114 a barrel. This helped fuel an increase in US CPI from 6.9 per cent to 8.5 per cent during the approximately seven-month period.
Now oil prices have risen from US$62 at the start of February to roughly US$100, about a 60 per cent jump since the start of hostilities. This has increased concerns about stagflation: a combination of weak economic activity combined with accelerating inflation.
Recession potential tipping points
The tipping point for a potential global recession, of course, depends on how much damage is done and how long the war lasts, including how long the Strait of Hormuz remains largely blocked.
The uncertainty concerning potential damage is highlighted by Israeli strikes on Iran’s South Pars field, which gave rise to Iranian retaliation against Qatar’s Ras Laffan liquefied natural gas (LNG) facility, the world’s largest such asset. This resulted in an estimated US$26 billion worth of damage and may take up to five years to fix, reducing the country’s LNG export capacity by 17 per cent.
A major risk scenario centres around reports that US President Donald Trump is considering ordering US troops to seize or blockade Iran’s Kharg island, the launch point of 90 per cent of the nation’s oil exports.
The US administration has already deployed around 5,000 marines and sailors, as well as USS Tripoli – an amphibious assault ship – to the region, signalling a potential ground game in coming weeks.
Israeli Prime Minister Benjamin Netanyahu also hinted at the prospect of using ground troops. He said last week, “You can do a lot of things from the air, and we are doing that, but there has to be a ground component as well. There are many possibilities for this ground component, and I take the liberty of not sharing with you all those possibilities.”
Action against Kharg would likely trigger a fuller retaliation against energy infrastructure across the Gulf states, should the Iranian regime still have the military power to do this.
While many uncertainties remain, a number of forecasters are already sounding the alarm bells. Oxford Economics warns, for instance, that if global oil prices average around US$140 per barrel for some two months it would be enough to push parts of the global economy into a mild recession.
However, a less severe alternative where oil prices average around US$100 per barrel for two months would only “shave a few tenths of a percentage point off global gross domestic product growth” via higher inflation.
Worryingly, current rises in oil prices have come despite recent announcements by IEA of a historically large release of 400 million barrels of oil from its emergency reserves, coordinated by 32 major economies.
The unusualness of such a release is shown by the fact that IEA nations have released emergency oil stocks on only five previous occasions. These were the 1990-91 Gulf War, Hurricane Katrina in 2005, the Libyan war in 2011, and twice following Russia’s invasion of Ukraine.
One signal of how the growing economic challenges from the Middle East are rapidly changing the global economic outlook is shown by recent monetary policy decisions. In the last week, key central banks including the US Federal Reserve, European Central Bank (ECB) and the Bank of England, held rates steady despite significant prior expectations of cuts.
US Fed governor Christopher Waller, who voted for a rate cut at the previous Federal Open Market Committee meeting, opted for a hold last week, saying that “this is looking like it’s going to be a protracted conflict, and oil prices are going to stay high for a longer time. So that suggested inflation was more of a concern than I was putting it (before)”.
Moreover, a growing number of market participants are so concerned about inflation risks that they no longer see the US Fed and key European central banks cutting rates this year. For instance, traders are currently pricing in two ECB rate hikes in 2026, and a significant chance of a third. Fed chairman Jerome Powell has begun talking about the possibility of rate increases.
Politically, the economic fallout from the crisis is likely to make upcoming elections even more challenging for many incumbent parties. This includes the US where Republicans face a growing possibility of losing their majority in the House of Representatives in November, and possibly the Senate as well.
Trump asserts that the economic impact of the war is “a very small price to pay” for trying to oust the Iranian regime. However, that view is not shared by a growing number of countries hit by the crisis, and may ultimately be rejected by the US electorate come November too.
Robert Wescott served during the Bill Clinton administration as special assistant to the president for economic policy and as chief economist in his Council of Economic Advisers. Andrew Hammond is a former UK special adviser in the government of Tony Blair.