

Ring the bell: Could Singapore be a victim of its own S-Reit success?
What’s in the pipeline of new Reit listings is a welcome sign. But SGX’s deeper challenge is far harder to solve
CALL it a Singapore-listed real estate investment trust (S-Reit) renaissance, if you like.
But it is starting to feel a bit like Groundhog Day in the local equity market – another quarter, another Reit initial public offering (IPO) either launching, testing the waters, or just swirling in the rumour mill.
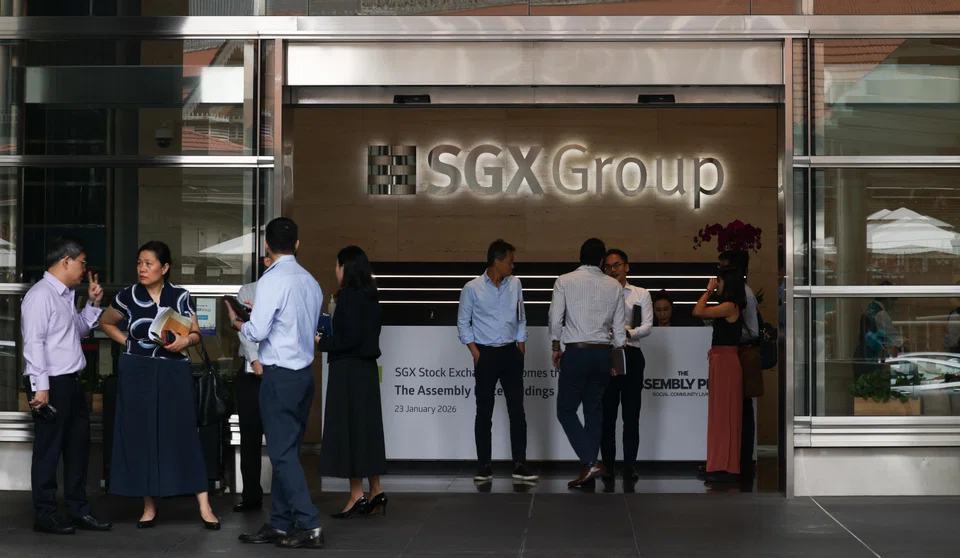
Just two weeks ago, the Singapore Exchange (SGX) welcomed logistics, industrial and business space player UI Boustead Reit to the mainboard. It raised about $973.6 million, in what was Singapore’s biggest IPO so far this year.
And if market chatter is to be believed, the pipeline is bulging with sponsors eager to offload their assets onto the public markets.
These include Malaysia-based IOI Properties Group, which is said to be advancing its plans to list two Reits – one on Bursa Malaysia and the other in Singapore.
The Singapore-bound Reit, which may hold marquee properties such as IOI Central Boulevard Towers and the South Beach mixed-use development in a portfolio valued at up to S$8 billion, is rumoured to be targeted for 2027.
Meanwhile, Thailand-listed hospitality company Minor International is reported to be weighing a US$1 billion S-Reit listing as soon as in the second half of this year.
Already, as at end-2025, Singapore’s 41 Reits and property trusts boasted a combined market capitalisation of S$104 billion, representing close to 10 per cent of the stock market.
Let me be clear: A robust, vibrant S-Reit market is a good thing.
Singapore has spent two decades painstakingly building a regulatory and tax environment that has made it the Asian hub for Reits, outside of Japan. It provides retail and institutional investors alike with a reliable instrument for yield in a world that is often starved of it.
But let us also be honest. A stock exchange cannot survive on property yield alone.
When a market becomes dominated by a single asset class – especially a purely defensive, yield-generating one – it risks morphing into a high-interest savings account rather than functioning as a dynamic engine of capital formation for the economy of tomorrow.
A strong S-Reit market is a fantastic foundation. But you cannot live in the foundation; eventually, you have to build the house. And right now, the upper floors of the local bourse are looking decidedly vacant.
Needed: New listings that aren’t Reits
For SGX to truly thrive, what we need is not another portfolio of suburban malls, logistics warehouses or data centres packaged into a trust.
What we need are quality, sizeable, operating companies choosing Singapore as their venue to raise capital and fund aggressive growth.
As a veteran industry source recently highlighted to me: The math for a truly thriving exchange looks very different from our current reality. For every new S-Reit that rings the opening bell, SGX needs at least three quality, sizeable corporate listings.
This three-to-one ratio may not be born of academic modelling, but it is not unreasonable. Above all, it is the rough intuition of someone who has watched this market long enough to understand the structural imbalance that has taken hold.
There have been no primary mainboard listings of a non-Reit so far this year. The last, on Dec 3, was the listing of Ultragreen.AI , a global innovator in fluorescence-guided surgery and AI-driven surgical solutions.
The exchange has become, in the eyes of some international investors, a Reit market with equities attached – rather than the other way around.
That perception matters, because perception shapes behaviour.
Index weights, analyst coverage, trading desk allocations – all these follow where the depth and dynamism are seen to reside. And right now, too much of Singapore’s new listings story is being written in distribution yields and net asset values, rather than in revenue growth and addressable markets.
Think about what a major corporate listing brings to the table. It brings a growth story. It brings research and development, economic dynamism and intellectual property. It gives asset managers a reason to allocate capital towards capital appreciation, not just dividend harvesting.
When a market has a healthy pipeline of technology, healthcare, consumer and manufacturing IPOs, it creates a virtuous cycle. It attracts a wider pool of analysts, varied institutional funds, and crucially, it fosters higher trading velocity.
After all, Reits are generally buy-and-hold investments, but growth equities are what drive daily liquidity.
Achieving this three-to-one ratio is the true, existential challenge for SGX management. It is a steep hill to climb.
The hurdles are well-documented. The risk is a vicious cycle where a perceived lack of liquidity leads to lower valuations for corporate issuers, relative to what they might fetch in New York or even in regional bourses.
And because valuations are lower, the best and brightest homegrown companies bypass the local bourse and take their IPOs to the Nasdaq; alternatively, they stay in the private markets, fuelled by an abundance of venture capital and private equity dry powder.
This leaves SGX with the issuers who fit the profile of the investors who are already here: yield-hungry dividend seekers. So we get more Reits.
If anything, the continued momentum in S-Reits risks masking the underlying issue.
Activity can be mistaken for progress, and listings can be mistaken for depth.
A thriving S-Reit pipeline, however welcome, does not by itself address the more fundamental question of the kind of exchange Singapore is building for the next decade.
What SGX needs – urgently, and in quantity – is quality equity listings.
Companies with genuine earnings power, management teams with track records, and market capitalisations large enough to attract the global institutional flows that make a bourse truly liquid and truly relevant.
That means the kind of listing that forces a global fund manager to look at Singapore not because it offers an interesting yield play, but because the company is simply too good to ignore.
Singapore’s pitch – political stability, rule of law, a genuinely international financial centre, a gateway to South-east Asia – is a strong one. It is not, however, a pitch that sells itself.
To be sure, the work being done to attract listings is real: the Equity Development Programme, the ongoing engagement with family offices and founders across the region, and the push into new sectors.
Those efforts deserve recognition. But, perhaps, they also need to move faster – and aim higher.
Yes, we should absolutely celebrate the success of the S-Reit sector; it is a genuine feather in Singapore’s cap.
However, we must stop using it as a fig leaf to cover up the gaps in the rest of the equity market.
While the S-Reit market is, in many ways, SGX’s most polished product, it would be ironic if it also becomes its ceiling.






