

‘Search funds’ to buy SMEs spring up in the Asia-Pacific, but will they succeed?
Australia and Japan lead in successful acquisitions, while search funds are emerging elsewhere
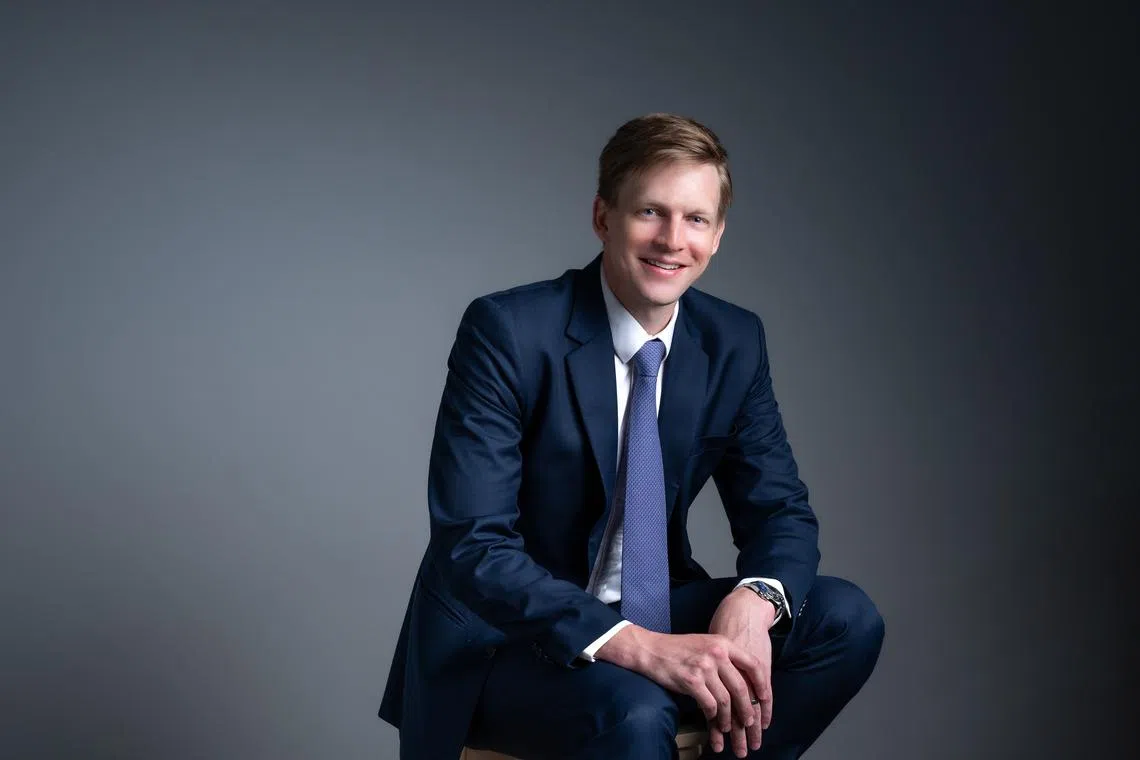
[SINGAPORE] After a 15-year career ranging from engineering to investment banking, Pete Seligman left the corporate world – and went looking for a company to buy. In 2013, he and a friend founded buyout vehicle Alpin Group to acquire, operate and grow small businesses in Australia.
“When we said we were going to buy a small business in Sydney, everyone thought we were a bit strange,” he tells The Business Times. “It was a very unusual thing to do at that time.”
Over the next four years, the duo acquired five businesses in succession, eventually exiting two and selling partial stakes in the rest by 2020.
It was only in 2019 that Seligman learnt he was performing entrepreneurship through acquisition (ETA), a concept from US business schools: acquiring and running a small and medium-sized enterprise (SME), instead of founding one.
A common ETA approach is the “search fund”: an investment vehicle in which a ‘‘searcher” raises capital to find, acquire and run an SME. Investors typically fund up to two years of searching, with more capital raised once a target is found.
Today, Seligman is Australia’s leading search fund investor, backing and nurturing new ETA aspirants.
While the ETA model is more common in North America, Australia is widely viewed as having the most developed search fund ecosystem in the Asia-Pacific, based on “active searches” and successful acquisitions.
Australia-based search funds have completed 11 acquisitions, with nine under way, according to business school Insead’s ETA and Search Funds Hub. Japan follows with four successful acquisitions and three ongoing searches.
Elsewhere in the region, the first search funds were launched in mainland China, Taiwan, Singapore and Malaysia in 2024, and in Thailand in 2025. But whether they bear fruit remains to be seen.
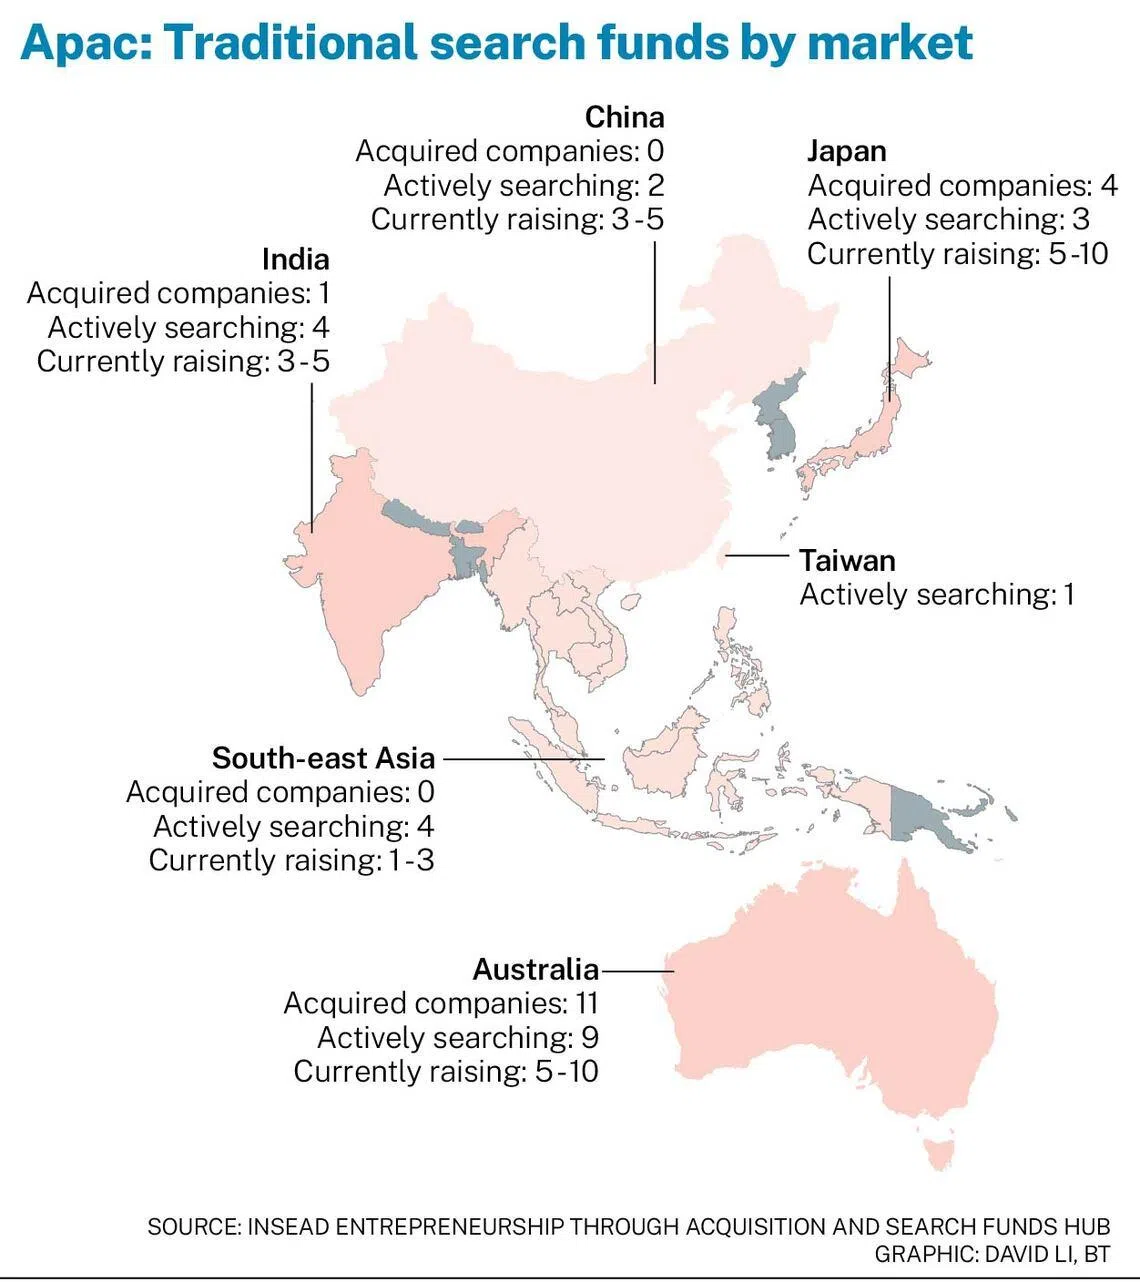
Growing search fund activity in Apac
Nearly 700 search funds have been launched in the US and Canada since 1984, when the concept was introduced by the Stanford Graduate School of Business.
An alternative is the self-funded search, which Seligman pursued in 2013. These searchers rely on personal savings and raise capital only after identifying a target.
Today, various ETA models are taught in business schools in North America and Europe, and are popular among Master of Business Administration (MBA) graduates as an alternative to entrepreneurship.
“If you want to become a business owner, you’ve got two options – either start one, or buy one,” says Seligman.
Apac is perceived as the next frontier for search fund growth, with observers citing its favourable demographics: baby-boomer business owners approaching retirement without successors.
The talent pipeline has also strengthened, says Ivana Naumovska, associate professor of entrepreneurship and family enterprise at Insead. More entrepreneurs – often returning home with MBAs from abroad – now view search funds and ETA as a “credible career path”.
Over the past two years, business schools Insead and IESE hosted inaugural Apac-focused ETA conferences in Singapore, Hong Kong and Shanghai.
In response, institutional search fund investors are turning their attention to the region. Beyond funding, these investors provide mentorship and may serve on the board of the acquired company.
Since 2023, Vancouver-based vehicle Ambit Partners has steadily increased its investments in search funds across the region. Its biggest portfolio markets are Europe and Latin America.
Ambit Partners has backed 21 search funds in Apac – including in Australia, China, India, Malaysia, Singapore, Taiwan, Thailand and Vietnam – with US$1 million in search capital and just under US$10 million for acquisitions.
Says co-founder Niel Wyma: “The region’s activity is still small relative to other markets, but growing quickly.”
Lighthaven, set up in December 2024 as the first Asia-focused institutional search fund investor, has backed 11 search funds across Apac.
Singapore-based founder Tycen Bundgaard held the fund’s second close last month. He intends to raise up to US$50 million by end-2027 to support more searchers in the region.
Last October, global investment fund Inseta was set up. It aims to be “one of the leading ETA and search fund investors” in Apac, says partner Lukas Krauss.
Inseta has raised over 75 per cent of its 50 million euro (S$74.9 million) target. A second close, planned for the first quarter of 2026, will prioritise securing investments from Apac-based limited partners.
Australia: Sustaining momentum
In Apac, Australia and Japan are considered the most “search fund-ready” markets as they have what is needed for a thriving ecosystem, says Prof Naumovska: a pool of SMEs with succession needs, entrepreneurial talent, availability of equity and debt financing, and an “institutionally credible” environment.
These conditions were not always there. In 2019, when the first search fund was launched in Australia, Seligman recalls “only a handful” of domestic investors – with most capital coming from offshore – and little sense of a community around ETA.
Since exiting some of the companies he bought, he has worked to build the country’s search fund ecosystem.
This includes launching Australia’s inaugural ETA forum in 2022, now an annual event; hosting podcasts; and speaking to “five to 10” people weekly to spread awareness, from searchers to investors to advisers. He himself has invested in 18 search funds, most of them in Australia.
“Debt and equity domestically have grown nicely in the last few years, which has been good support for Australia’s growth,” he says.
Australian banks have become more receptive to cash flow loans – which do not require tangible assets to be pledged as collateral – for ETA-type transactions, while private credit funds have also stepped in.
“Each year, I think about the different actors required to make the market work, identify where the gaps are, and then encourage those players to enter the market,” he adds.
His next focus is expanding the pool of non-executive directors, as he expects more ETA-type transactions to be completed in the next 12 months.
Wyma notes that search ecosystems elsewhere have taken time to develop, with successful search fund CEOs eventually forming “the next generation of active investors, mentors and board members”.
“This reinvestment of capital, experience and values creates the flywheel that allows the ecosystem to develop and flourish,” he says.
Japan: Rethinking the playbook
In Japan, a growing wave of family businesses facing succession issues prompted the launch of two search fund accelerators in 2018 and 2020.
Atsushi Takemaru, director at venture capital firm Inclusion Japan (ICJ), says these accelerators operate similarly to traditional private equity: They identify a target, arrange the necessary capital, and then bring in an operator of their choice.
But as Japan’s search fund ecosystem matures, this model is showing its limitations, he notes. Accelerators typically have greater decision-making power and a larger equity share than the operator, which can disincentivise talent.
“As a result, not much talent is coming into the Japanese market for search funds,” he says.
ICJ is taking a different approach. In February 2025, the firm launched what it bills as Japan’s first institutional investment fund solely for search funds.
To give aspiring entrepreneurs more skin in the game, ICJ will take no more than a 20 per cent stake, with the searcher raising the remaining capital from other investors.
Says Takemaru: “By leading the search, raising the capital yourself, finding the company and closing the deal, it’s a completely different experience for the operator. We believe our investment model may thus be better suited to where the Japanese market is currently at.”
ICJ’s fund has raised US$7 million from three investors – Takashimaya, Mitsubishi UFJ Trust and Banking Corporation, and Kansai Electric Power Group – and has supported four Japanese search funds to date.
South-east Asia: Some gaps to plug
Beyond Australia and Japan, growth in Apac has been uneven.
Prof Naumovska thinks that South-east Asia lacks the “ecosystem glue”: a network of investors, lenders and advisers.
Debt constraints remain a barrier, she adds. “In some markets, lending for SME acquisitions is less developed, more collateral-driven, and harder to structure around cash flows.”
Without reliable debt financing, deals rely more heavily on equity. But South-east Asian investors – both institutions and high-net-worth individuals – lack awareness of the search fund model.
Matt Windsor – who launched Thailand’s first search fund, Regen Capital Partners – says many players are familiar with private equity or venture capital, but not search funds.
“Family offices and corporates are often already investors with strong deal flow and may wonder: ‘Why would I need to give (a searcher) upfront capital, without a target?’”
Yet, even if international investors are keen, domestic backers remain key, say observers. They provide critical local knowledge – on the economic climate or specific industries, for instance – and in-market connections to support the searcher.
Bundgaard estimates that a searcher’s capital table should minimally consist of 30 per cent domestic equity.
Says Seligman: “If my searcher in China sends me an opportunity in the fabrication space, I might understand what a fabricator looks like in Australia, but not in China. A Chinese investor based there, however, has insights and experience into that dynamic.”
International investors will thus have “a much greater appetite” to back a searcher with strong domestic support, he adds.
The size of a market also affects the ease of acquisition, says Wyma. “Searchers only need to find a single company to acquire, but finding a great business that is for sale on reasonable terms is not easy.”
Each searcher supported by Ambit Partners may screen anywhere from 500 to 20,000 companies before acquiring one.
“As such, there needs to be a sizable pool of companies with appropriate economic characteristics – size, revenue quality, profitability, margins, team and structure – to pursue.”
Searchers from smaller South-east Asian markets could therefore face more difficulty.
Prof Naumovska notes that although Singapore has the right conditions for ETA, its small market – and SME base – limits the number of search funds for domestic targets.
In addition, many SMEs in South-east Asia are still run “in a very founder-centric way”, with informal practices and often unaudited financial statements.
“That makes diligence harder and increases uncertainty for both buyers and lenders,” she adds.
Overcoming cultural resistance
In some parts of Asia, there also remains cultural resistance to selling one’s business to an outsider.
“It’s a common Chinese mindset for many business owners to want to work until the last second of their life,” says Annie Huang, who launched Taiwan’s first search fund, Floreo Capital, in November 2024.
Adds Prof Naumovska: “Selling to a first-time external CEO, which is central to the search fund model, can take longer to get comfortable with.”
Australia’s openness to this – given its more Western-oriented business culture – is one reason its search fund ecosystem has developed more quickly than those of other Apac markets, Bundgaard notes.
Still, even highly conservative markets such as Japan have begun to overcome this mindset as succession needs grow “urgent enough”.
He says: “Japan has now become an attractive market for search funds, because so many family-owned businesses are reaching a point where there is no other option for succession.”
Huang sees this shift in Taiwan, too. Many SME owners say she is a “silver lining” that will finally allow them to retire.
A flash in the pan, or the real deal?
For now, it remains too early to tell if search funds will thrive in Apac.
“Apac should be the biggest – and most successful – market for search funds and ETA activity, because the fundamentals are there,” says Seligman.
However, approaches to ETA must be tailored to individual markets, given the region’s wide diversity of cultures and economies, he adds.
For Wyma, the success is measured by how many entrepreneurs launch searches, acquire and grow companies, create wealth, and deliver meaningful returns.
“This all takes time, and search funds have long feedback cycles – it’s not an instant gratification path,” he says.
While exits can occur within four to seven years post-acquisition, some of the best outcomes “have come from compounding over even longer periods, with liquidity opportunities for investors along the way”, he adds.
So far, only three of the 21 Apac search funds backed by Ambit Partners have completed acquisitions. No exits have been made yet.
Failure, too, is par for the course. According to a 2024 IESE Business School study, roughly one in three international search funds fails to make an acquisition. Among those that do, a third incur losses.
Vietnam’s first search fund, LT Partners, launched in 2022 but ultimately dissolved after failing to complete an acquisition.
As the first movers in Thailand and Taiwan, respectively, Windsor and Huang are well aware that the outcome of their searches could be a turning point for their markets.
“I’ve already raised the search capital, so if I don’t close a deal, that capital is lost,” says Windsor. “But I’m optimistic that I will find a target in the next two years.”
Still, Seligman argues that a single example “isn’t enough” to prove or disprove a market’s viability for search funds. Although four search funds he backed have failed, successful acquisitions elsewhere in Australia have encouraged others to give the model a shot.
Wyma advises prospective searchers and investors to approach ETA efforts with diligence, saying: “This is by no means a guaranteed or easy path to success.”
TRENDING NOW

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Income Insurance appoints former Manulife Singapore top man as new CEO

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

