

Sembcorp’s ease in curtailing emissions exposes a sustainable financing loophole
Wong Pei Ting
WHEN industrial and urban solutions group Sembcorp Industries ran its Investor Day earlier this month, it reported a drop in its emissions intensity so steep that it has surpassed key 2025 targets well ahead of schedule.
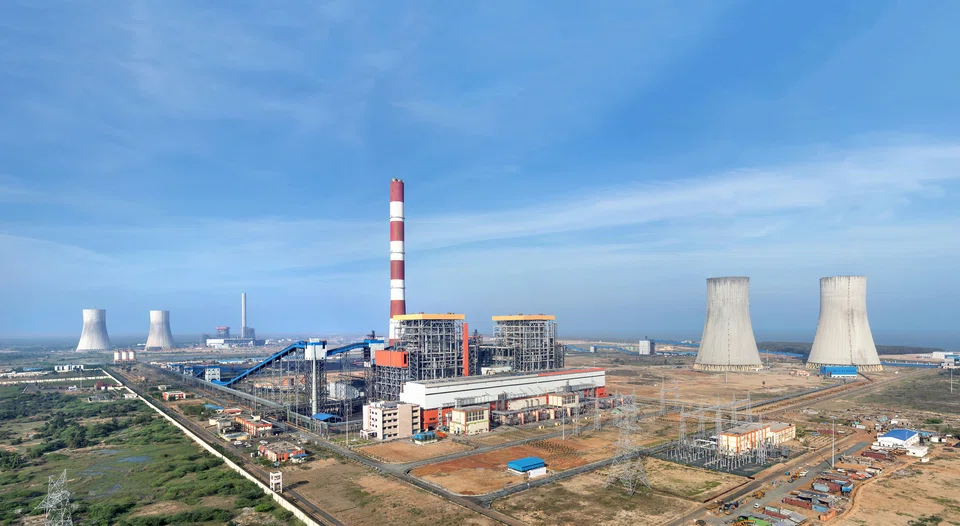
A closer look reveals that most of the improvement did not come as a result of Sembcorp making its existing businesses greener, but from divesting a high-emissions asset.
In other words, Sembcorp’s improved emissions profile has not led to a reduction in real-world emissions – it has merely moved a large amount of emissions out of sight.
The way that markets record and assess businesses’ emissions needs tweaking, so that the balance of incentives motivates actors to seek real-world decarbonisation over paper omissions.
Taken at face value, Sembcorp’s progress in greening its business looks impressive.
From an emissions intensity of 0.54 tonne of carbon dioxide equivalent per megawatt hour (tCO2e/MWh) in 2020, Sembcorp is now on course to report emissions intensity of 0.3 tCO2e/MWh this year. That is already below the company’s 2025 target of 0.4 tCO2e/MWh. Sembcorp has now adopted a 2028 target of 0.15 tCO2e/MWh for emissions intensity. Those targets cover only Sembcorp’s Scope 1 and 2 emissions, which measure the company’s direct emissions and emissions from its power consumption.
The progress puts Sembcorp on track to avoid coupon step-ups on two of its three sustainability-linked bonds (SLB) that have a combined S$975 million of principal.
The improvement in Sembcorp’s emissions intensity came mostly because the company sold off Sembcorp Energy India (Seil), a coal business, to a private consortium. If Seil was still part of Sembcorp in 2022, Sembcorp’s emissions intensity would have been 0.5 tCO2e/MWh instead of 0.29 tCO2e/MWh without Seil. But with the divestment, Seil’s emissions no longer belong to Sembcorp’s Scope 1 and 2 emissions.
Some of Seil’s emissions will actually continue to show up in Sembcorp’s Scope 3 tally, which covers indirect non-power emissions. That is because Sembcorp provided a “deferred payment note” facility to the buyers of Seil, and will continue providing technical services to Seil.
But Sembcorp’s emissions intensity targets – which are also the targets that determine the interest payable on its sustainability-linked debt – only cover Scope 1 and 2 emissions. Tucked away in the Scope 3 ledger, Seil’s emissions intensity will not affect Sembcorp’s performance against its targets.
Has Sembcorp almost halved the emissions intensity at each of its power assets, or in its natural gas business, or grown its renewable business so much as to move the needle so sharply? Not quite. All that has happened is that a troubling source of emissions has been moved out of the relevant reporting scope. Out of sight, out of mind and free from consequences.
The problem is that the prevailing approach to emissions reduction looks only at whether the metrics have changed, but does not consider how and why the metrics changed.
One possible fix is to prevent a company from reporting lower emissions immediately after selling a high-emitting asset. For example, companies could be required to continue including an asset’s last-known emissions for a certain number of years after divestment when that asset belongs to known problem classes, such as coal plants or transportation equipment. The length of time the company should continue to own the emissions of the divested high-emitting assets can be calibrated based on an established methodology that accounts for the remaining life of an asset.
Without the ability to immediately exclude emissions after a sale, companies that need to lower emissions in the short term can only achieve it by organically lowering the asset’s emissions.
If there is borrowing involved, banks and financial institutions could consider imposing on borrowers “responsible divestment” requirements for known problem assets. Such requirements could include steps to ensure early retirement for coal-fired plants, and that they be replaced with lower-carbon alternatives.
To prevent scope “leakage”, the financial ecosystem should also make it a norm for Scope 3 emissions to be included in targets, especially when Scope 3 emissions represent a substantial share of a company’s total emissions. It is jarring that none of the early vintages of SLBs include Scope 3 emissions in reduction targets, as the Anthropocene Fixed Income Institute (AFII) pointed out in a report last week. Companies should not have too many shadows in which to place inconvenient emission sources.
There is hope yet. AFII, a non-profit that monitors the sustainable finance market, highlighted a growing trend of bonds taking Scope 3 into account. Four of the five euro-denominated SLBs issued in the first week of September alone feature Scope 3 targets, it said.
Scope 3 inclusion can further assert a healthy pressure for companies whose supply chains overlap to align their climate ambitions and cut emissions together. Mutual monetary benefits can nudge business partners to deal productively with one another.
Sembcorp’s freshly minted 2028 target will require the company to halve its emissions intensity in the next five years. Will the company – and many others in a similar situation – turn again to a divestment solution to achieve the goal on paper? Or will it strive to accomplish progress that is reflective of actual decarbonisation? The financial ecosystem must encourage a more meaningful outcome.
TRENDING NOW
Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Nearly half of Singapore workers put in at least six unpaid hours a week: survey
Vietnam’s data-centre investment rush faces reality check on power and site constraints

