

Shadow banks are too big to stay in the shadows
Mega hedge funds are so critical to modern finance that they should be regulated more like lenders
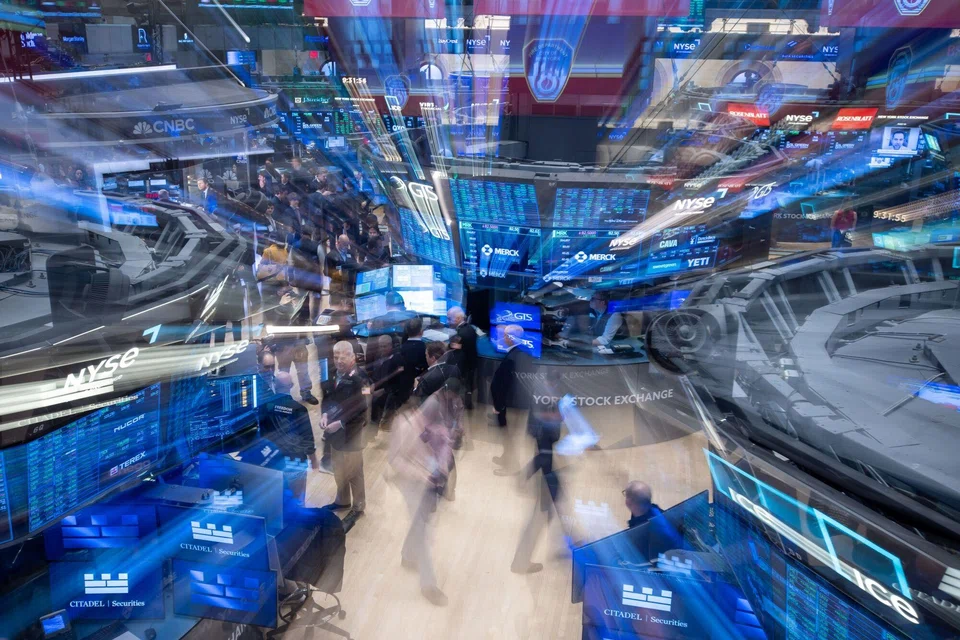
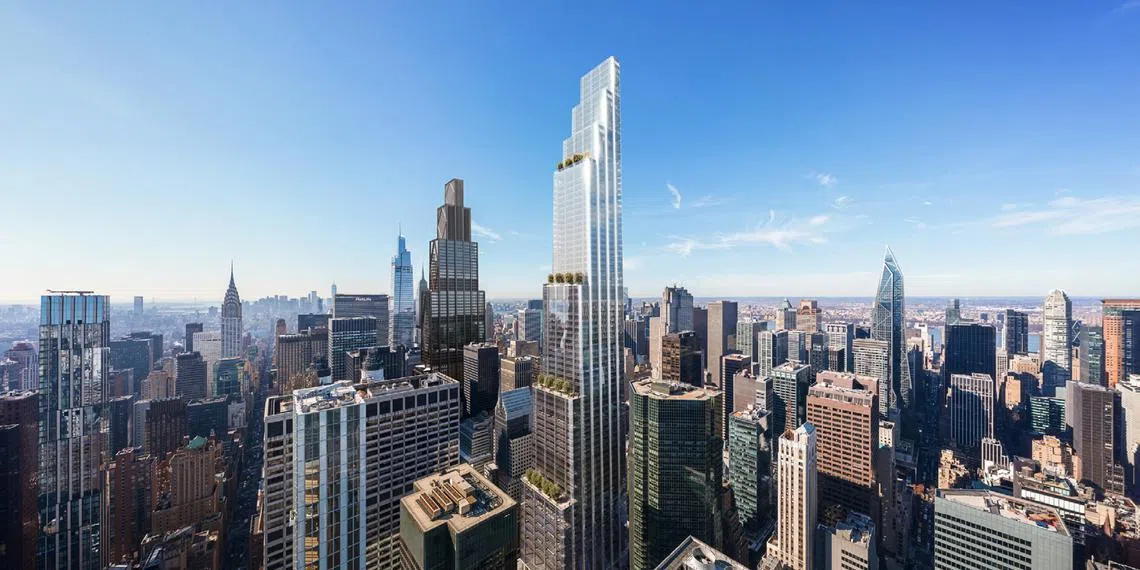
WHEN it is finally completed seven years from now, Citadel’s New York tower will be the second-tallest building in the city, after the World Trade Centre. It will also loom over the headquarters of JPMorgan Chase just a few hundred metres south along Park Avenue.
That the world’s most valuable bank will be literally in the shadow of a key pillar of shadow banking is an overt and irresistible metaphor for how financial power has shifted over the last 15 years – from traditional lenders towards enormous, less restrained repositories of money, such as Citadel.
Shadow banks do a lot of the work that commercial banks do without being hampered by strict government regulations. That means these operations – particularly, hedge funds and private asset managers – can invest more aggressively, taking on greater risks and potentially earning greater rewards.
It does not mean, however, that they do not pose a systemic risk to global finance and economies. They are woven intricately into similar transactions and obligations that have periodically made banking collapses existential threats, yet the risk they pose goes relatively unchecked and under-examined. That should worry investors, policymakers, regulators and consumers.
Moreover, investors and lenders enmeshed with shadow banks do not have bailout protection. If downturns or more brutal stresses arrive, their trades are not necessarily backstopped by central banks like the US Federal Reserve, as traditional bank lending can be.
Central banks have had to step in and shore up wobbly banks and markets numerous times over the last century (including during the 2008 financial crisis, the 2020 dash for cash and more recently, when Silicon Valley Bank and other small lenders were imperilled). There is no reason not to expect another rough patch to emerge at some point, yet shadow banks largely operate under the radar and with unprotected lenders.
As markets tank again in response to President Donald Trump’s “Liberation Day” tariffs, there is a real risk of a crisis of faith in the US as a reliable world power – and crucially in its Treasury bonds, which underpin shadow banking. Big hedge funds have at least avoided disaster in the tariff rout so far.
That is why some experts are arguing for permanent shadow-banking safety nets. If taxpayer funds need to be pledged to do that, then regulators will have to consider tighter supervision of shadow banks as well – even though some Republicans in Congress are calling for a rollback in potential federal oversight.
The players
Citadel, a US$65 billion hedge fund, does not have JPMorgan’s US$4 trillion “fortress balance sheet”, but it probably has as much, if not more, power to shape markets. The size and influence of major alternative asset managers has only grown since 2020, and the hedge fund industry has become more concentrated among the largest players like Citadel, DE Shaw and Millennium. Hedge funds collectively now use more borrowed money to fuel their trades than at any time since the Fed began to collect data in 2013.
Will these secretive alternative institutions be at the heart of the next financial crash? Citadel and the other big hedge funds argue they do not need more regulation because they are safer than banks.
They say that locking up investors’ money for longer terms means they do not rely on the kind of panicky depositors who start bank runs. Even so, shadow banking is entwined with traditional lenders and also depends on funding from money market funds – whose depositors can become just as flighty during crises.
It is certainly possible that these big funds are more stable than most people imagine. Citadel offers a useful example of why that might be. But even the most well-managed of firms are still vulnerable to system-wide shocks. When a major crisis hits, markets that normally seem uncorrelated can suddenly move together with terrifying speed – and the distance between safety and doom vanishes. Or as statisticians like to say, correlations go to one.
Anyone interested in determining what might be done to prevent a shadow banking-induced meltdown should ponder some recent financial history.
When Lehman Brothers collapsed in September 2008, many analysts and bankers hoped this would be an isolated failure. But federally backed lenders like Fannie Mae and Freddie Mac also got swept into the emerging vortex, as did major US banks like Washington Mutual and Wachovia.
Soon after, giants like Citigroup and Bank of America needed federal life support. A systemic crisis had arrived in the US and far beyond. Total losses eventually exceeded US$2 trillion, US home prices fell by one-fifth, unemployment doubled to more than 10 per cent and America suffered its deepest recession since World War II.
Politicians and financial regulators then created wide-ranging rules to prevent the same thing from happening again. But even after 2008, there was still a market for risk.
Private equity firms still wanted to buy sluggish businesses and load them up with potentially risky debt to drive greater pay-offs when selling them on. And speculative arbitrage – that is, buying and selling related assets in different markets and profiting off the price gaps – was still needed to help price bonds and derivatives, and keep markets liquid.
Investment banks did this work before 2008. Today, hedge funds have picked up the liquidity-supporting functions, but without the limits on borrowing or reporting requirements that even stand-alone investment banks like Lehman Brothers had to observe.
Market-based finance has boomed far more than regulators ever expected. Globally, what regulators call non-bank financial intermediaries – the shadow banks as well as pension funds and insurance companies – have grown at an average annual rate of one-and-a-half times faster than traditional lenders.
Total shadow-banking assets have more than doubled globally to US$240 trillion. Among these, funds specifically involved in supplying credit to companies and people grew to US$70 trillion, according to the Financial Stability Board (FSB), a watchdog group. In the UK, almost all debt taken on by companies in Britain since 2008 has come from markets, not banks, according to the Bank of England (BOE).
Investment banking and commercial banking were once sharply divided in the US. The thinking for much of the 20th century was that it was wise to insulate retail banks and their ordinary depositors from riskier Wall Street trading. The regulation that insured that division, the Glass-Steagall Act, was repealed in 1999, which laid the groundwork for many of the risky financial fashions that gave rise to the 2008 financial crisis.
Ken Moelis, who founded his own small investment bank, Moelis & Co, in 2007, has said he expected the 2008 crisis to force the financial world to revert to its divided, pre-1999 state. He thought that would happen slowly, however. As he told a conference in December, “What surprised me, is that it’s not taking 30 years.” Financing, he said, “is radically changing from a bank-centric market where it was for most of my career, to an alternatives, life insurance, pension fund, sovereign wealth (market)”.
If plain-vanilla banking and more high-flying shadow banking truly did inhabit different worlds, that might offer some comfort to anyone worried about systemic risk. But this clean “division” is an illusion.
A mighty citadel
The total assets of hedge funds are more than 15 times greater today than in 2008. Mutual funds are still larger, but the big hedge funds are more influential because they trade more and can use borrowed money to amplify their firepower.
Citadel is the most profitable hedge fund in history, at least by one measure. Ken Griffin, who founded the company in 1990, has led his firm to total net gains of US$83 billion since then – putting it ahead of other big hedgies such as DE Shaw, Millennium, and Bridgewater – according to LCH Investments, a research firm.
The fund’s success argues against instability fears that haunt shadow banking. That is due in part to Citadel’s long track record. But its approach to borrowing and risk management are also major strengths.
Citadel is a multi-strategy fund with hundreds of managers trading almost every market imaginable. This protects it against losses in any single area, and makes it more attractive as a client to banks and brokers. Voluminous trading and diversification are virtues, particularly in the eyes of big banks that have been lending heavily to hedge funds, private asset managers and other non-bank rivals.
Direct lending by banks to financial firms including hedge funds and private asset managers has been the fastest-growing part of the US banking system. It hit US$1 trillion last year, according to a recent Bloomberg News analysis.
Multi-strategy funds are the biggest borrowing beasts among hedge funds. Their average gross debt is currently about US$12 for each US$1 in the fund, the highest ratio on record, according to the US Treasury Department’s Office of Financial Research (OFR). That kind of leverage can amplify returns when invested successfully, but destroys capital faster when trades go wrong. The demise of Long-Term Capital Management in 1998 is a vivid reminder of how swift and ugly such debacles can be.
There is another problem with borrowing money: when lenders want it back, funds can be forced to dump trades and eat losses. Broader markets can wind up bruised as well.
Citadel has built uncommon defences against those scenarios that make it less vulnerable to panicky lenders. Unlike peers, Citadel has issued US$1.6 billion of investment-grade public bonds. That is a small part of its overall borrowing, but it does not need to be repaid for five years. No other hedge fund has gone as far as issuing investment-grade debt to lock in funding for longer terms that insulates them from short-term market disruptions.
Citadel has longer-term finance from other sources, too, according to S&P Global’s credit rating team. It has six-month agreements with its prime brokers at investments banks. It seeks longer terms from another important source of leverage, especially for trading US Treasuries, the repo market, where funds swap bonds for cash.
It also holds billions of US dollars, equivalent to about 30 per cent of its fund, in cash and other liquid assets, according to S&P. That can offer extraordinary resilience, too. Back in early 2020, when Covid-19 was sparking mayhem, Citadel did not burn through all this financial buffer.
Now you see it, now you don’t
Citadel may be an isolated example, however. The top 10 US hedge funds more than doubled their repo borrowings since the start of 2023 to US$1.4 trillion, according to the OFR. And although other mega funds might try to mimic Citadel’s approach, the data on how prudently they are actually managing the terms of their funding is not available. That leaves central bankers in the dark about their vulnerabilities.
Where might those weaknesses reside?
Big investment banks increasingly finance multi-strategy hedge funds on a portfolio basis, meaning they lend against trades cumulatively rather than individually. The idea is that the risks of some bets should balance others, making banks feel more comfortable about lending.
Diversification feels like insulation – until it does not. The Covid-19 pandemic proved the point in 2020 when there were not any safe havens. Portfolio lending can also transmit losses from one market to another. If a hedge fund’s trades in corporate bonds go wrong, for example, it might sell other assets, such as Treasuries, to meet lenders’ demands for cash, stressing government bond markets. Or the problem could start in government debt markets.
Hedge funds’ trading also affects other asset managers along the shadow banking chain, which is where the risks of sudden instability are least well understood. Consider Treasury basis trades, a form of highly-leveraged arbitrage that keeps the Treasury market humming along. While extreme leverage itself is inherently risky, basis trades also play a role in supplying credit to companies – a phenomenon that has been under-examined.
A basis trade typically involves buying Treasury bonds and selling Treasury futures. But mutual funds are some of the biggest buyers of Treasury futures to support their corporate debt investments. If hedge funds had to rapidly unwind basis trades under duress, or regulators suddenly imposed tough limits on leverage, lending from markets to companies would likely shrink, too, hurting the economy.
Most importantly, hedge funds are at the mercy of money market funds, the source for much of their borrowed cash. These instant-access cash funds have doubled in size to nearly US$11 trillion worldwide since 2008, according to the FSB, and are considered super safe because they are mainly meant to own stable government debt.
But in the US, money market funds lend up to one-third of their cash into the shadow banking system by swapping it for Treasuries for short periods, according to research from the Bank for International Settlements. The risk is overt because many trades are ultimately financed with short-term funding (the opposite of the strategy Citadel uses to try to reduce term risk).
Money funds are the de facto depositors in the shadow banking system and their investors can demand their cash back any time. Who bears the risk of this so-called maturity transformation? In the now-you-see-it, now-you-don’t world of shadow banking, it is partly big hedge funds themselves, and partly the repo brokers that source funding for them (and those brokers are often part of big banks).
Connections across markets and fund types – and the hedge fund fulcrum on which they rest – are all underappreciated. Big hedge funds are better managed in many ways today than Long-Term Capital Management was in the 1990s, but there are many more of them now, they are much bigger and more influential, and their borrowings on average are at record highs. A failure today would likely be far more damaging to the wider system.
What should regulators do?
Klaas Knot, president of De Nederlandsche Bank, is not popular in hedge fund land. He currently chairs the FSB, a group of global central bank chiefs and regulators. He has launched task forces to investigate shadow bank leverage and how big hedge funds might spark or accelerate sell-offs.
Watchdogs like Knot could end up focusing too tightly on specific firms and activities, when they should be examining the entire shadow banking chain instead. Any regulatory system that works will have to subject all large hedge funds to stricter guard rails and treat them more like banks.
Some backstops are already being considered or are in place. A group of academics recently urged the Fed to set up a lending facility for major hedge funds that could be deployed if a crisis in Treasuries arose. The BOE has opened a new lending window for pension funds and insurers, to protect UK government debt markets from a repeat of the near-meltdown that occurred in 2022.
Expanding central bank support to hedge funds would be very unwise when the Trump administration and House Republicans want to reverse a Biden-era policy that gave regulators a route to greater oversight of shadow banks.
Reforms should not mean setting a strict limit on how many dollars hedge funds can borrow per dollar of capital, as has been floated by the FSB. That is too blunt, as the industry has correctly pointed out. A fund levered at 10-to-1 that invests mostly in government debt is far less likely to get wiped out than a fund that puts the same amount of borrowed money into stock markets.
What is needed is a set of complementary guard rails, including a simple leverage ratio, models of the worst losses likely over each month or year, and a measure of spare cash at hand. These three gauges are akin to how regulators have controlled banks since 2008: risk-based capital, leverage and liquidity.
Seeing clearly how different mega funds manage their risks and borrowing terms would help the Fed decide whether any firm is too aggressive, and could signal appropriate operating limits for all. Much more transparency is needed.
Regulators should require shadow banks to report much more – at least confidentially – about their balance sheet management. Regulators and central banks can then think more clearly about the systemic risks of today’s big, influential and interconnected funds.
If we have learnt anything about financial crises, it is that they can arise in unexpected ways, and many more asset classes and market participants can be swept into a meltdown than expected. When everyone wants cash, even a firm like Citadel can be forced to exit trades rapidly – amplifying market shocks and threatening the supply of credit to the broader economy, which is ultimately what matters to central banks.
The Fed already has the power and some of the tools needed to forestall possible conflagrations. And it has had plenty of practice between the twin wildfires of the 2008 financial crisis and the Covid-19 pandemic. But it also needs greater visibility into the risks inherent in the shadow banking network.
The shadow banks are so enmeshed with traditional lenders and money funds, that ignoring their capacity to spur another Lehman Brothers moment means flirting with the possibility of financially-driven economic disaster. BLOOMBERG
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Britain’s mansion tax shows the difficulty of targeting wealth
Three hats, one goal: How Ng Kian Swan runs sustainability at NUHS
COE review: The gap between luxury and mass-market cars isn’t the only one worth bridging

