

Should the Code of Corporate Governance be refreshed to complement the EQDP?
A look at the UK approach might be instructive
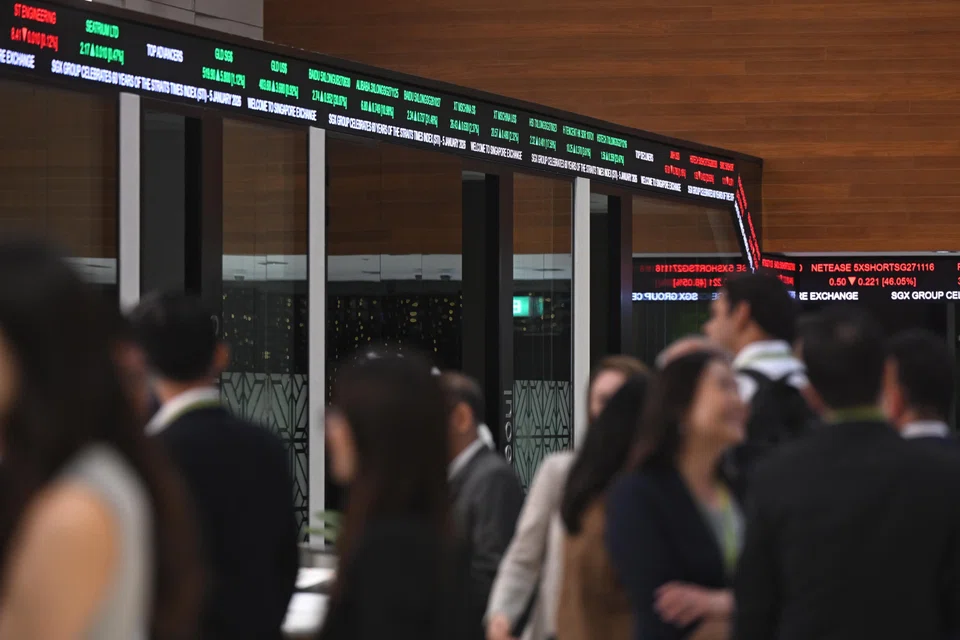
THE Singapore Code of Corporate Governance was last comprehensively revised in August 2018. Apart from targeted refinements – including the January 2023 move to hard-code the nine-year rule for independent directors – the framework has remained largely intact since.
There is no doubt that the Code has served the Republic well. However, markets evolve and with the launch of the Equity Market Development Programme (EQDP), Singapore has entered a new phase of capital-market activism aimed squarely at improving liquidity, valuations and investor participation, particularly beyond the largest blue-chip names.
These smaller firms stand to benefit the most from renewed investor interest, but confidence in this segment is often the thinnest and its disclosures lag those of blue chips. In short, governance standards among second and third-liners are below those of the larger companies.
Singapore’s governance framework already rests on a comply-or-explain philosophy, with regulators emphasising substance over box-ticking. In practice, however, explanations vary widely in quality. Too often, investors are left with generic statements that comply formally but inform poorly.
The problem is that one-size-fits-all expectations can unintentionally encourage boilerplate reporting, particularly among smaller issuers with limited resources but complex realities.
If a review of the Code were to be considered, the United Kingdom offers a useful reference.
Alongside the UK Corporate Governance Code for premium-listed companies, smaller and growth-oriented firms are entitled to adopt the Quoted Companies Alliance (QCA) Corporate Governance Code, which is designed specifically for smaller companies. It offers a flexible, principles-based approach rather than rigid rules, allowing them to grow without stifling innovation.
The QCA Code is applied by some 700 companies, including 92 per cent of those whose shares are traded on AIM (the UK equivalent of the Singapore Exchange’s Catalist), many constituents of the Main Market, three-quarters of companies quoted on the Aquis Stock Exchange, and private companies which may opt to float in the future.
The QCA Code is explicitly principles-based and outcome-focused, asking companies to explain how governance supports strategy, culture, risk management and stakeholder engagement – rather than prescribing rigid structures.
Companies are expected to explain how each principle is applied in light of their size, ownership structure and stage of development. In essence, the QCA Code helps smaller, growing companies achieve good governance in a way that suits their size and resources, making it a popular choice for those seeking to mature responsibly.
Singapore could adapt this logic without lowering standards. A differentiated approach to governance – accounting for size – might be the best way to complement the EQDP while providing smaller companies relief from overly prescriptive requirements designed for larger outfits.
Fewer generic explanations, clearer accountability for boards, and more comparable disclosures would strengthen confidence in precisely the segment of the market that the EQDP seeks to revitalise.
Given the regulatory push to bring in more listings and broaden interest beyond index heavyweights, it makes good sense to re-examine the Code.
TRENDING NOW

If Europe goes to war, the fallout will be felt in East Asia

Singapore government slaps loan curbs on individual private-hire car buyers
Wider talent pools, smoother operations: What these S’pore firms gain from inclusive hiring

Philippines’ FDI slowdown exposes uneven investment prospects across S-E Asia

