Singapore residential developers need a more equitable land betterment charge formula
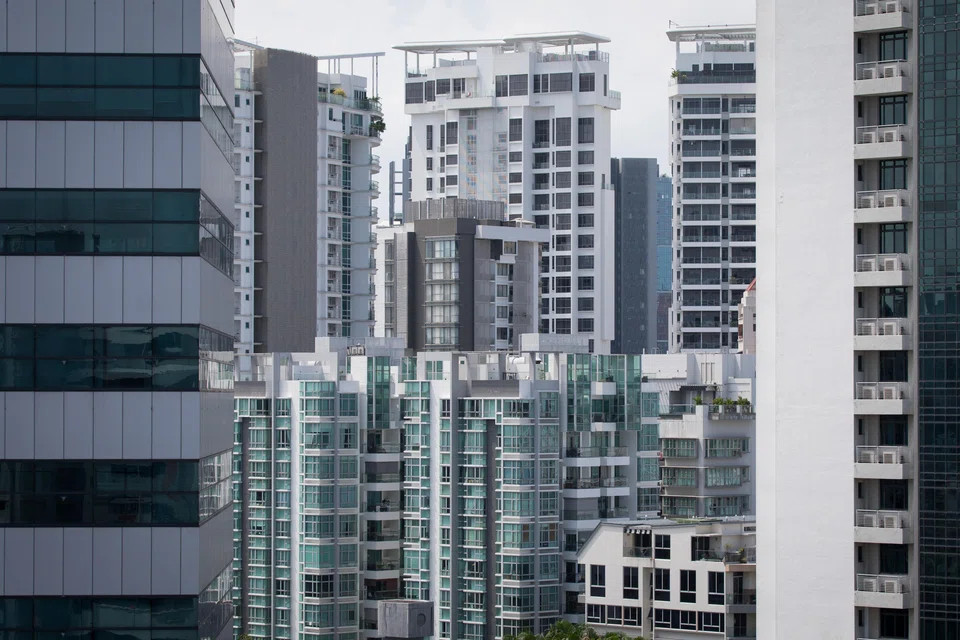
PROPERTY groups’ profit margins for Singapore residential developments have whittled down significantly over the years. And this has weighed on the market valuations for the likes of City Developments , UOL Group , GuocoLand and Wing Tai .
Part of the diminishing margins can be attributed to macroeconomic factors, such as inflation and rising interest rates, as well as dampeners in the form of property cooling measures.
However, one often overlooked component is the land betterment charge (LBC) – formerly known as development charge (DC) – that developers in Singapore need to pay to the government if they want to enhance the use of some sites or build bigger projects on them.
Since Jul 18, 2007, the formula that has been used for computing DC – and later LBC – creams off 70 per cent of the appreciation in land value when some sites are put to higher use or built on more intensively. The previous DC formula was based on 50 per cent of the increase in land value.
When the change in the DC formula took place in 2007, the Singapore property market was in a bull phase, with an en bloc sale boom in full swing.
The authorities said then that the change was not to cool the market, but to achieve a “more equitable sharing of gains between landowners and the state”.
Observers saw the move as the state laying claim to a larger share of the real estate boom, since many of its initiatives spurred the strong demand that was driving the local residential and office markets.
Sixteen years on, however, the situation is rather different.
“ABSD is the bane of developers… In the face of emaciated profit margins, something’s got to give. ”
It has almost come to a point where shareholders could quite justifiably question management of listed developers about the rationale for continuing the Singapore residential business.
It may be time for the authorities to revert to the previous LBC formula, where the state took half, not 70 per cent, of the enhancement in land value. Doing so would boost developers’ motivation to redevelop older properties and rejuvenate the cityscape.
The Urban Redevelopment Authority (URA) in 2019 launched a couple of rejuvenation incentive schemes. One of them sought to inject more live-in population into the Central Business District (CBD), by encouraging the conversion of older office buildings in some parts of the district into projects with a wider diversity of uses – including residences and hotels.
Projects approved under the CBD Incentive Scheme are granted additional gross floor area (GFA) of 25 per cent to 30 per cent. Notwithstanding this, the owner of an old CBD office block may not find it worthwhile to embark on redevelopment if there is a big LBC component, observers said.
The government needs to leave more on the table to reward developers sufficiently for the risks of undertaking such projects, especially if the redevelopment includes residences.
Ageing buildings across Singapore – be they office or residential – may be strata titled, with units held by many owners.
For redevelopment to take place, owners typically team up to sell their strata units to a developer via a collective sale. Where LBC is involved, it may be easier to persuade owners to go for an en bloc sale if the state were to take a smaller share of the increase in land value.
As Tan Hong Boon, executive director of capital markets at JLL Singapore and a veteran in collective sales, said: “For a lot of the potential en bloc sale cases emerging these days, the LBC payable by developers to the state is substantial. This eats into the price left for owners.”
Shrinking en bloc premium
The en bloc sale premium – how much more an owner stands to receive from selling their unit through a collective sale compared with disposing of it individually – in some cases has been eroded to just 20 per cent to 25 per cent; this may be too low to garner the minimum 80 per cent consent level from owners, Tan added.
En bloc premiums used to be higher – at about 30 per cent to 50 per cent during the previous en bloc cycle in 2017-2018, and 50 per cent to 60 per cent, if not more, during the 2006-2007 boom, he recalled.
LBC features not only in some redevelopment projects. The tax may also be payable for projects on greenfield sites bought at Government Land Sales (GLS) tenders. An example would be if the developer taps the bonus GFA of up to 7 per cent (beyond what is stipulated in the URA’s Master Plan plot ratio) for balconies, private enclosed spaces and private roof terraces for a residential project.
In short, a formula change in LBC may help alleviate cost pressure on developers in a range of situations. Pre-tax profit margins for Singapore residential projects today are said to be in the high-single digit to the teens, down from about 50 per cent during the super bull run in the 2007-2008 period, prior to Lehman’s collapse.
Higher land and construction costs, interest rates and agent commissions are among the factors that have thinned margins. Moreover, rule changes by URA over the years have crimped a typical condo project’s efficiency – or ratio of total saleable area to GFA – from about 115 per cent to 125 per cent during the heyday around 2007-2008 to about 95 per cent. With lower efficiency, the breakeven cost goes up.
ABSD limits developers’ pricing power
Probably the biggest blow to residential developers here has been the rollout of the Additional Buyer’s Stamp Duty (ABSD) in December 2011.
To qualify for upfront remission of ABSD on residential site purchases – the current rate is a whopping 35 per cent – developers have to undertake to complete and sell all residential units of a development within five years. Otherwise, the developer would have to fork out the ABSD plus interest, a penalty that is very likely to put the project in the red.
Developers have to be careful not to overprice their project at launch, lest they be stuck with unsold units. This limits their pricing power.
A pattern has also been observed of some developers that have bought sites around the same time rushing to finish selling their projects to meet the five-year sales deadline. Thereafter, they tend to become hungry and start bidding aggressively for land, perpetuating a cycle of high land bids and thin margins.
ABSD is the bane of developers. From the viewpoint of fostering a stable property market, however, it is a useful tool to discourage hoarding of land. Without it, developers may be inclined to slow down their launches to create scarcity and push up selling prices.
That said, in the face of emaciated profit margins on Singapore residential developments, something’s got to give.
Revising the LBC formula to accord to developers a more equitable share of the increase in land value could help renew their raison d’etre. It may also provide a much-needed fillip to the languishing share prices of listed developers.