

SOS: Saving One’s Solvency by shaping up – or jumping ship
As corporate stress and distress levels rise, how can companies navigate troubled waters to restructure for a turnaround?
In 2007, businessman Stanley Tan had a premonition: Internet search engines would kill off the iconic Yellow Pages telephone directory.
Before the turn of the millennium, it was common to flip through the thick book to find phone numbers and addresses. But with Yahoo! Search and Google, the same details could now be retrieved with the click of a button.
“The business we were in had been disrupted by the digital alternative,” Stanley Tan told The Business Times. At the time, he was a major shareholder of mainboard-listed Yellow Pages Singapore, publisher of print directories such as its eponymous one.
“It was obvious that we couldn’t do things the same way we did before,” said Stanley Tan. The problem: this was not obvious to the management.
It took a boardroom struggle and dramatic restructuring, but Yellow Pages Singapore eventually became property developer GYP Properties, ceasing publication of print directories from 2018.
In today’s challenging macroeconomic environment, more firms might have to contemplate such restructuring.
A wave of stress and distress
In recent months, industry observers have seen more companies facing stress and distress, and seeking assistance.
Management consulting firm Alvarez & Marsal (A&M) has seen “substantially more” companies with cash and liquidity pressures in the last 12 months, compared to the year before, said Utsav Garg, head of A&M, Southeast Asia and Australia.
“Expenses have gone up, while the top line assumptions that were true 12 to 18 months back are no longer true for many businesses,” he said.
High interest rates, inflation and continued geopolitical uncertainty have meant “strong headwinds for companies with weaker balance sheets, faced with a prolonged period of declining or negative operating profits and cash flows”, said Adrian Chan, partner for turnaround and restructuring, deal advisory at KPMG in Singapore.
Some companies may have overstretched their financials, said Tan Wei Cheong, financial advisory partner at Deloitte Singapore. When interest rates were lower, they borrowed extensively to fuel growth – but if the tide changes, “it can catch these companies by surprise”.
There are also industry-specific factors. Post-Covid activity has driven growth in Singapore’s construction sector, but more construction firms are “bleeding” from past projects as pandemic-era delays raised costs, said Deloitte’s Tan.
Across the region, specific sub-sectors in retail have experienced “significant volatility” post-Covid, said Garg. For one, spending on lifestyle retail – driven by a Covid-era e-commerce boom – has since been diverted towards travel and leisure.
Time could be running out for those in trouble. Amid an uptick in corporate defaults and distress, Setia Law has seen funders and investors “less inclined to take a wait and see approach”, said managing director Danny Ong. Instead, they are quicker to take enforcement action, such as a filing a lawsuit or winding-up petition, or seizing assets.
“Whilst always unpredictable and without a crystal ball, we consider that there will be ever increasing volatility and uncertainty, and more companies needing to restructure their debts,” he said.
Even when times are good, companies may risk falling into distress. Typical pitfalls include poor management of working capital or cash flow, and weak corporate governance, noted KPMG’s Chan.
Weak corporate governance and regular management or board changes could be a sign of internal disputes and infighting, he added.
“These factors often lead to inconsistent or ineffective decision-making, which results in companies haemorrhaging red ink,” he said. Loss-making or overly capital-intensive pet projects may be allowed to continue, even if they cannot be funded sustainably.
For small and medium-sized enterprises (SMEs), there is a risk of becoming distressed if diversification or expansion plans go awry, said Deloitte’s Tan.
He has seen local businesses enter the infrastructure or energy sector in overseas markets that “may not be as well-regulated”. When things went wrong, the companies could not realise arbitration awards – court-granted awards of damages, costs or contract – and had to rely on the Singapore parent for capital.
As such projects are capital intensive and require debt financing, “this would severely affect the Singapore parent’s financial position, despite its profitability”, he said.
When firms expand into non-core businesses by taking on debt, they must make sure “the main ship doesn’t also sink, if business plan assumptions do not pan out”, said A&M’s Garg.
Act before it’s too late
Time is of the essence in restructuring. Said KPMG’s Chan: “Procrastination erodes value – the later a debtor company embarks on a restructuring, the lower the chances are of a successful turnaround.”
Shareholders may be pressured to accept less-than-ideal rescue terms from white knight investors at “a high price of heavy equity dilution” – significantly impairing shareholder value, he added.
The very fact of entering distress can make things worse. If suppliers are spooked by the news, they may “exacerbate the insolvency by amending credit terms to cash only”, said Chan. The loss of customer confidence could also hit revenues.
Setia Law’s Ong frequently sees distressed companies – especially founder-controlled ones – being reluctant to engage with financiers and creditors early, or get external professional help.
They may also resist being open and transparent with financiers and creditors, causing the latter to distrust them. “This often places companies in a worse-off position…and increases the risk of enforcement action being taken.”
Yet seeking help early can work in their favour, said Deloitte’s Tan. Stakeholders such as banks may be more assured that the company is in “good hands” and thus be willing to extend financing.
Such support from critical stakeholders, from banks to suppliers and customers, is crucial for continued survival. For instance, companies may need creditors to agree to a haircut – where claims are settled at a discount – if their assets are insufficient to settle their liabilities in full, he said.
This provides better debt recovery for creditors as compared to liquidation, but the relationship matters, he added: “Unfortunately, emotions and a lack of trust in management may affect the decision-making process of creditors, notwithstanding the worse-off position if the restructuring fails.”
To keep, or not to keep?
Restructuring begins with an existential question: should a company keep its key business, or abandon ship?
That comes down to a question of viability, said Deloitte’s Tan. If the business is no longer viable or has dissipated, any restructuring of debt obligations is unlikely to be successful or permanent, as the company cannot generate positive cash flow to sustain itself.
The strength of the business’ value proposition matters all the more in times of distress when finding a white knight, said A&M’s Garg. “When things are going well, people don’t ask: ‘Why does the company exist, does it really exist, or will it change the world if it doesn’t exist.’”
When trouble hits, however, investors will raise “fundamental and existential” questions about the company’s prospects: whether its revenues will increase, or how it stacks up against competitors, for instance.
In some cases, a turnaround can be achieved by keeping the core business but improving processes.
This is how mainboard-listed abalone producer Oceanus Group steered itself back towards profitability.
In 2014, the group was over S$94 million in debt and on the brink of liquidation. Peter Koh, a retired entrepreneur and shareholder of Oceanus, became executive director and group chief executive officer to help turn things around.
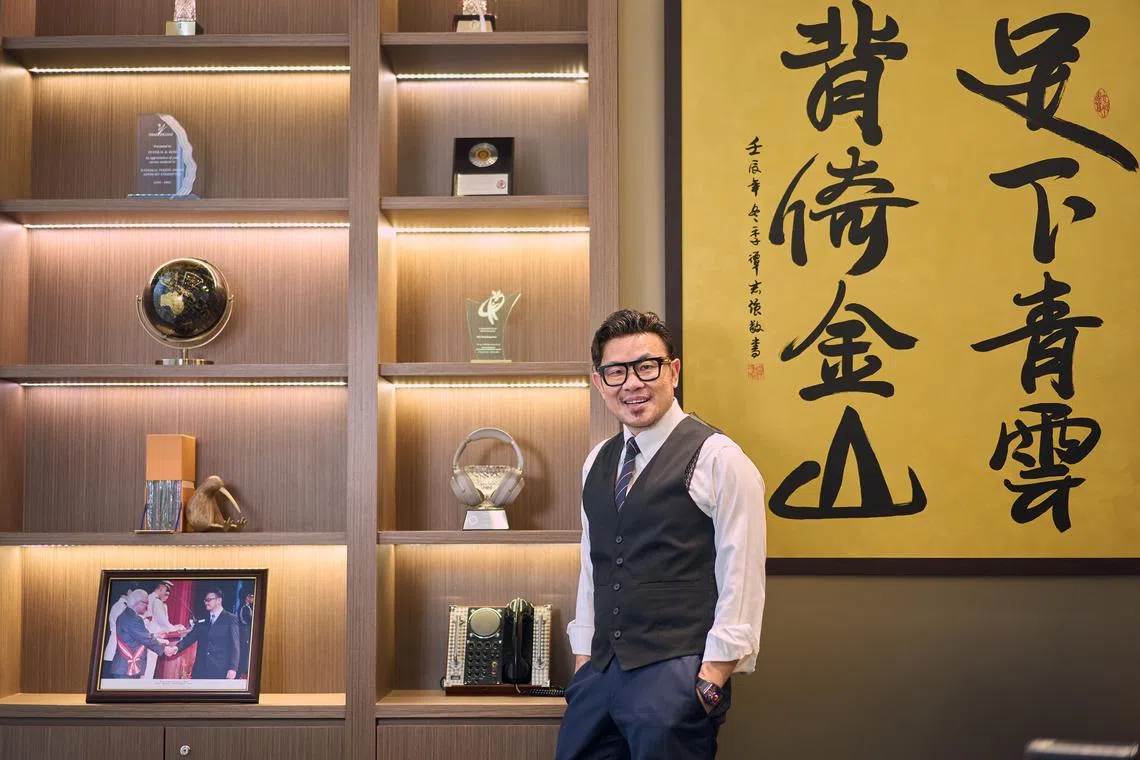
Oceanus’ woes began in 2011, when over 42 million of its farmed abalones in China died in the year’s third quarter, several times the loss in the year-ago quarter. In 2013, a typhoon damaged some of its farms, sinking the group deeper into the red.
Bad luck aside, Koh realised that the group’s Singapore management team lacked oversight of its farms in China, which were run entirely by Oceanus’ China subsidiary.
“Nobody knew what was happening on the ground,” he said. “How do you run a business when you’re not even there?”
There were also costly lapses in corporate governance. Salaries were paid to phantom workers. As the company lacked procurement policies, employees in China often purchased supplies from their friends at marked-up prices.
Koh also learnt that Oceanus was underselling its products due to inadequate market research, and that customers could cancel orders at the last minute with no penalty.
“There were no real corporate protocols and standard operating procedures. Even if there were, nobody followed them and there was nobody to police (them) either.”
He set out to clean up the group’s balance sheet and strengthen corporate governance. His first step was to visit the farms in China and implement new internal controls and best practices.
Today, proper quotations must be obtained so goods and services are purchased at cost-effective prices. Market research ensures the group’s products are priced in line with competitors, while a deposit has been introduced to prevent cancellation of orders.
Koh also conducted sudden and frequent roll calls on the farms to weed out phantom workers.
Oceanus has also improved its business model, lowering land requirements and costs. Instead of farming full-sized abalone, it runs hatcheries for juvenile abalones and supplies these to sea farmers, then buys back the fully-grown ones.
The group managed to cut operating expenses by 70 per cent within six months, and improve its cash flow management. Today, part of its new management team is based in China to directly oversee farm operations.
The group has also diversified into new revenue streams such as abalone distribution and foodtech.
In 2017, Oceanus completed its debt restructuring exercise. In 2021, it exited the Singapore Exchange watchlist after nearly six years there.
No going back: from publishing to real estate
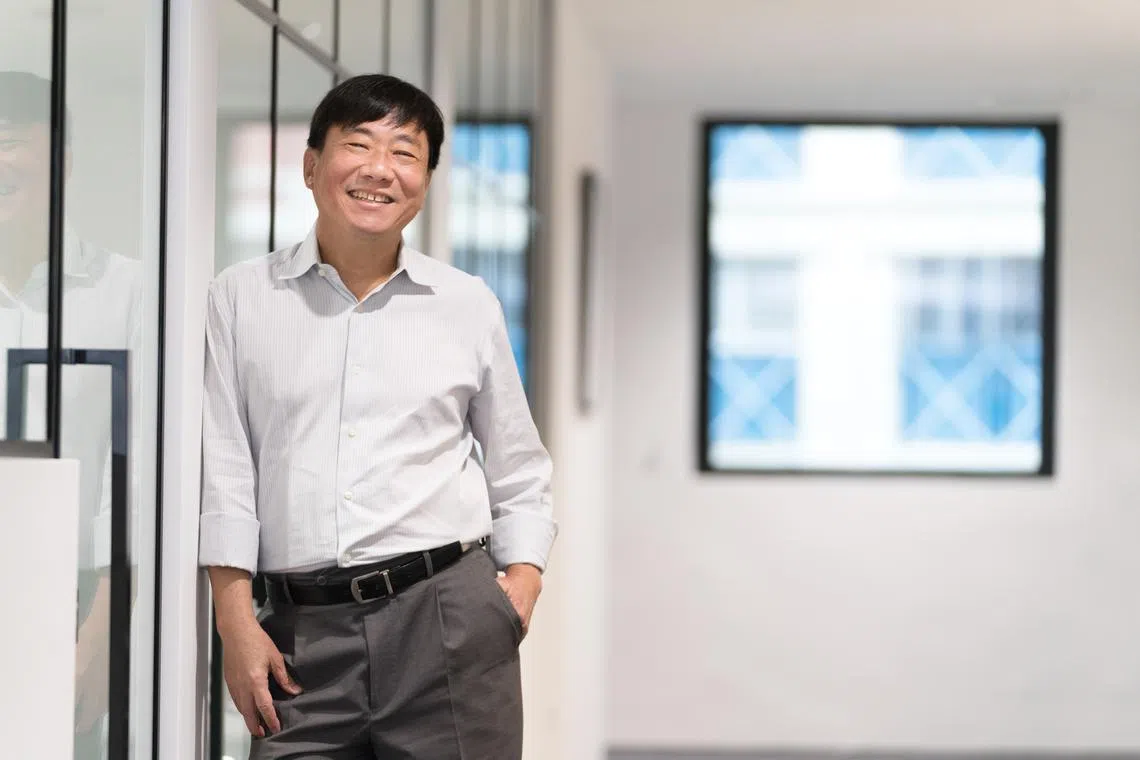
For Yellow Pages Singapore, its print-era success was ironically the biggest challenge, said Stanley Tan. In 2007, print directories were still its main revenue contributor, even though profits from this segment had been declining.
Stanley Tan felt the management was not readying Yellow Pages Singapore to keep up with the times. Instead, the company was entrenching itself further in its old business: signing costly long-term contracts with specialised paper vendors and currency forward contracts attached to paper purchases.
Furthermore, looming over the company was an outstanding S$130 million debt that was due soon – yet management had not indicated any plans to pay it off, he added.
Stanley Tan took these as warning signs that the company, while still profitable, could find itself in trouble if it did not act soon.
His desire for change led to a headline-making boardroom tussle, where he and partner investor Pang Yoke Min called for an extraordinary meeting to oust all four independent directors.
While the attempt was ultimately withdrawn, it prompted the resignation of the chief executive and some other directors. Stanley Tan later took over as chairman and acting CEO in 2009.
As a company in a disrupted industry, Yellow Pages Singapore had three logical options for restructuring, said Stanley Tan.
First, Stanley Tan thought of redesigning its business model to compete with web-based search. However, the fragmented ownership of the Yellow Pages product made this challenging. Each publisher around the world had a different owner.
Stanley Tan attempted to amalgamate the 100-odd Yellow Pages entities worldwide – even officially changing the company’s name from Yellow Pages Singapore to Global Yellow Pages. “But we couldn’t find a common ground.”
Second, he considered offering digital solutions to serve their SME clients. But the company did not have employees with the right skill set to sell and market these, and SMEs had little incentive to digitalise at the time, he said.
He was left with his third and final option: pivoting to a new business. But what?
For Stanley Tan, it was important for Global Yellow Pages to enter a business in which the board had “domain knowledge”. The company ultimately decided to diversify into property, given Stanley Tan’s familiarity and experience with real estate investments.
One shortcoming of the previous board, he said, was that none of its members had experience in publishing or intellectual property, and thus lacked understanding of how the media business was evolving.
“If you have a diverse board with an ownership mentality and industry knowledge, that will equip you better (for) managing changes,” he said. Stanley Tan had earlier founded The Grand Pacific Investment Group, which was involved in publishing and paper-related businesses before being sold.
Since FY2016, real estate has been the largest contributor to the group’s revenue and total assets.
From 2018, Global Yellow Pages stopped operating the Yellow Pages print and digital directories, instead licensing the brand to an associate company, and officially rebranded to GYP Properties. In November 2022, it delisted.
Many other Yellow Pages companies across the world have since filed for bankruptcy. While GYP avoided such a fate, it was still held back by how long it took – almost a year – to seek approval for the new business.
KPMG’s Chan noted that companies which are “not agile enough to invest in productivity or are slow to embrace restructuring to transform their business” may be left behind or have a lower chance of rehabilitation.
Delays in restructuring make it hard to retrain workers for new roles within reinvented organisation, Stanley Tan noted. GYP ended up retrenching workers when it folded its print and digital directories.
Businesses also need to make sure they have sufficient financial resources for the proposed changes, he added.
“Transformation needs to be done quickly and effectively. And when you do it well, all stakeholders will be better off.”
TRENDING NOW

Prima to move out of historic Keppel Road flour mill building in 2028
Temasek-related Azalea, SeaTown, Seviora Capital to merge in 2027
Family offices see more tailored products, leverage ‘collective firepower’ for direct deal access
Singapore room rates soar, but hotels seeing mixed demand from F1 race and events

