

Splitting the bill: How Asia can finance apparel’s decarbonisation
Fixing the mismatch between responsibility, risk and resources is both the sector’s climate solution and Asia’s opportunity
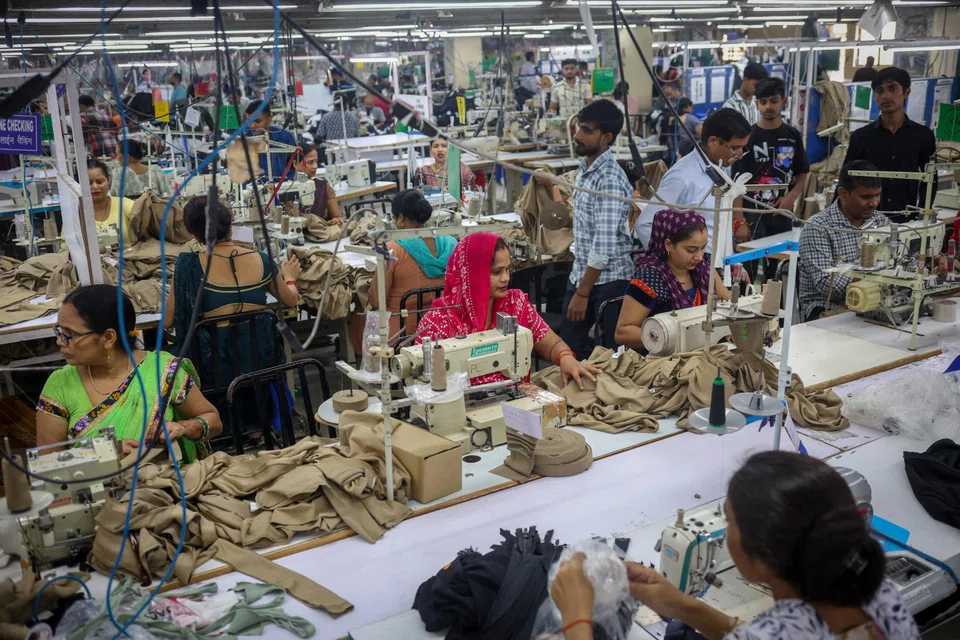
GREENHOUSE-GAS emissions from the apparel sector rose nearly 8 per cent in 2023, according to the Apparel Impact Institute’s annual Roadmap to Net Zero report. The first increase since the institute began tracking emissions, the apparel industry now accounts for roughly 2 per cent of global greenhouse-gas emissions – nearly as much as the entire aviation sector.
The industry’s increasing carbon footprint underscores how current financing and policy efforts have fallen short in driving decarbonisation for the apparel sector.
Today, most of the industry’s emissions lay with suppliers, often in hubs such as Bangladesh, Vietnam and India. But for many of these suppliers, the capital needed for clean energy and efficiency upgrades is inaccessible and unaffordable. Fixing this mismatch between responsibility, risk and resources is both the sector’s climate solution and Asia’s opportunity.
Innovative financing models led by brands and financial institutions have expanded access to finance across global value chains, particularly to suppliers who have long been locked out of the finance needed for decarbonisation initiatives.
Blended finance is emerging as a key tool in enabling access to high impact solutions: Singapore recently launched the Green Investments Partnership fund, aiming to raise US$100 billion from a mix of development finance institutions and commercial investors, specifically for these projects that are typically deemed too risky by conventional financiers.
While Asia is the fastest-growing region for sustainable finance and a rising issuer of green bonds, manufacturing hubs across the region are still struggling to gain access to affordable capital. This is due, in large part, to the complexities that come with real-world emissions reduction strategies, including brand maturity, local regulatory aspects, and the practical hurdles that banks and suppliers face.
There is now broad consensus that brands, producers, financial institutions and governments should share the responsibility of decarbonisation. Without proper incentives or competitive lending, the majority of suppliers – particularly small and medium-sized enterprises – cannot finance even straightforward energy upgrades.
Some financing models have begun to change this, demonstrating merit across the apparel industry, such as the Future Supplier Initiative, a collective financing model that is developing and financing deep decarbonisation projects with suppliers.
These designs can be scaled and replicated across sectors, highlighting the value that collaboration across industry ecosystems can bring to emission reduction strategies:
- Move the risk upstream Brands and buyers must co-invest. Tying procurement to decarbonisation absorbs some of the early performance risk, so banks can price loans more accessibly. De-risking a value chain investment supports suppliers and builds the confidence needed to crowd in additional lenders.
- Blend for scale Combine catalytic grants and guarantees with commercial capital so suppliers can access rates and tenors that make upgrades cash-flow positive. Policy support can amplify this. For example, tax incentives or targeted levies can steer money into renewable energy, efficiency and capacity building, ultimately creating a pipeline big enough for institutional capital.
- Cut the friction out of green lending Simplify the process for green investment: standardise data, eligibility and term sheets so a factory can reuse one “green file” across lenders. Regulators, development institutions and industry bodies in Asia should agree on common criteria for supplier-level loans – just as they did for green bonds.
Decarbonising apparel means building green infrastructure, renewables, electrified heat and energy efficiency, around the incentives of each stakeholder. Brands want resilient, visible supply chains; banks need risk-sharing and standardisation; governments work towards climate and industrial wins; and suppliers require affordable long-term capital.
Already driving the energy transition, Asia has helped renewable energy overtake coal as the world’s primary source of power. Its next climate leadership opportunity is in designing the financial architecture of decarbonisation – ensuring that capital reaches the hard-to-abate, often under-financed factories that power the region’s growth.
Banks, brands, governments and suppliers, it is time we all work together and split the bill for net zero.
The writer is the senior director of sustainable finance and engagement at the Apparel Impact Institute
TRENDING NOW

‘We don’t want to stay as we are’: CEO Patrick Ng builds a more resilient Huationg

URA to review guidelines on floor space to give developers more design flexibility: Chee Hong Tat

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026

