

The stars are aligning for Lendlease Reit to transform into a pure-play retail landlord
The potential sale of the trust’s Sky Complex office property and acquisition of PLQ Mall should excite unitholders
[SINGAPORE] Lendlease Global Commercial Reit (LReit) could be on the cusp of a transformation.
The manager of LReit on Tuesday (Sep 30) disclosed that it has signed a new tenant – an American technology company – at Building 3 of its Sky Complex property in Milan, Italy.
This brings committed occupancy at the seven-storey Grade A office building to 49 per cent, up from 31 per cent in February.
While UOB Kay Hian analyst Jonathan Koh believes that the new tenant will enhance the ecosystem at Sky Complex, he believes that the asset could be “the next potential candidate” for divestment.
“We expect new CEO Guy Cawthra to continue pursuing asset recycling to reposition towards Singapore by tapping on its sponsor pipeline,” Koh said in a note on Wednesday.
He noted that LReit has a sponsor pipeline of more than S$6 billion of assets in Singapore, including Paya Lebar Quarter (PLQ) Mall, PLQ Office, Paya Lebar Green and Comcentre.
Meanwhile, Tony Lombardo, the chief executive of LReit’s sponsor Lendlease, revealed in a recent news interview that Abu Dhabi Investment Authority (ADIA) could be looking to sell its stake in PLQ Mall.
The sovereign wealth fund owns a 70 per cent stake in PLQ, with Australia-listed Lendlease holding the remaining 30 per cent.
Reportedly valued at over S$1 billion, PLQ Mall spans some 340,000 square feet (sq ft), comprising retail space for 200 shops, 100,000 sq ft of open spaces, and a 20,000 sq ft covered outdoor plaza.
“Paya Lebar Quarter is a long-known ROFR (right of first refusal) pipeline for Lendlease Reit,” said DBS analyst Geraldine Wong.
She noted that the mall is entering its second renewal cycle and has stabilised.
She added: “The opportunity to acquire a quality mall could be too good to pass, especially when the current low interest rates is an enabler for an accretive deal to happen.”
Describing PLQ Mall as “one of the newest and best-built malls in the east of Singapore”, Wong noted that LReit would be a “prime candidate” to acquire the property.
The potential sale of LReit’s Sky Complex office property and acquisition of PLQ Mall should excite unitholders.
This could transform the Singapore-listed real estate investment trust (S-Reit) into a pure-play retail landlord.
Already, Lendlease and Certis have put their recently completed Paya Lebar Green office project up for sale, The Business Times reported last week.
A closed expression of interest exercise is ongoing – with an asking price understood to be close to S$600 million – and prospective buyers are expected to make submissions by around mid-November.
In August, LReit also announced that it is divesting the office component of the Juong commercial-retail development Jem for S$462 million.
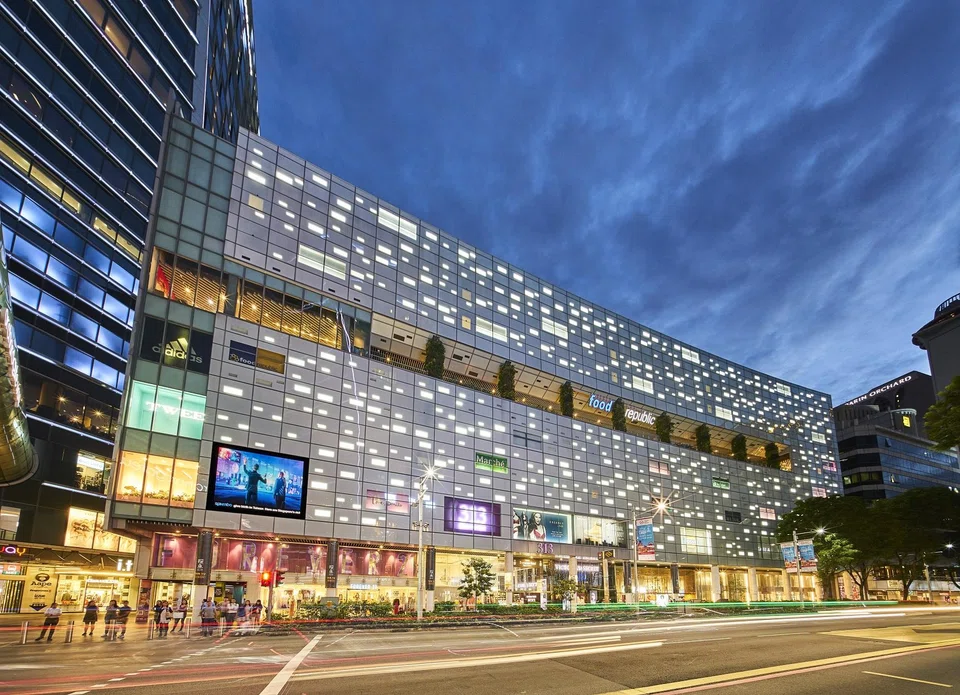
Potentially, LReit’s transformed portfolio – should the moves happen – could then comprise fully Singapore retail properties: the 313@somerset shopping mall on Orchard Road, the retail component of Jem in Jurong, and PLQ Mall in Paya Lebar.
LReit’s retail portfolio has been performing well. For the full year ended June, it achieved positive rental reversion of 10.2 per cent.
The counter has gained 15.5 per cent in the year to date, to close at S$0.635 on Thursday. It has outperformed its Singapore-listed Reit peers, which have climbed 10.5 per cent in the same period.
However, LReit is trading at a price-to-book ratio of 0.74 times, or a 26 per cent discount to its book value.
Could this suggest that it could have some room for upside, should it transform itself into a pure-play retail Reit with Singapore-based assets?
Frasers Centrepoint Trust , a pure-play retail Reit which focuses on Singapore suburban malls, could offer some hope – it trades at a 3 per cent premium to book value.
UOB Kay Hian’s Koh has a “buy” call on LReit with a target price of S$0.79, while DBS’ Wong has a “buy” recommendation and a target price of S$0.75.
LReit’s inclusion in the recently launched iEdge Singapore Next 50 Index could provide some lift. But, perhaps, its metamorphosis into a pure retail play could earn it a re-rating.
TRENDING NOW

Ex-Goldman trader builds mini pod shop in Singapore with offbeat hires

US says China to buy 10 million tonnes of coal in 2027 and 2028

Amberwood at Holland sells 23 of 70 units launched at average price of S$3,019 psf

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

