

Substance over ‘sweeteners’: Redesigning Singapore’s incentives for strategic growth
How the Republic’s incentive framework can align with new OECD rules and advance the national economic strategy
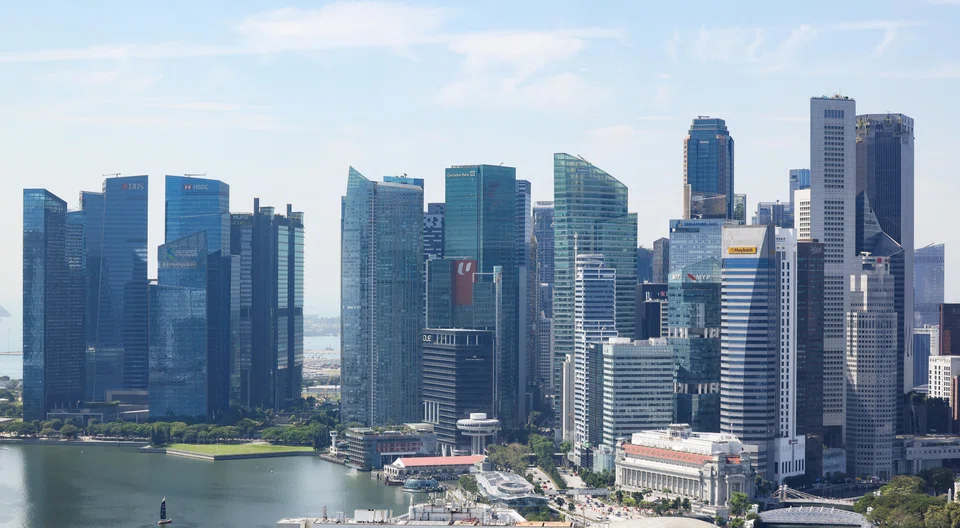
SINGAPORE is at a defining moment in time. Despite global volatility, the city-state secured S$14.2 billion in fixed asset investments in 2025, a 5.2 per cent increase from 2024.
Meanwhile, the playbook of headline tax cuts is being rewritten. The traditional strategy of shifting profits to very low-tax jurisdictions is becoming less effective, following the implementation of the Organisation for Economic Co-operation and Development (OECD)’s Global Anti-Base Erosion (GloBE) Pillar Two Rules – which applies a 15 per cent global minimum tax for multinational enterprises with annual revenues exceeding 750 million euros (S$1.1 billion).
As global tax rules tighten, incentives are increasingly judged less by generosity and more by design quality, economic substance and alignment with national priorities.
The shift aligns with the Singapore government’s recent Economic Strategy Review (ESR), which emphasises competitiveness, innovation, entrepreneurship, human capital and economic restructuring.
With the OECD’s 2026 side-by-side administrative package providing clearer parameters for how substance-based incentives are treated under global minimum tax calculations, Singapore has greater clarity on how its incentives operate within this framework while remaining a competitive tool for anchoring high-growth sectors.
In this environment, sustaining growth will require sharper choices: deploying incentives that encourage real activity, crowding in high-quality investment, and supporting long-term capability building.
From principle to practice
The OECD’s GloBE Pillar Two has fundamentally altered how tax outcomes are evaluated: Incentives based on rate reductions or profit-based relief are at risk of neutralisation through top-up taxes elsewhere. By contrast, incentives tied to real economic substance – people, assets and expenditure – stand on firmer ground, reinforcing the principle that profits should be taxed where activity occurs.
Pillar Two’s focus on economic substance reinforces a longstanding Singapore principle: that competitiveness must be grounded in deep operational capabilities. The government recognises that future job creation will not automatically track gross domestic product growth, making it essential to adopt strategies that intentionally create opportunities and prepare Singaporeans to access them.
The urgency is clear: Job creation eased from 18,700 roles in 2024 to 15,700 in 2025, underscoring the challenge of high-quality employment growth and strengthening the case for incentives that reward workforce development, capability building and productivity gains rather than short-term tax outcomes.
Substance‑based incentives therefore do more than satisfy Pillar Two requirements – they align with national efforts to evolve training models, support lifelong learning, and build an artificial intelligence (AI)-literate workforce across sectors.
These efforts echo national workforce developments in 2025, where companies and training partners were encouraged to expand AI-focused upskilling, deepen research talent pipelines, and strengthen leadership pathways.
Sharper scrutiny on incentive design
The January 2026 OECD side-by-side administrative package, including the substance-based tax incentive, reinforces a clear shift from policy intent to execution. The package provides clearer parameters for how expenditure-based and production-based incentives are assessed in practice.
Importantly, it does not expand the range of incentives available. Instead, it disciplines their use, allowing the global minimum tax to continue functioning as a floor on competition. Incentives must now demonstrate clear links to economic activity, operate transparently and remain aligned with international standards.
This focus on design discipline mirrors the ESR’s emphasis on agility and innovation as Singapore seeks new forms of competitive advantage.
In its mid-term update, the ESR committees highlighted opportunities in advanced manufacturing, trusted services and emerging sectors such as quantum, space and decarbonisation technologies – each requiring policies that can adapt quickly to industry needs and support transformation.
Incentives that are conceptually sound but operationally opaque, subjective or slow to access may struggle to influence investment decisions. The emerging benchmark is clarity, predictability and evidence-based outcomes.
Where the Refundable Investment Credit fits – and where it does not
Singapore’s Refundable Investment Credit (RIC) represents a meaningful evolution in its incentive landscape. By prioritising qualifying expenditure – such as capital spent on new factories or research and development – over taxable profit, it remains attractive under global minimum tax rules and supports capability investments critical to Singapore’s next phase of growth.
The RIC effectively rewards genuine economic contributions over engineered tax outcomes. This tracks with investment trends in 2025, where semiconductor manufacturers, biomedical and chemicals companies expanded their production and research capabilities here because of this alignment.
That said, the RIC is not designed to be a universal tool. For services-led operations, regional management or employment-intensive models, other qualifying tax incentives (QTIs) may be required.
Why a diversified toolkit matters
No single incentive can address the full spectrum of investment needs in a post-Pillar-Two environment. The OECD framework recognises QTIs as part of a set of acceptable tools, subject to substance-based caps and design constraints.
As business models diversify, incentives must also evolve to accommodate different cost structures and investment horizons. A diversified incentive framework allows Singapore to target multiple forms of economic activity – research and development, advanced manufacturing, green technologies, modern services, AI deployment and skills upgrading – each corresponding to key ESR recommendations.
A diversified approach will also provide optionality, allowing incentives to be better targeted, more predictable and less distortive, while remaining compatible with global minimum tax expectations.
Crucially, it supports broader strategic priorities including entrepreneurship, talent development and inclusive growth.
Beyond compliance: positioning for global competitiveness
Singapore’s challenge has never been about meeting global minimum tax requirements, but about signalling the right economic behaviours. In a world where tax outcomes are increasingly standardised, incentives compete on clarity, credibility and alignment with real activity.
For businesses making long-term location decisions, the signal matters. Incentives that are clearly structured, consistently administered and anchored in observable activity strengthen business confidence – particularly in an environment where global tax rules are still evolving in practice.
Substance-based incentives reward long-term commitment rather than tax optimisation. They reinforce the principle that investment decisions should be driven by genuine operational considerations, not short-term arbitrage across jurisdictions.
New regional initiatives such as the Johor-Singapore Special Economic Zone further strengthened cross-border connectivity in 2025, helping to attract new global investments and deepening Singapore’s role as a regional hub.
While our neighbours see increased investments, companies are still anchoring in Singapore because of speed to market, talent availability, innovation ecosystems and trusted access to South-east Asia’s high-growth markets.
Ultimately, Singapore’s competitiveness will rest on the alignment, clarity and inclusivity of an overall incentive architecture that supports strategic economic priorities: sectoral transformation, innovation leadership, global connectivity, AI adoption, quality job creation and workforce resilience.
The writers are from Deloitte Singapore. Yvaine Gan is global investment and innovation incentives leader, and Eugene Penafort is global investment and innovation incentives director.
TRENDING NOW
Easy to rent out, hard to sell: Are buyers losing interest in Singapore’s one-bedroom condos?

GovTech retrenches another 38 staff in second round of layoffs
Stocks to watch: Seatrium, CapitaLand Investment, Keppel DC Reit, Suntec Reit, CLCT, TSH Resources

World’s largest offshore wind platform by Seatrium consortium on track to be completed by 2028

