

Tighter HDB loan limit will cool resale flat prices; choice units should still see firm demand
The tighter loan limit makes for prudent borrowing, which is sensible in a job market prone to disruptions
INCREASINGLY, an adage of Singapore’s housing market is that when prices rise strongly, the government will quickly intervene to cool things.
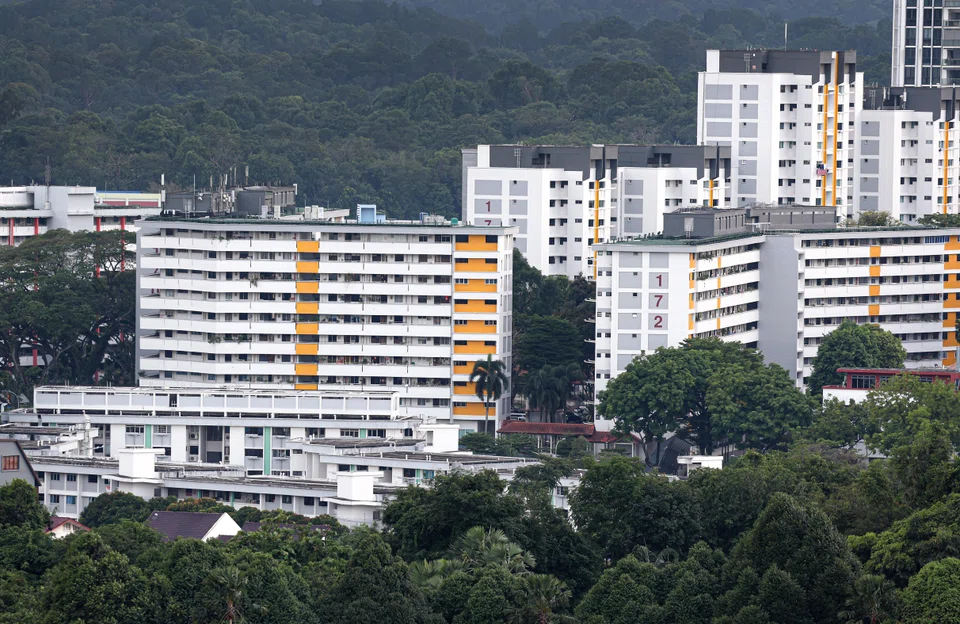
The latest round of property cooling measures zeroed in on the Housing and Development Board (HDB) market, where resale flat prices have lately been growing much faster than private home prices.
In the second quarter of 2024, the HDB resale price index rose 2.3 per cent from the previous quarter. The index was up 4.2 per cent from Q4 2023 and 6.6 per cent year on year (yoy).
Meanwhile, the Urban Redevelopment Authority’s property price index for residential properties in Q2 rose 0.9 per cent quarter on quarter, 2.3 per cent versus Q4 2023, and 6 per cent yoy.
Effective from 12 am on Aug 20, the loan-to-value (LTV) limit for HDB loans was lowered from 80 per cent to 75 per cent. The 75 per cent limit is similar to the LTV limit for home loans granted by financial institutions. For a home valued at S$750,000, a lower LTV of 75 per cent (versus 80 per cent) reduces the maximum loan amount by S$37,500 to S$562,500.
Eligible lower to middle-income first-time homebuyers will be less affected by the lower LTV limit for HDB loans, since they will receive a higher means-tested Enhanced CPF Housing Grant when buying new and resale flats. The increase in grants is progressive. Eligible families and joint singles with an average monthly household income of up to S$1,500 get the largest increase of S$40,000.
The latest move to cool the HDB resale flat market should be viewed largely as a pre-emptive one. After all, eight in 10 first-timer families who collected the keys to their resale flats in 2023 used 25 per cent or less of their monthly household income to service their HDB housing loan.
Adverse impact
The lower LTV limit for HDB loans will likely blunt the momentum in the HDB resale flat market.
One, some buyers will see their buying power curtailed. Sure, many buyers may not borrow up to the LTV limit or the maximum loan duration. Still, there are some buyers who want to max out the home-loan quantum and duration in order to get a particular dream unit or to buy as pricey a home as possible in the hope of profit maximisation.
Two, buying sentiment in the HDB resale flat market will be dented. Some buyers may adopt a wait-and-see attitude to assess the impact the lower LTV on HDB loans has on the resale market. Many HDB resale flat buyers may proceed with heightened caution, given this reminder that the government can and will intervene to help ensure stability in housing prices.
At the margins, weaker homebuying sentiment for HDB resale flats can affect buying sentiment in new suburban condos, as many potential buyers in this segment might be hoping to fund their condo purchases substantially from selling their HDB homes for a good price.
Underlying support
However, the resale market for HDB flats should continue to receive strong support from various groups of buyers. Some buyers who can buy subsidised HDB Build-To-Order (BTO) units may still go for HDB resale homes, for the shorter waiting time or their preference for a unit in a highly specific location.
Also, many homebuyers focus on HDB resale flats because they are ineligible to buy BTO units or are restricted to buying smaller BTO flats.
For example, those who buy HDB four-room and five-room units in the resale market and bypass the BTO market include couples comprising two Singapore citizens; a citizen and a Singapore permanent resident (PR) who bust the income ceiling to buy BTO homes; PR households whose applicants and core occupiers have had PR status for at least three years; and single citizens aged 35 years and older.
Sales of HDB resale homes in sought-after locations that fetch over a million dollars each or, in several cases, over S$1.5 million dollars each, capture the headlines. While such transactions account for a small fraction of total resale flat deals, they may cause homebuyers to fret over housing affordability.
Expect continued positive momentum in the sub-segment of much sought-after HDB resale homes. These homes can be great for living, and are far cheaper than the new or resale leasehold condominiums nearby.
Also, as the population ages, many local private home owners may happily trade an owner-occupied private home for a choice HDB resale home, thereby freeing up funds for their retirement and lowering recurring property-related expenses. In 2023, 787,167 Singapore citizens were aged between 55 and 69 years old, accounting for about 22 per cent of the citizen population.
Prudent borrowing
Access to sizeable home loans is important for young couples starting on their home-ownership journey, especially those who do not have large amounts of savings or receive financial help from parents.
Still, the recent trend of lower LTV limit for HDB loans makes sense as the job market may be increasingly prone to much disruption. Before this latest change, the LTV limit was lowered from 90 per cent to 85 per cent in December 2021, and then reduced to 80 per cent in September 2022.
Being forced to borrow less can be a blessing when a homeowner loses a job or enrols in a full-time course to retrain for other career opportunities. Also, a homeowner may need to take substantial time off from full-time employment to care for young children or elderly parents.
Ultimately, HDB’s continued push to build more BTO homes, including in choice locations, will be critical to meeting the housing aspirations of many young locals, as well as keeping HDB resale flat prices in check.
TRENDING NOW

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Income Insurance appoints former Manulife Singapore top man as new CEO

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

