Time for CICT to press on with divestments
Bukit Panjang Plaza, 21 Collyer Quay and Citadines Raffles Place present opportunities for the Reit to unlock value and redeploy proceeds to better use
SOME observers in property circles have noted that CapitaLand Integrated Commercial Trust (CICT) seems to be in a hurry to divest some assets.
Last week, The Business Times reported that an expression-of-interest (EOI) exercise closed in the fourth quarter of 2023 for the 299-unit Citadines Raffles Place, which is in the CapitaSpring building at Market Street that was completed a couple of years ago.
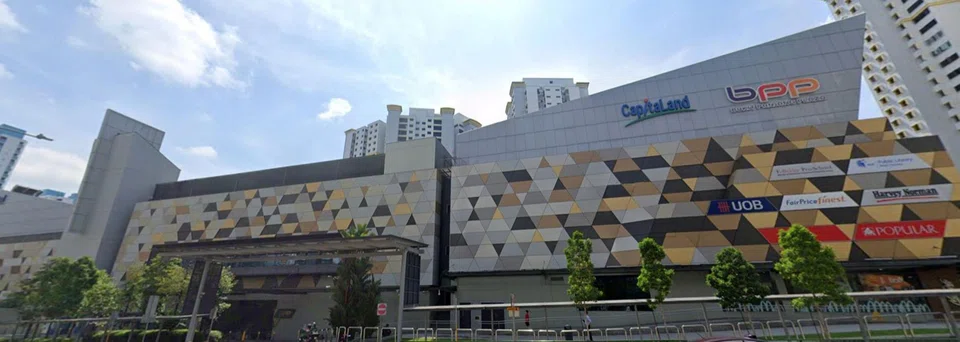
Now, word in the market is that a separate low-key EOI exercise is set to close next week for Bukit Panjang Plaza, a suburban mall which the real estate investment trust (Reit) has held for some time.
“Last year, there was buying interest for 21 Collyer Quay at S$3,600 to S$3,700 psf on net lettable area.”
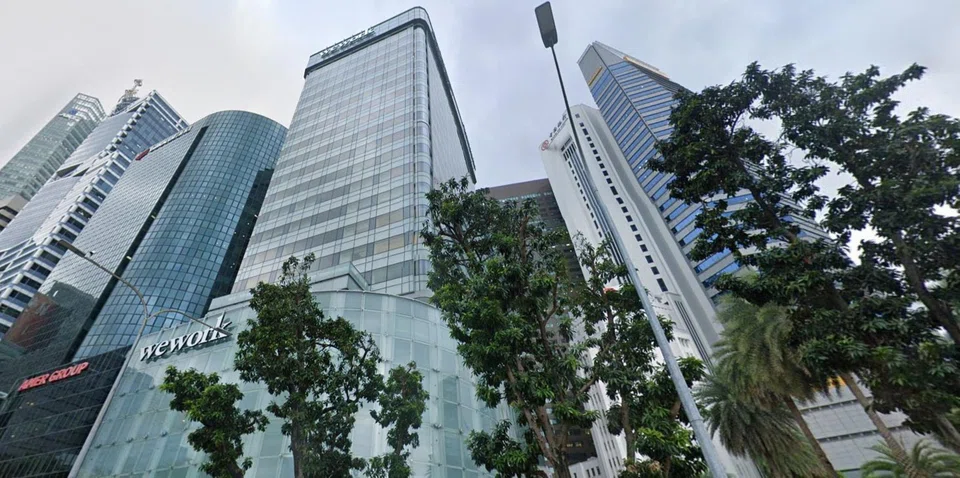
BT also understands that late last year, CICT received interest in the 21 Collyer Quay office building, which some describe as a trophy asset, for its prime location with unblocked views of Marina Bay and a coveted 999-year leasehold land tenure.
In the case of Citadines Raffles Place, a decision to sell makes strategic sense, since serviced apartments are not CICT’s forte.
Bukit Panjang Plaza and 21 Collyer Quay were acquired by the former CapitaMall Trust (CMT) and CapitaCommercial Trust (CCT) respectively, way before they were renamed and later merged in late 2020 to form CICT.
Singapore’s largest Reit may have decided it has optimised these assets. Presented with a chance to exit these investments at handsome prices significantly above the latest valuations, CICT stands to unlock value and be able to put sale proceeds to better use – if it seizes the opportunity at the right time.
“Rather than bear all this uncertainty and risk, CICT may take the opportunity to divest 21 Collyer Road at a premium to valuation.”
For a start, given the current high-interest-rate environment, the Reit could use a chunk of divestment proceeds to reduce debt.
CICT’s aggregate leverage stood at 40.8 per cent as at Sep 30, 2023. This is slightly lower than the 41.2 per cent as at Sep 30, 2022, though some analysts still consider the current gearing relatively high, and would like to see it brought below 40 per cent.
Drop in interest coverage ratio
The Reit’s interest coverage ratio – that is, the ratio of earnings to interest expenses – has declined steadily from 3.9 times as at Sep 30, 2022 to 3.1 times as at Sep 30, 2023.
A closer look at the three properties gives a sense of the scale of sale proceeds that could be released if they are divested.
CICT holds a 45 per cent interest in a joint venture that owns the Citadines Raffles Place. CapitaLand Development owns 45 per cent, and Mitsubishi Estate Co, the remaining 10 per cent.
The CapitaSpring building, in which the serviced residence is located, is on a site with a 99-year leasehold tenure that began on Feb 1, 1982, leaving about 57 years on the lease. Parties are understood to have expressed interest, but a buyer has yet to be identified. Market watchers expect the owner’s asking price to be at least S$1 million per room.
Bukit Panjang Plaza is on a site with a 99-year leasehold tenure from Dec 1, 1994, so there are nearly 70 years left on the lease. The shopping centre is near the Bukit Panjang bus interchange and MRT/LRT stations.
As at Dec 31, 2022, the property was valued at S$344 million, with a 4.8 per cent capitalisation rate. Based on a net lettable area (NLA) of 163,998 sq ft, the valuation would work out to about S$2,098 per square foot (psf).
Tenants in the four-storey mall include FairPrice Finest supermarket, Harvey Norman, Gadget Hub and Kopitiam.
The asking price for the ongoing EOI exercise of Bukit Panjang Plaza, being conducted by JLL, is said to be about S$470 million.
CICT had acquired it in two stages, in 2003 and 2007. It has completed significant asset enhancement works on this asset over the years, and perhaps does not see further value-add potential in the near future. Competition for shoppers and patrons at this retail property became stiffer following the opening of the neighbouring Hillion Mall in 2017.
Late last year, a few agents were quietly sussing out demand for 21 Collyer Quay. Talk in the market was that there was some potential buying interest in the range of S$3,600 to S$3,700 psf on its NLA.
However, CICT is said to be eyeing a higher price of S$3,900 to S$4,000 psf, translating to between S$830 million and S$852 million. As at Dec 31, 2022, the building was valued at S$634 million, based on 3.45 per cent cap rate. The valuation worked out to S$2,977 psf on an NLA of 213,000 sq ft.
The 21-storey building is fully leased to WeWork.
CICT acquired the property in 2005 from HSBC under a sale-and-leaseback arrangement. Ahead of HSBC’s lease expiry in April 2020, CICT found WeWork as the replacement tenant. The flexible workspace provider’s seven-year lease began in December 2021, following a S$45 million renovation of the building.
Analysts say that 21 Collyer Quay’s development potential has been fully tapped. The building’s existing gross floor area slightly exceeds the maximum allowed based on the 15.0 plot ratio designated for the commercial-zoned site under the Urban Redevelopment Authority’s latest Master Plan.
So far, WeWork has been reported to be on time with its rent to its landlords in Singapore, notwithstanding its US parent having filed for Chapter 11 bankruptcy protection in November 2023.
Observers say that if WeWork exits the building, CICT should still be able to find a replacement flexible space operator to whom it could lease 21 Collyer Quay. However, the Reit stands to extract higher rents by finding multiple tenants in the building. For that, it may have to incur expenditure to renovate the property again, this time to re-adapt the building to suit typical end-user office tenants.
Call option at CapitaSpring
Rather than bear all this uncertainty and risk, CICT may take the opportunity to divest 21 Collyer Road at a premium to valuation. No doubt, the property’s 999-year leasehold tenure is an attraction, but the trust does not really need this. CICT could plough the sale proceeds into CapitaSpring, where it is still within a five-year call option period to acquire its partners’ stakes in the commercial component of about 673,000 sq ft in the building. On an as-is basis, office rents in the newly-built CapitaSpring would be higher than in 21 Collyer Quay.
Factoring CapitaSpring’s shorter land tenure into the price, CICT should be able to extract a higher net property yield by taking full ownership of the offices/workspace and retail space in the building, while exiting 21 Collyer Quay at a lower property yield.
If the above pans out, CICT would have executed one of the classic strategies of a Reit – switching from a lower-yielding asset to a higher-yield one.