Unbridled innovation: a rude awakening for Singapore’s banks?
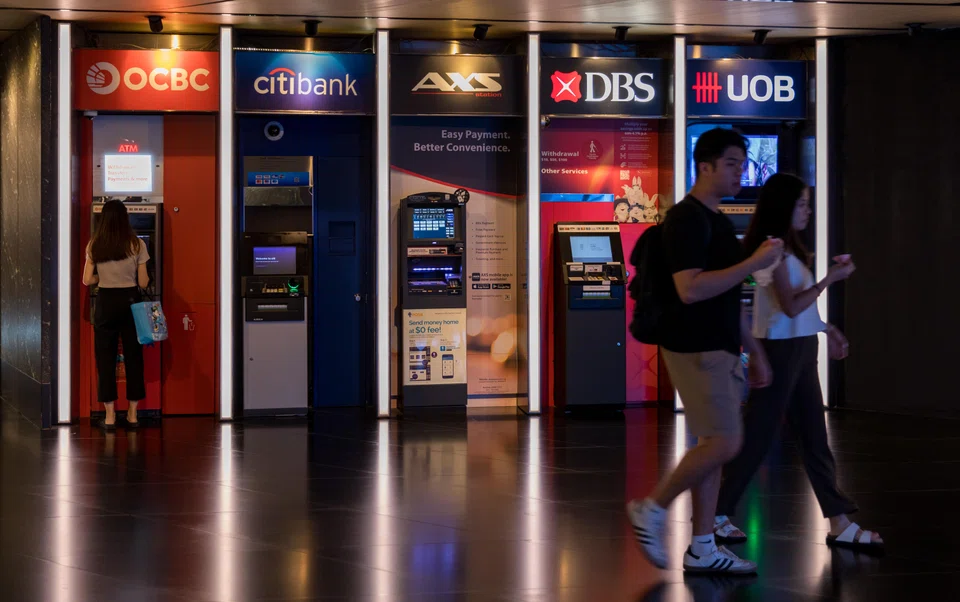
OVER the past few months, something strange and unsettling has unfolded in Singapore. In a nation renowned for its bustling shopping scene and cutting-edge technological prowess, there have been several instances where the simplest of purchases, such as buying a carton of milk, could not be made without resorting to traditional, old-fashioned paper money. This unusual scenario is likely a manifestation of a deeper issue within the country’s banking sector.
One episode of widespread unavailability of digital banking and ATM services in May, not the first, saw the Monetary Authority of Singapore impose an additional capital requirement on DBS – a harsh punishment at the time. Another, more recent, episode saw DBS and Citibank outages in mid-October, apparently due to data centre backup failures, causing significant disruptions that were initially dismissed as anomalies.
These events were soon followed by a string of similar problems at other major banks, including a Nets outage in early November, UOB’s Internet and mobile disruptions, and an OCBC disruption, all happening within the span of just a few weeks. This pattern of failures brings to mind the saying “Once is an accident, twice is a coincidence, three times is a pattern”. Clearly, these do not appear to be mere coincidences but seem to be indicators of a systemic issue.
While no IT system is infallible, software bugs and technical glitches do not really support the frequency of these outages. So the crux of the matter seems more likely to lie in the sector’s unbridled race towards innovation at all costs.
For the longest time, the key word in the banking industry was “stability” and “don’t rock the boat” – something that seems very much applicable today. Perhaps in an effort to keep pace with the rapidly evolving fintech space, it appears that traditional banks might be prioritising speed and novelty over the foundational elements of their operations.
Castles built on sand?
A friend who supplies artificial intelligence (AI) technology to one of the top local banks shared his thoughts with me. He expressed shock at the chaos within the bank. Critical functions were being externalised, coordination was chaotic, and there was a general sense of attempting too much, too quickly. All of this was happening with insufficient structure and leadership.
Having worked at Nokia, I experienced first-hand how a company’s commitment to a tech philosophy ultimately led to its demise. Having built its success on developing the right technological approach for growing markets, it failed to adapt when markets matured… and insisting on its approach cost it dearly.
The financial service sector in general is undoubtedly going through an accelerated dramatic change. For Singapore banks, being a hub in the region adds pressure, to show and lead the way in the growth and improvement of banking services. But it seems that we have forgotten that there can be such a thing as going “too fast”.
For incumbents, innovation is not as easy as it is for the so-called “neo banks” (like Revolut or Wise) or the multitude of fintech startups around (like robo-advisers). They do not have a heritage system, and so they simply buy the latest tech and operate from that base.
Incumbents such as DBS, UOB and OCBC typically have legacy IT systems and, even worse, they probably also have had to integrate acquisitions made along the way – for example, when DBS acquired POSB in 1998 – that had their own IT systems.
So, innovating for incumbents would typically mean having to find compromises. An innovation like Nets might not be running on the same code as your bank accounting software, which in turn could be running on a different code to PayNow… you get the picture?
The incidents we have seen of late are likely to only increase, not decrease, because it seems plausible that “creaky systems” and new systems are being held together with chewing gum, creating opportunity for disaster.
Add to this all kinds of cyber threats and it is not looking good.
The “move fast and break things” Silicon Valley philosophy, while a mantra that seems to rule in the startup world, can have severe repercussions in the banking sector. For institutions that millions rely upon for their daily transactions and financial well-being, the unintended consequences of this approach can be far-reaching and devastating.
An effective innovation framework for traditional banks
The central issue is – you are no longer a financial services company. You are now a tech company that operates in the financial service market.
Becoming a tech company brings expectations of constant innovation and pushing boundaries that are often hard to balance with the “conservative” mindset that we expect of people who are responsible for ensuring the stability and safety of our financial assets.
This means that incumbent banks will need to adopt an innovation framework, some kind of structure to manage their innovation process, ensuring that the journey from idea to execution is managed properly. Leadership and management coordination will also need to step up, because being a tech company that operates in the financial service market means delivering on the expectations of the possibilities of tech while being accountable for regulatory constraints that ensure the viability of the entire financial system. So the balancing act is inevitably a difficult one.
Rather than doing “innovation on the fly”, going with AI or whatever is the latest flavour of the month in the tech world, banks need to ensure they manage (innovation) risk appropriately and create the conditions for success.
There is no need to reinvent the wheel here, as any consumer goods company can attest: they have had to manage innovation for decades and have become good at managing the process (not necessarily the outcome!).
Being clear about managing innovation allows you to have a structured way to approach opportunities and get those opportunities to market, be they incremental or breakthrough.
It will be painful at first. Not least because banks do not typically work in a cross-functional manner, and this is at the heart of a successful innovation management framework.
Design thinking is a great tool to create ideas, apps and more, but it is not a way to manage innovation. Banks seem to be mostly limited to this tool and are missing many other ways to drive and manage innovation, from creative crowdsourcing, to outside-in thinking and conditional functional incubation… there is a lot that can help that is not being done.
In the past, innovation was not a key driver in banking. So this adaptation will naturally take effort.
But it also needs careful planning and managing, so as to ensure that the fundamentals of our financial services remain solid, while they lead the way in innovating the future of the sector with Singapore as a lighthouse in the region.
The writer is co-founder and managing partner of Flying Fish Lab