

An uphill climb for CPF’s glide-path portfolios, but digital platform defies odds
Endowus’ success in weaning members off their love for cash deposits offers hope for the upcoming funds
[SINGAPORE] Life-cycle portfolios that use a glide-path mechanism, in which the risk exposure dials down as you near retirement, is a sensible, well-established approach to pre-retirement investing.
In the US, this class of assets – also called target-date strategies – grew by 20 per cent in 2025, hitting US$4.8 trillion due to buoyant equity markets.
Investment research company Morningstar noted that target-date strategies in the US have grown at a compounded rate of nearly 12 per cent annualised over the past 10 years, reflecting asset-price appreciation and steady plan contributions.
What are the chances that the Central Provident Fund’s planned glide-path portfolios, which work on a similar principle as target-date strategies, could take off in the long run?
In my view, even with an increasingly savvy and investment-aware population, the new portfolios, expected to roll out in 2028, may face an uphill climb.
I think there are, at the outset, two big hurdles. One is CPF members’ love for an assured or guaranteed return.
They get this in the 2.5 and 4 per cent interest rates for the Ordinary Account (OA) and Special Account (SA), respectively.
The second, which relates to the first, is the success of the CPF itself as a pension system, and the deep well of trust it has earned among members in its ability to deliver benefits, not just in the assured interest rates, but also in the flexibility to use the funds for purposes other than retirement savings.
We love the flexibility that CPF offers.
But for the upcoming glide-path portfolios and their managers, this flexibility is a double-edged sword.
Clinging to cash
On the one hand, there is a substantial sum in total CPF balances of S$677 billion as at end-March 2026, of which investments using OA and SA funds account for S$21.2 billion.
On the other, however, members may well prefer to keep their CPF accounts as their low-risk allocation, never mind that the OA rate barely keeps up with inflation and does not provide the growth needed for future retirement adequacy.
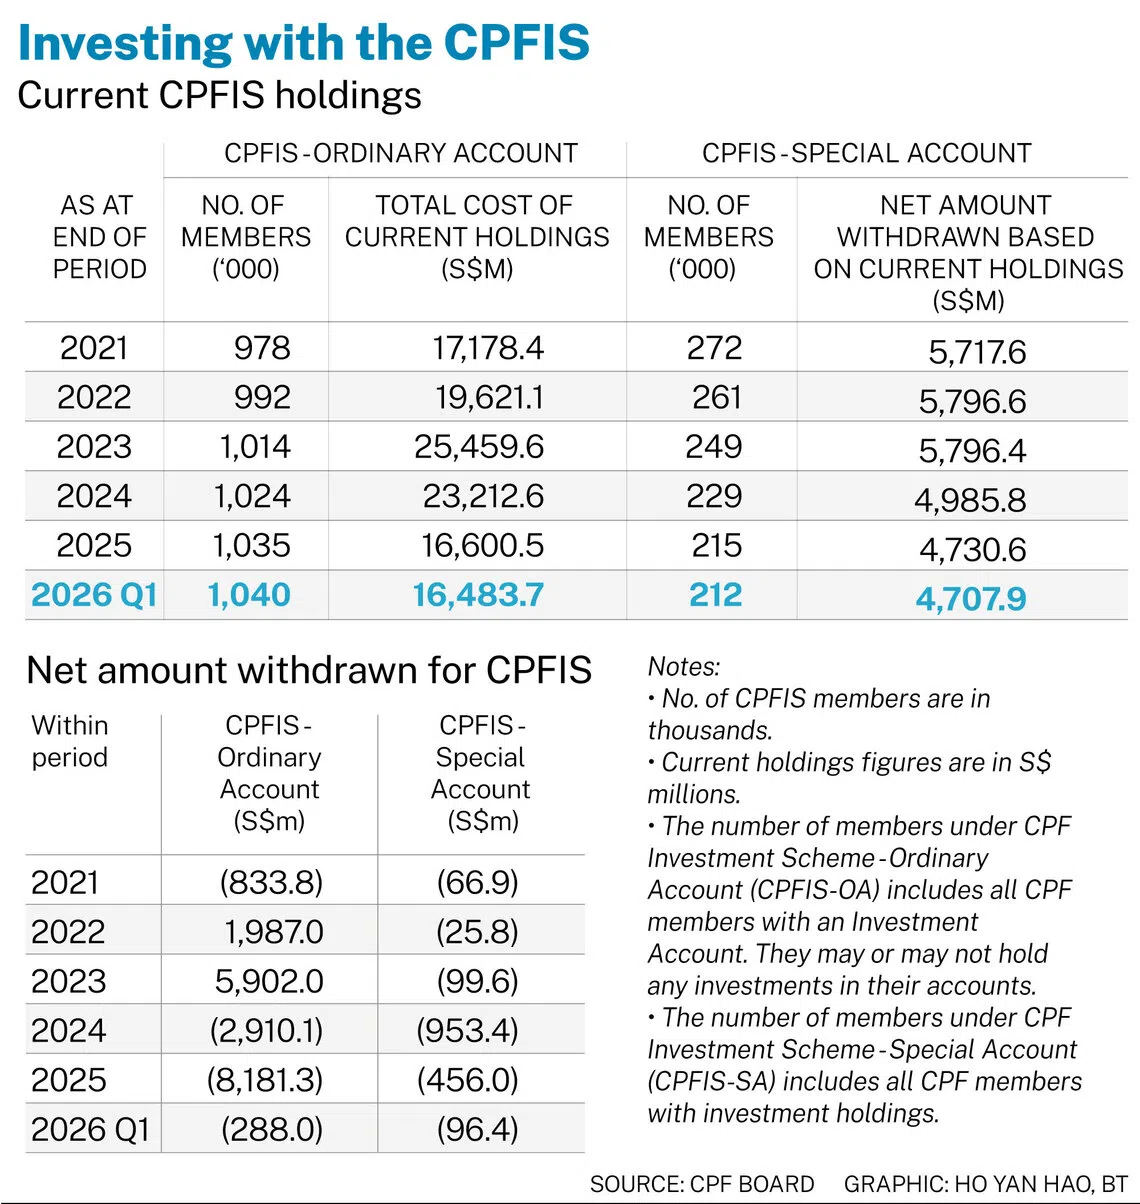
So far, CPF Investment Scheme (CPFIS) statistics are not encouraging.
The value of current holdings in the CPFIS OA shrank to S$16.48 billion at the end of the first quarter, a decline of 35 per cent from the peak of S$25.45 billion in 2023.
In terms of the net amount withdrawn for investment, the amounts were negative between 2024 and Q1 2026.
Endowus chairman and group chief investment officer Samuel Rhee has an explanation for the shrinkage in the value of current holdings in the CPFIS.
The peak value of S$25.45 billion in 2023 was due to members using their CPF savings to invest in six-month Treasury bills (T-bills), he said.
Recall that the T-bill yields peaked at end-2022 at more than 4 per cent. By early 2023, this had declined to an average of 3.77 per cent, still a significant margin above the OA rate.
T-bill rates have since declined; today, they hover at around 1.55 per cent.
The Singapore Department of Statistics data on Singapore’s household balance sheet bears out the distinct preference for cash and a low allocation to equities.
Of the S$2.14 million in household financial assets at the end of the first quarter, cash had the largest share at 33 per cent, followed by the CPF at 31.5 per cent, and life insurance at 15 per cent. Unit trusts’ share was around 10 per cent and listed securities, 7 per cent.
Defying the odds
But Endowus’ success in weaning members off their love for cash deposits defies the odds and surely offers hope for the upcoming glide-path funds.
In the seven years since the company was onboarded as a digital wealth adviser for the CPFIS, the proportion of members investing regularly has risen.
Rhee said the company has seen record pace of CPFIS investments in 2025 and year to date.
This is despite the overall CPFIS data reflecting negative values in terms of net amounts withdrawn for investment in the same period.
In fact, the surprise is also Endowus’ experience in the proportion of regular investments by CPF members.
Forty-three per cent of its CPF clients make recurring investments, higher than 32 per cent for cash and 24 per cent for the Supplementary Retirement Scheme.
Rhee said: “We have never had a monthly or even weekly net outflow in regular CPF investing in the seven years that we have been the digital adviser for CPFIS. This is a rare feat in any wealth and investing service, and we believe it shows the importance of education and advice.
“It’s because we onboarded them for the right reasons, with the right expectations. We educate and convert them… the advice must be in the context of your total wealth and financial planning for retirement.
“All these things are critical for the success of (the new CPF glide-path portfolios). I do worry as well that people won’t take them up as much or as quickly.”
Endowus currently has total client assets of S$17 billion under administration.
Its experience shows a segment of CPF savers is committed to regular investing for retirement.
This segment has the potential to grow. But it also underscores the critical need for advice, if the new portfolios are to gain traction.
Young savers confront multiple cash outflow needs, the largest of which is their home purchase. Drawing from the CPF to fund the necessary down payment, as well as monthly mortgage payments, is likely to derail any monthly investment commitment.
Investor education on the merits of long-term investing has to be consistent – in terms of illustrating the savings gap members may have in their retirement goals; the impact of a property purchase and the trade-offs arising from using CPF funds; and of course the benefits of staying invested and investing regularly.
Even here, Endowus’ track record demonstrates that staying invested can yield returns above the OA rate.
In 2025, 94 per cent of its CPF clients beat the OA’s 2.5 per cent hurdle, higher than the CPFIS average of 85 per cent.
Between January 2020 and December 2025, 90 per cent beat the OA rate, exceeding the CPFIS average of 65 per cent.
The lower expense ratios of Endowus’ funds may partly explain the differential.
The new glide-path portfolios may not take off with an immediate bang. But investor education on the rewards of regular investing in the long term – against the risk of holding too much in cash – will surely give it a good head start. Those efforts should start now.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Singapore judge raises doubts iron ore trader Radiant World is owed US$1 billion

