

What’s next for Singapore digital banks in 2025 in quest for profitability
Digital banks have benefited from higher interest rates, but the next step – engaging customers – will be harder
THE high interest rate environment has been a boon for digital banks in Singapore, enabling them to sustain higher promotional rates for customers although all three have yet to turn profitable.
While costs have led all three digital banks – GXS, MariBank and Trust – to remain in the red, the relatively high promotional rates were sustained for longer than digital bank counterparts in other countries.
For instance, MariBank has kept its interest rates at 2.7 per cent through 2024, cutting it to 2.5 per cent on Jan 1 this year. In comparison, digital banks in Hong Kong only offered the higher promotional rates to a small group of customers for six months, whereas all three digital banks here have offered the higher promotional rate to all customers without a time limit.
All three digital banks saw improvements in net interest income. Sea’s MariBank generated net interest income in 2023 compared with an expense in 2022, while GXS (backed by Grab and Singtel) and Trust (backed by Standard Chartered and FairPrice Group) saw net interest income increase by about six times.
“This was the first time in history in which digital banks can attract customers and still have healthy net interest margins,” Alexander Pariyskiy, associate partner at consultancy McKinsey, told The Business Times.
The digital banks have done the first step right in getting customers on board, with GXS and MariBank getting the deposit cap lifted by the regulator to allow more customers to come on board in 2024. However the next phase is more tricky – getting customers to stay engaged and use their digital bank accounts for daily transactions.
Report card
The digital banks themselves are riding off the high of 2024, when a growing deposit base enabled all three to launch loan products for their customers.
Deposits at Trust, for instance, hit S$3 billion as at June 2024, with customer loans and advances standing at S$486 million. The bank’s CEO, Dwaipayan Sadhu, says that over 16 per cent of Singapore’s adult population is a Trust customer. The bank is on track to become the city-state’s fourth-largest retail bank by customer numbers by end-2024.
Neither MariBank nor its parent company Sea discloses how much it has in loans or deposits, but the bank says that it has worked on product solutions to lower barriers to accessing financial services for retail and small-and-medium-enterprise (SME) customers.
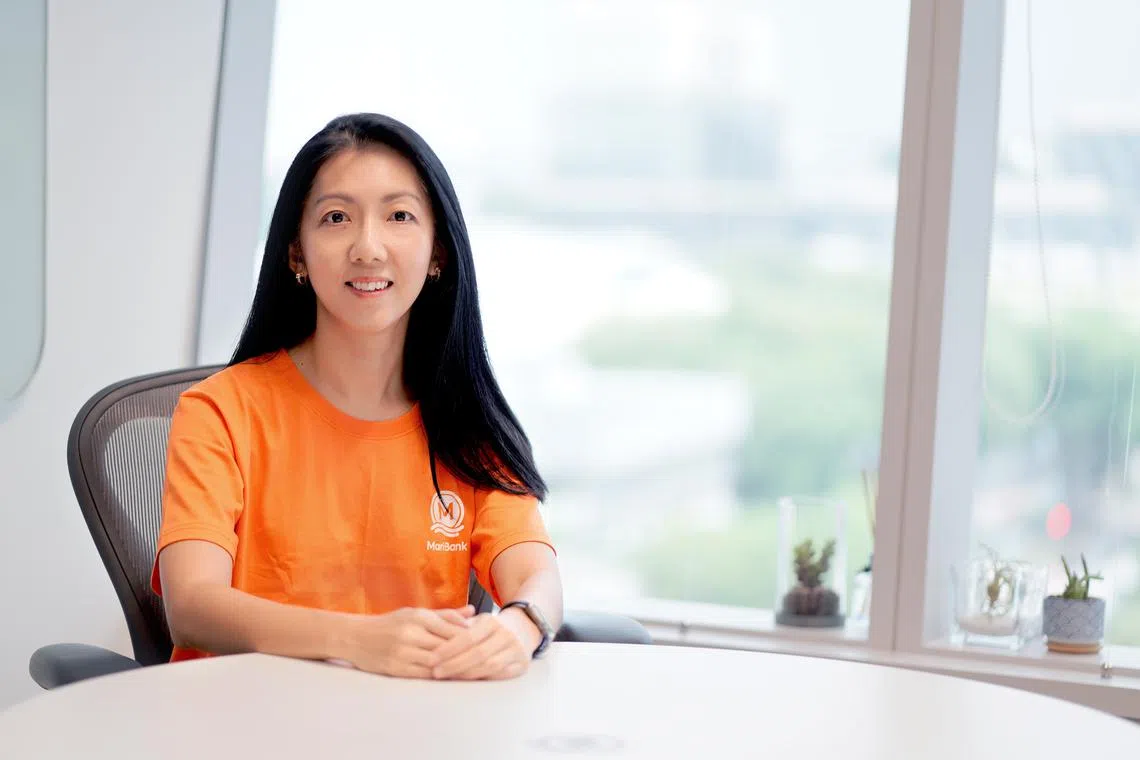
“The new offerings and service enhancements we introduced last year were all designed based on our customers’ feedback,” says Natalie Goh, CEO, MariBank Singapore. These include Mari Invest, an investment product that primarily buys into the Monetary Authority of Singapore’s paper.
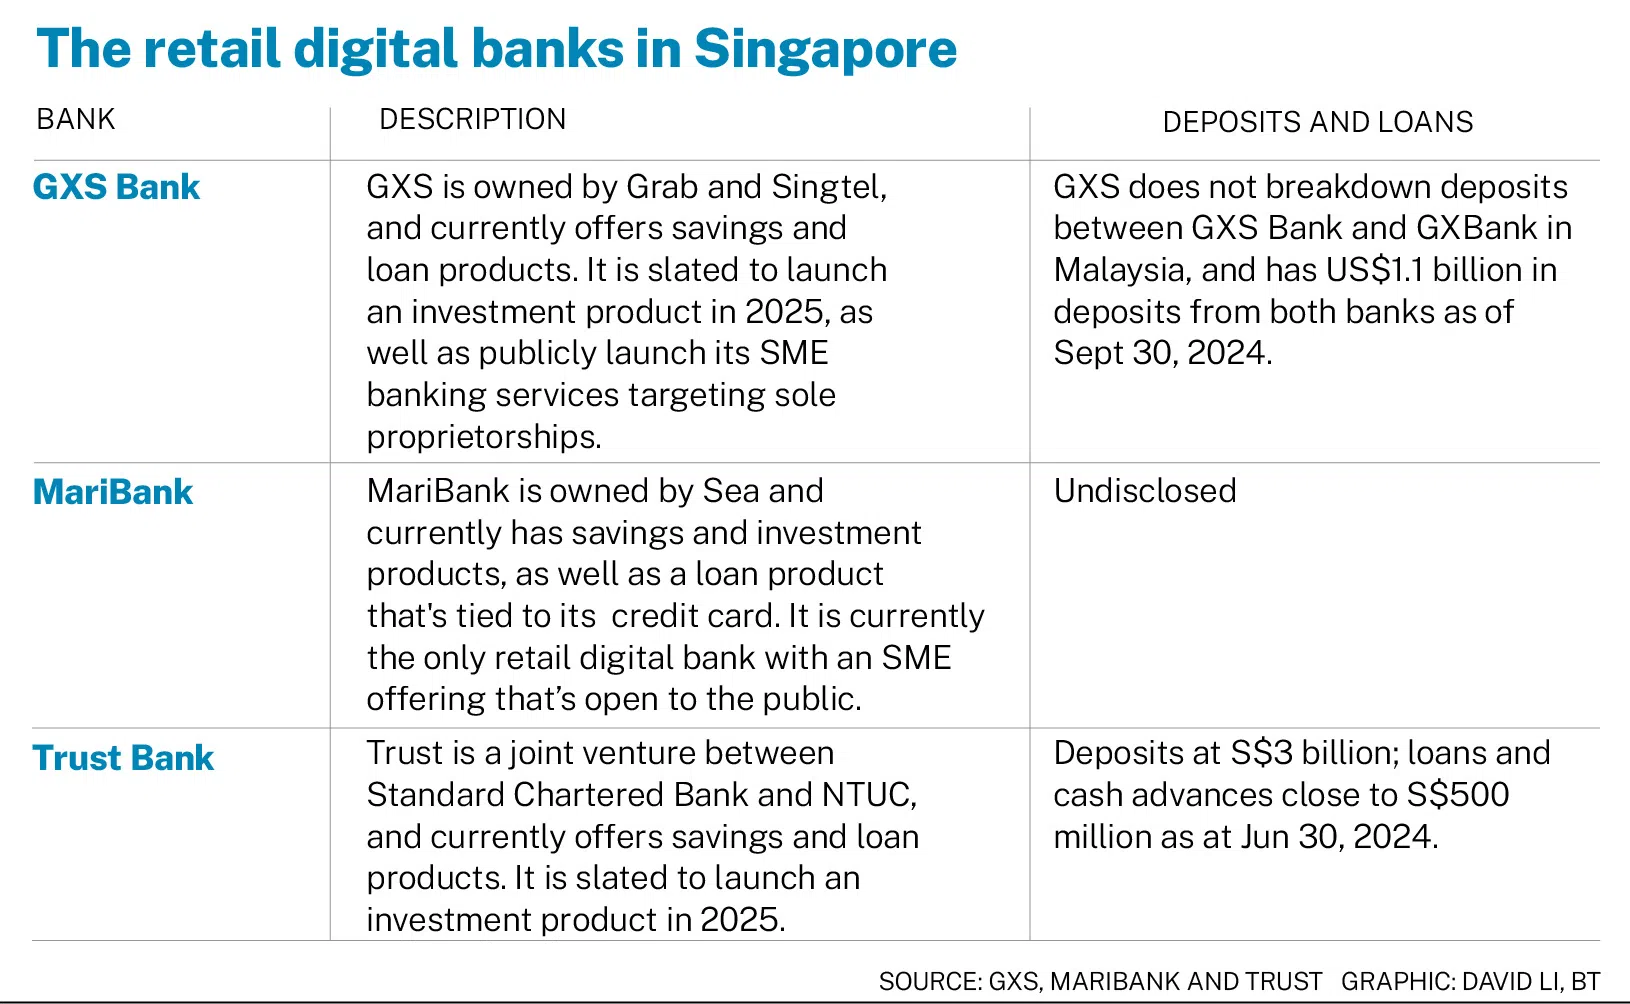
At GXS, the combined deposits of GXS and GX Bank in Malaysia have crossed US$1.1 billion as of Sept 30 2024. For GXS, a major theme for 2024 has been the growth of deposits, even as interest rates have started to come off.
“We’ve had fairly consistent growth in deposit balance over the year rather than seeing fluctuations based on interest rates, and while we’ve adjusted our interest rates, we still remain attractive for savers,” says Muthukrishnan Ramaswami, CEO of GXS.
Data and utility
So far, digital banks have mirrored traditional banks in terms of their product offerings, with savings, loan and investment products. But what would be an edge for these digital banks is the appropriate data to glean insights into what their customers would use.
The promise of digital banks is the data they have on their customers collated from their ecosystems. For GXS, it is the data its parent companies Grab and Singtel have, and for MariBank, it’s the data that parent company Sea has from Shopee and Garena. Trust would likely have access to data from parent companies Standard Chartered Bank and Fairprice Group.
“I think what’s especially going to be a game changer is data as an asset,” says Avishek Nandy, head of financial services practice at consultancy Bain.
The combination of data and artificial intelligence (AI) can help break the silos between product offerings, creating solutions catering to individuals based on their saving, spending and investing habits. Currently, traditional banks do not generally offer such solutions to customers below the affluent bracket.
These efforts will be key as digital banks compete to become the primary bank for their customers in Singapore. High interest rates are coming off as the Federal Reserve has slashed rates in the past few months, with a few more rate cuts likely on the way.
Indonesia’s digital banks found that out the hard way, when promotional rates failed to get customers to switch to using them as their primary banks. The deposits held in the current accounts and savings accounts (Casa) in Indonesia digital banks make up less than 5 per cent of Casa across the country, notes Sumit Kumar, partner at consultancy BCG.
In Singapore, the amendment to the Payment Services Act in Dec 2023 now allows e-wallets in Singapore to hold up to S$20,000, up from S$5,000. Moreover, a report by payment processing company WorldPay states that the country is expected to have e-wallets as drivers for transactions, meaning that competition is rising for digital banks.
“All of that makes us think hard: Will it be easy for a digital bank to become a transaction bank or medium of choice?” says Kumar.
This is a challenge experienced by all three digital banks, which have rolled out sweeteners such as promotional cashback rates or loyalty points for customers to incentivise using their credit cards or payment methods at the till.
“So it’s about how active our customers are, how they’re interacting with us, and how much they are banking with us,” says Ramaswami.
Citing the popularity of GXS’ savings products, where available slots get filled up quickly with customer demand, Ramaswami believes that customer retention is on the deposit accounts side. On the loan front, letting customers repay whenever they want has allowed the bank to obtain data on customers who typically have little to no credit history.
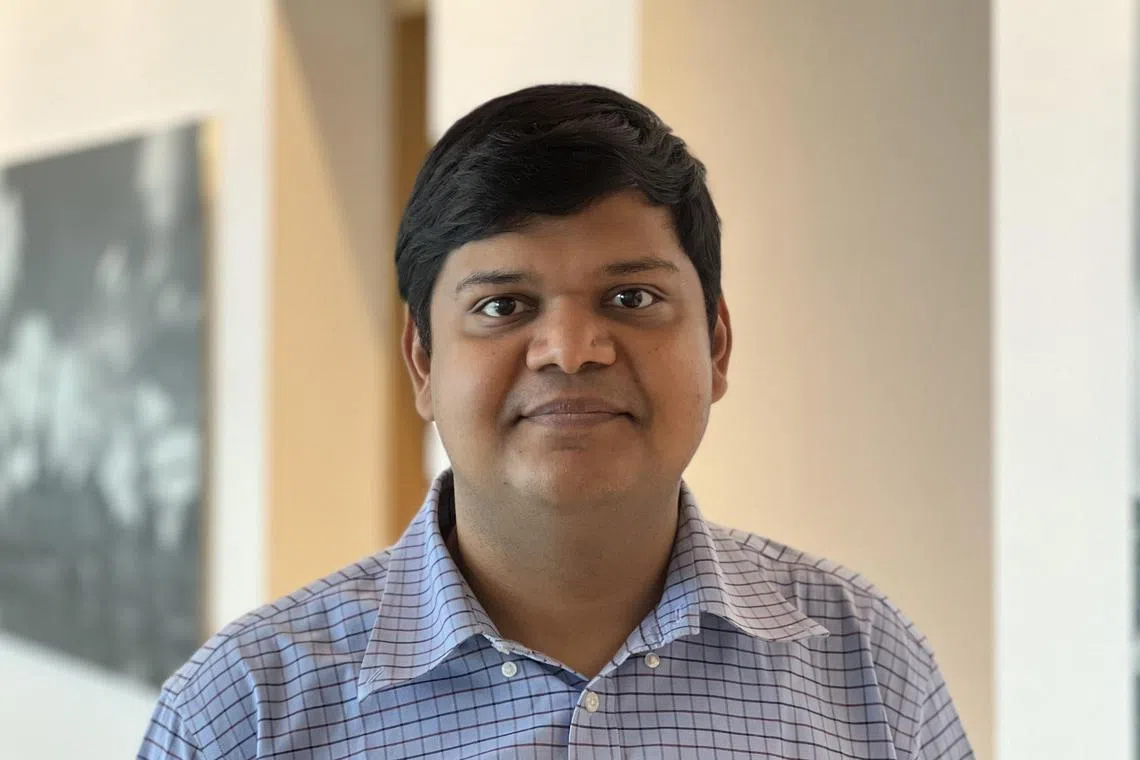
GXS has customers on both ends of the spectrum for its FlexiLoan product, with higher income bracket customers also taking up loans. With these customers, higher loan quantums can be dished out.
“It’s not sustainable to serve only one end of the segment, and it’s the customer segment that falls in between that is attractive to serve, such as consumers with an annual income of between S$50,000 to S$100,000,” says Ramaswami.
As digital banks grapple with both traditional banks and e-wallets, they will need to differentiate themselves with a value proposition that goes beyond banking, notes Bain’s Nandy. From loyalty programmes to insights to help with managing spending and savings, the more holistic the proposition, the focus on the transactional nature of digital banking can be taken away.
Digital banks will need to do what traditional banks do, but differently and locate niches that can be lucrative, notes McKinsey’s Pariyskiy. Be it through better pricing or customer experience, digital banks will need to find their way to compete with the incumbents on their home ground.
“If you manage to build a highly engaged customer base, with trust for a bank way higher than other institutions, you can actually monetise the base by offering products outside of financial services altogether,” he says.
In 2025, digital banks in Singapore are looking to expand their services, building new products and offerings in the wealth and SME space.
New niches
MariBank currently is the only digital bank with a savings, investment and loan product, with GXS and Trust still building out their investment offerings, which are slated for launch in 2025.
MariBank currently has a Mari Invest product, where customers invest into units of the Lion-MariBank SavePlus fund, managed by Lion Global. The fund invests mainly in bills by the Monetary Authority of Singapore and other bond and money market funds.
Both GXS and Trust have kept details of their products under wraps, but it appears that both are gunning for very different segments of the market.
According to research by Trust, the mass and mass affluent segments have been underserved, with customers in these segments mainly keeping money in savings or fixed deposit accounts. These customers find it difficult to invest despite the range of options in the market, says Trust’s Sadhu.
“We saw a significant opportunity in this space and that’s where TrustInvest closes this gap,” he says. The product has yet to be launched.
Meanwhile, GXS has not launched its investment product yet mainly because the underserved segment it is targeting still generally lacks money for investing.
It is likely the product would be more of a fixed-income instrument, which would be low-risk and fairly easy to understand. The key features of the product include being unitised, with no minimum amount, and the ability to be liquidated at any time. GXS is also looking to combine insurance coverage with the investment product as well, says Ramaswami.
“We are not competing in the wealth management sector – this is already well-served with every large retail bank playing in that space. Where we see a gap is in providing access to simple, low-risk and easy-to-understand investment products such as fractional investments, which may be more useful for our customer base,” he says.
In the SME space, digital banks can make a difference, something that the digital wholesale banks – which serve businesses – such as Greenlink Digital Bank and Anext Bank have homed in on. Other non-bank financial institutions such as Revolut and Wise have also ramped up their SME offerings here as well, underscoring the potential seen in the Singapore market.
SMEs are thus also a new target group for GXS, with the digital bank set to launch products and offerings for that market in the first quarter of 2025. Selected sole proprietorships within Grab and Singtel’s ecosystem have been invited and onboarded onto the SME banking offerings, with GXS estimating that one in two sole proprietorships are either part of or served by Grab and Singtel’s ecosystem.
Sole proprietorships and small businesses are the main audience for the SME products, which include a business deposit account with interest, a loan product for working capital, and deals from the Grab and Singtel’s ecosystem. Currently only sole proprietorships can sign up for GXS’ SME banking services.
Trust is keeping mum on whether it will join the other digital banks in courting SMEs with its own suite of banking products and services.
“While we can’t comment on specific segments, there is a huge opportunity for us to create differentiation and bring innovation across the market in Singapore, and we remain focused on where we can make a real difference,” says Sadhu.
“The traditional banks have struggled to treat an SME and an SME owner, the business and the director of the business as one customer, they think of it as two different customers and two different experiences,” says BCG’s Kumar.
New year, new me
Moving into 2025, all three digital banks have outlined different focuses for the year as they build towards profitability.
The big themes for digital banks this year include falling interest rates, the increased use of AI, and building a path to profitability. AI could help drive even more personalisation and create a more interactive human-like experience for customers.
This could be in the form of interactive avatars rather than static landing pages to help close a sale, or using generative AI to cross-sell products, says BCG’s Kumar.
“That could be quite interesting and powerful for people to think of, because for them, efficiency in terms of higher revenue per customer or higher conversion of every dollar you spend and the cost to serve on the servicing side is going to be critical,” he adds.
Falling interest rates could also put a damper on the path to profitability for digital banks here. For some global digital banks, the high interest rates contributed as much as 40 per cent of their revenue, notes McKinsey’s Pariyskiy.
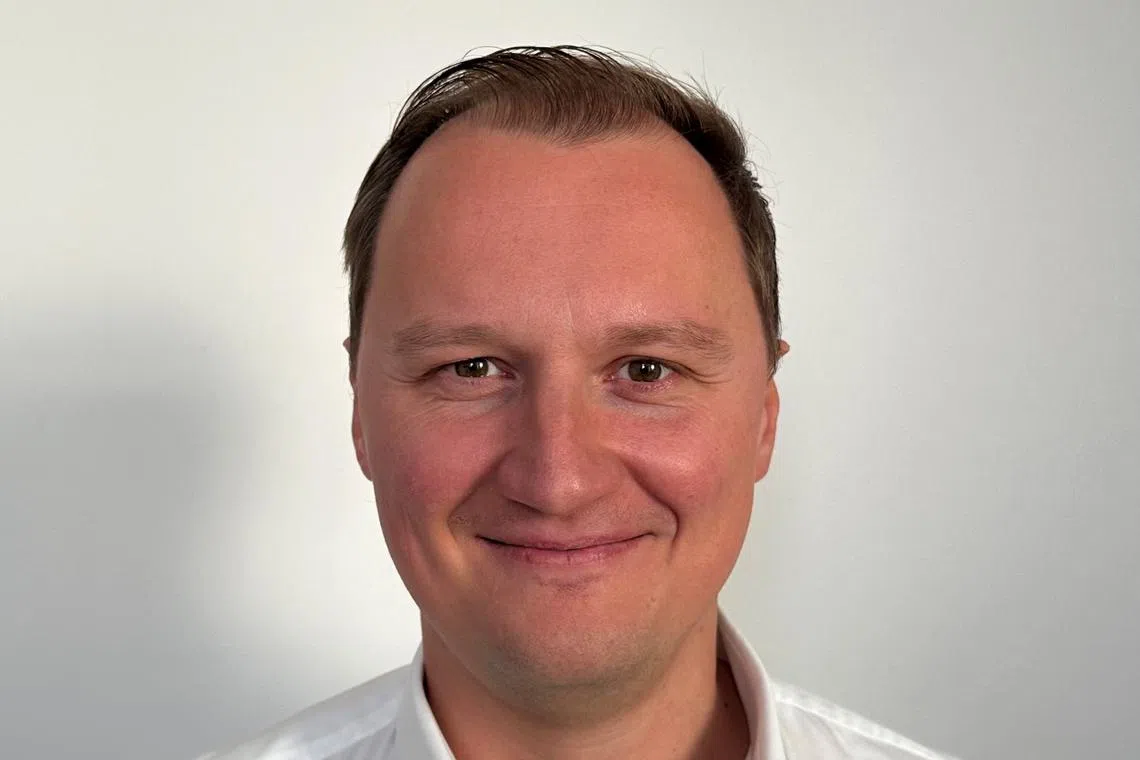
Any substantial fall in interest rates could impact profitability, especially if the digital bank has not built strong revenue generating products.
The digital banks here have set out different priorities for 2025, with growing the customer base a common refrain across all.
“This means continuing our growth, building out our capabilities further and giving our customers even more reasons to use our services more regularly. We are already seeing great progress – for instance, our credit card customers use their cards 21 times on average each month, which is a great start,” says Sadhu.
At MariBank, besides growing the customer base, the digital bank aims to strengthen its deposit and loan portfolios as well as enhance security infrastructure.
“This will be achieved through an expansion of our wealth management and payment capabilities, as well as a progressive roll-out of the personal loan offering,” says Goh.
Besides growing the customer base, GXS will also focus on retaining retail customers as well as growing its SME market. This year will be one of scaling up, but also balancing growth, matching the deposit base with the quantum of loans that the digital bank can dole out as well, notes Ramaswami.
“We’re not likely to have that many big announcements in 2025. The SME business banking is the key initiative for 2025, and we will be focusing on launching that while continuing to grow our retail business,” he says.
Increasing the size of the digital bank’s playing field will be key for 2024, as well as the need to hedge its bets says Pariyskiy. In monetising customers, digital banks here will have to build and finetune products that will appeal to customers and generate revenue as well.
“Differentiate something that others don’t and also optimise internally as well not just to save costs, but also to have sustainable growth,” he adds.






