

Will CNMC Goldmine continue to shine?
There are sharply divergent views on the direction of gold prices; meanwhile, gold mining stocks are now performing better than the precious yellow metal
[SINGAPORE] Back in April, as global markets were reeling from US President Donald Trump’s “Liberation Day” tariffs, this column opined that a little company called CNMC Goldmine might offer respite from the mayhem.
Since then, its shares have shot up 118.8 per cent, versus the Straits Times Index’s (STI) rise of 19.9 per cent. On a year-to-date basis, CNMC has trounced the STI by an even wider margin: it climbed 279.6 per cent, while the STI rose 14.8 per cent.
This strong rally was fuelled by a surge in profitability at CNMC’s mining operations in the Malaysian state of Kelantan. For the first half of 2025, the group reported a 256.1 per cent year-on-year increase in earnings to US$15.8 million, on a 78 per cent rise in revenue to US$52.8 million.
Earnings per share came in at S$0.0518 for the six-month period, versus S$0.0146 for the corresponding period in 2024.
CNMC said that the strong financial performance was driven by a 26 per cent increase in gold production, and a 41.1 per cent surge in its average selling price during the period to US$3,197 per ounce.
On the face of it, there is good reason to expect that CNMC will achieve similarly elevated profitability in H2 2025 and 2026. For one thing, the company completed the expansion of its carbon-in-leach plant in April, which has boosted its processing capacity for gold-bearing ore from 500 tonnes per day to 800 tonnes per day.
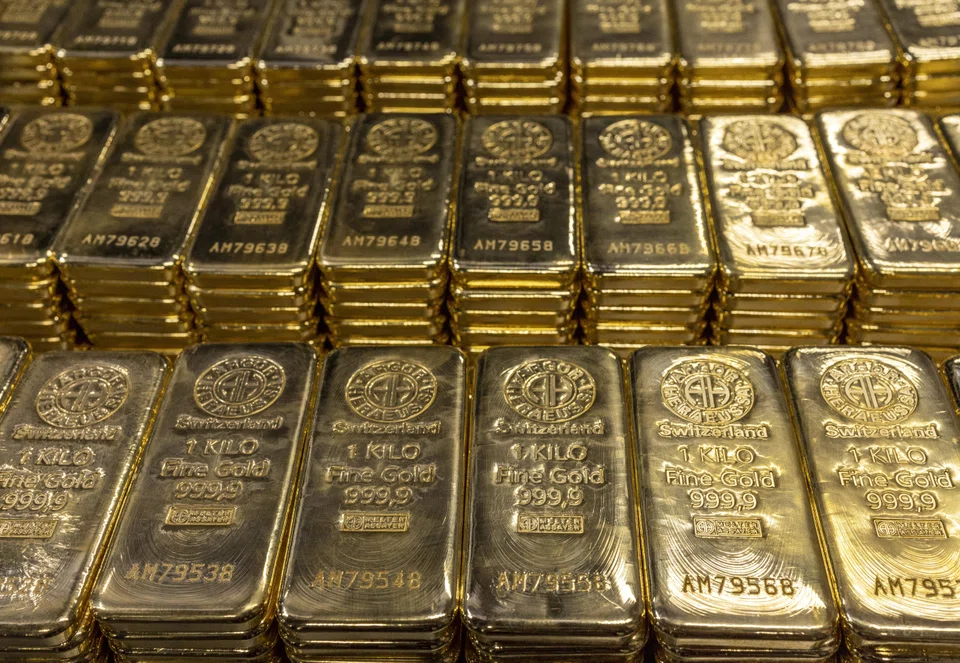
More importantly, gold has consistently traded above CNMC’s H1 2025 average selling price since June 30. In fact, the price of gold has surged to record highs this week of more than US$3,600 per ounce.
Will CNMC’s sustained elevated profitability be sufficient to drive its shares higher? Or, are its shares already close to their peak?
Divergent views on gold
Clearly, a lot hinges on where the price of gold goes from here. The precious yellow metal is often said to be a “safe-haven” asset, and a hedge against geopolitical turmoil and global financial market instability.
Its relevance has been buoyed this year by Trump’s return to office in January, with an agenda that is likely to stretch the US government’s budget deficit and disrupt global trade.
Indeed, there has been a lot of talk recently about US dollar weakness, and central banks increasing their purchases of gold.
Yet, much like other financial assets, gold attracts a lot of speculative interest. This supposed “safe-haven” asset is not just about mitigating risk in an investment portfolio; for some investors, the precious metal offers the potential to drive returns, too.
In recent weeks, The Business Times has published sharply divergent opinions of a number of market watchers. Three weeks ago, for instance, Union Bancaire Privee’s chief strategist Norman Villamin provided a timely and prescient view on why the price of gold was set to push higher.
At the other end of the spectrum, our regular columnist Ken Fisher said earlier this week that many of the arguments usually put forward to own gold are just fiction. The way he sees it, the recent run in the price of gold was due to little more than speculative investor demand.
Some investors might also find it useful to re-read the views Warren Buffett expressed about gold in his 2011 annual letter to shareholders of Berkshire Hathaway, when interest rates were close to zero. In particular, he noted that gold is not a productive asset, unlike farmland or companies such as Coca-Cola or See’s Candies.
Over the long term, productive assets that require minimal capital expenditure, rather than “safe havens” such as bonds or gold, are most likely to keep investors safe from inflation, Buffett said.
What about the possible collapse of the US dollar-based trading system?
“Whether the currency a century from now is based on gold, seashells, shark teeth, or a piece of paper (as today), people will be willing to exchange a couple of minutes of their daily labour for a Coca-Cola or some See’s peanut brittle,” Buffett noted, in his letter.
Gold miners taking off
What does all this mean for CNMC?
While gold may be an unproductive asset, the surging price of the precious metal has made gold miners more productive than ever. With their increased profitability, these companies will be better able to invest in their future growth and efficiency, pursue mergers and acquisitions, and hike their dividend payouts.
In fact, heavyweight gold mining stocks are now performing better than gold itself. The US-listed VanEck Gold Miners ETF (GDX) – which holds stocks such as Newmont, Barrick Mining and Gold Fields – has delivered a year-to-date total return of 97.1 per cent, far outstripping the 38 per cent return chalked up by SDPR Gold Shares (GLD).
GDX returned 10.6 per cent in 2024 and 10 per cent in 2023, lagging GLD’s return of 26.7 per cent and 12.7 per cent for those two years, respectively.
Similarly, CNMC’s total returns of 25.6 per cent in 2024 and 5.6 per cent in 2023 pale in comparison to the 298.2 per cent return it has delivered so far this year.
Besides expanding its production capacity, CNMC distributed a total dividend of S$0.015 per share for H1 2025, comprising a special payout of S$0.011 per share and an interim dividend of S$0.004 per share.
This half-year payout was nearly 29 per cent of its earnings for the period, and more than the S$0.014 per share that was paid out for the whole of 2024.
SAC Capital said in a note dated Sep 3 that it is forecasting earnings per share for CNMC of S$0.103 for 2025, and S$0.12 for 2026. The research house has a target price of S$1.13 for CNMC’s shares, derived by applying a 40 per cent discount to its peer mean price-to-earnings ratio of 18.4 times.
CNMC closed on Wednesday (Sep 10) at S$0.93.
Based on SAC Capital’s forecast 2025 dividend of S$0.035 per share, CNMC has a dividend yield of 3.8 per cent.
Yet, even after its big run, CNMC still has a relatively small market cap of just S$377 million. This could limit its options in pursuing inorganic growth initiatives. The small size of its operations could also mean volatile earnings.
For investors prepared to bet that gold will remain elevated for the next couple of years, perhaps the question is not whether CNMC will continue performing well, but whether it offers the most sensible exposure to the global gold mining sector at this point.






