

Will ESR-Logos Reit cash in on buying interest in short-lease hospitality assets?
Even if the price fetched is below the end-2023 valuation, it may be worthwhile for the Reit to strike a deal for its hotel and convention centre next to Expo MRT station
PROPERTY investors seem to have become more receptive to buying Singapore hospitality and commercial properties on short-land-tenure sites over the past year. This provides an opportune exit for the owners of such properties.
In late 2023, Viva Land sold the former SO/ Singapore hotel on a site in Robinson Road with about 47.5 years’ balance lease. This was sold to a consortium that included the Tan family behind Sunray Woodcraft Construction and Mini Environment Service. Mingtiandi reported the price at around S$170 million to S$180 million.
This year, Paragon Real Estate Investment Trust (Reit) managed to sell The Rail Mall, in Upper Bukit Timah Road, on land with a balance lease of about 21 years and nine months. The Yong family behind Woh Hup Holdings picked up the single-storey strip mall for S$78.5 million.
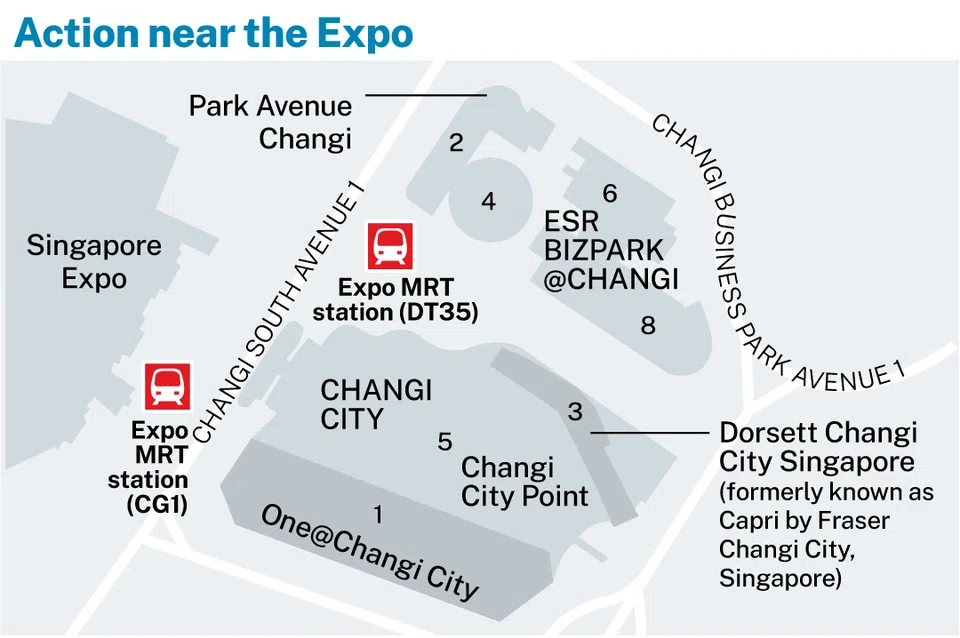
Frasers Property sold the 313-room Capri by Fraser Changi City, near the Expo interchange MRT station, for about S$171.8 million to a consortium comprising family office Atelier Capital Partners Singapore, TPG Angelo Gordon, Heeton Holdings and Far East Consortium International (FEC). The hotel is part of an integrated project on a site with a balance term of about 45 years.
A similar situation may be under way at the integrated development next door, owned by ESR-Logos Reit . ESR BizPark@Changi, formerly known as UE BizHub East, sits on a site zoned as Business Park-White, with up to 40 per cent of the overall gross floor area allowed for “white” uses including shop, restaurant, office or hotel.
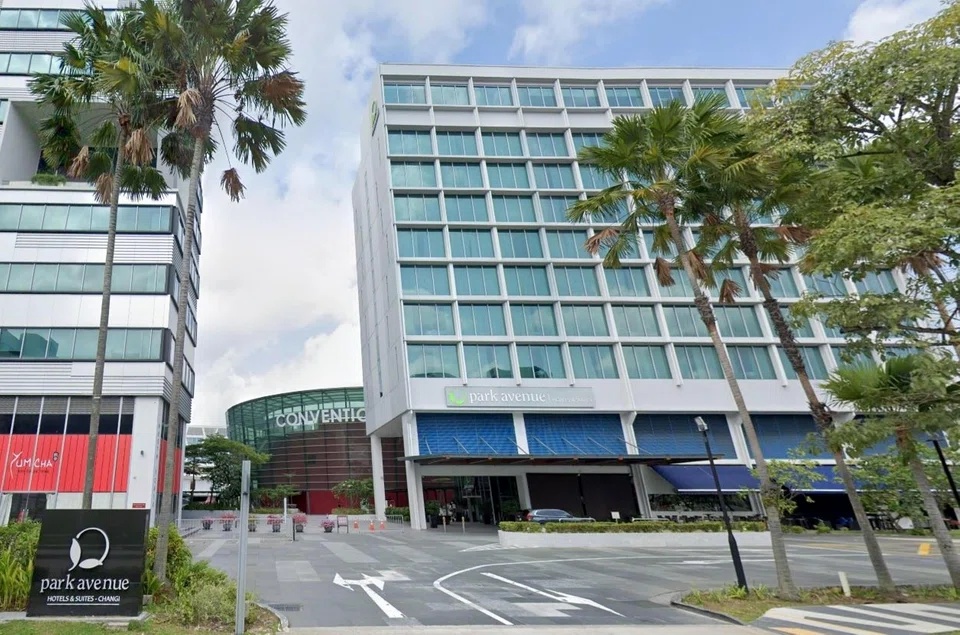
ESR BizPark@Changi comprises two business park buildings (with some retail space), the 251-room Park Avenue Changi hotel, and a convention centre.
Word in the market is that last year, the ESR-Logos Reit appointed JLL to help it find a buyer for the hotel and convention centre. It makes sense for the Reit to dispose of the hospitality portion of the complex as the group’s focus is on industrial real estate assets.
A potential buyer is understood to be doing due diligence on the hotel and convention centre.
According to ESR-Logos Reit’s annual report, the hotel and convention centre in the complex were valued at S$155 million as at Dec 31, 2023. At the time, the remaining land tenure on the site was 44 years and two months.
Two key differences
There are at least two significant differences between the two developments in Changi Business Park.
The Changi City project, developed by the then Frasers Centrepoint and Ascendas Land (Singapore), is on a site awarded by JTC Corporation with a straight 60-year leasehold term from April 30, 2009.
ESR BizPark@Changi was developed by United Engineers (UE) on a site awarded by JTC with a 30-year leasehold term with an option to extend for a further 30 years.
The initial 30-year term kicked in on Feb 1, 2008; this leaves a balance of about 13 years and four months. The option to extend the lease for 30 years will take the lease expiry to Jan 31, 2068; this is expected to entail a substantial land premium payment to JTC.
To recap, UE BizHub East was completed in 2012 and sold by UE to Viva Industrial Trust as part of the stapled group’s flotation on the Singapore Exchange in 2013.
In 2018, Viva Industrial Trust was merged with ESR-Reit. In 2022, ESR-Reit merged with ARA Logos Logistics Trust to become ESR-Logos Reit.
The second difference between the two developments is that the Changi City project is strata titled, which facilitated the sale of the various components in separate deals: One@Changi City (business park), the Changi City Point mall and the Capri by Fraser Changi City hotel.
On the other hand, the whole of ESR BizPark@Changi is still held under a single property title. It is not strata subdivided; the various components do not have their own strata titles.
So how can ESR-Logos Reit dispose of the hotel and convention centre, separately from the rest of the business park complex?
Strata subdivision or plot subdivision?
One possibility could be to propose a strata subdivision to carve out a strata unit for the hotel/convention centre component of the complex, and issue a long lease on the strata unit to match the lease expiry on the site.
There may be another solution: site subdivision.
ESR BizPark@Changi sits on two plots of land. The two business park buildings – at 6 and 8 Changi Business Park Avenue 1 – occupy the smaller plot of nearly 1.2 hectares (ha) and extend to part of the larger plot of 1.7 ha.
The larger plot could be split into two, to separate the hotel/convention centre (at 2 and 4 Changi Business Park Avenue 1) from the business park buildings.
All of these will require approval from the authorities.
Market observers expect ESR-Logos Reit to hold discussions with JTC, the Singapore Land Authority and other government agencies on how to structure a sale, even as due diligence by the potential buyer is ongoing.
ESR BizPark@Changi took its present name following the completion of asset enhancement works in the first quarter of 2021.
Although UE divested UE BizHub East in 2013, it continues to operate the hotel – besides the 251 guest rooms, there are some serviced office suites – and the convention centre under its Park Avenue hospitality brand.
The convention centre has a seating capacity of about 650 people; the single-level facility is suitable for wedding banquets, concerts, conferences, corporate meetings and other events.
Depending on the profile of the buyer, there could be a change in operator. For instance, if the buyer is a co-living operator, it is almost certain to want to manage the hospitality asset itself.
Investment appeal of short-tenure assets with strong cashflow
Despite their relatively short balance site leases, such assets have their appeal to investors. For a start, the absolute price quantum is smaller than if the asset had a much longer or freehold tenure.
This pushes up rental yield.
Investors may be willing to buy a retail or hospitality asset in a prime location with connectivity and generating strong rental cashflow, even if it is on a site with a short balance leasehold tenure.
Some may be looking at holding the property for about five years. Others could be prepared to hold on to the asset for much longer, if their calculations show they can recoup their investment and make a decent return, before the site lease runs out.
Some businesses may also be eyeing a property with a shorter balance site lease to use for their own operations. Or to manage it. A case in point would be Hong Kong-listed FEC’s subsidiary Dorsett Hospitality International (DHI), which took a stake in the consortium that bought the Capri by Fraser Changi City. DHI has been appointed by the consortium to operate the hotel, which has been rebranded Dorsett Changi City Singapore.
For ESR-Logos Reit, it remains to be seen if it can seal a deal to sell the hotel/convention centre of its business park project next to Expo MRT station, the Singapore Expo and in proximity to Changi Airport. Even if the price is below the end-2023 valuation, it would be worthwhile for the Reit to strike a deal and focus on its core industrial property business.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Britain’s mansion tax shows the difficulty of targeting wealth
Three hats, one goal: How Ng Kian Swan runs sustainability at NUHS
COE review: The gap between luxury and mass-market cars isn’t the only one worth bridging

