

Will GE do better as three companies than as one?
How to dismantle an industrial icon
“THE difficulties inherent in such a reorganisation were many and serious.”
That is how in 1893 Charles Coffin, the first chief executive of General Electric (GE), described merging three businesses into what became the iconic American conglomerate. More than 130 years later, Coffin’s latest successor, Larry Culp, must be feeling similarly about doing the reverse.
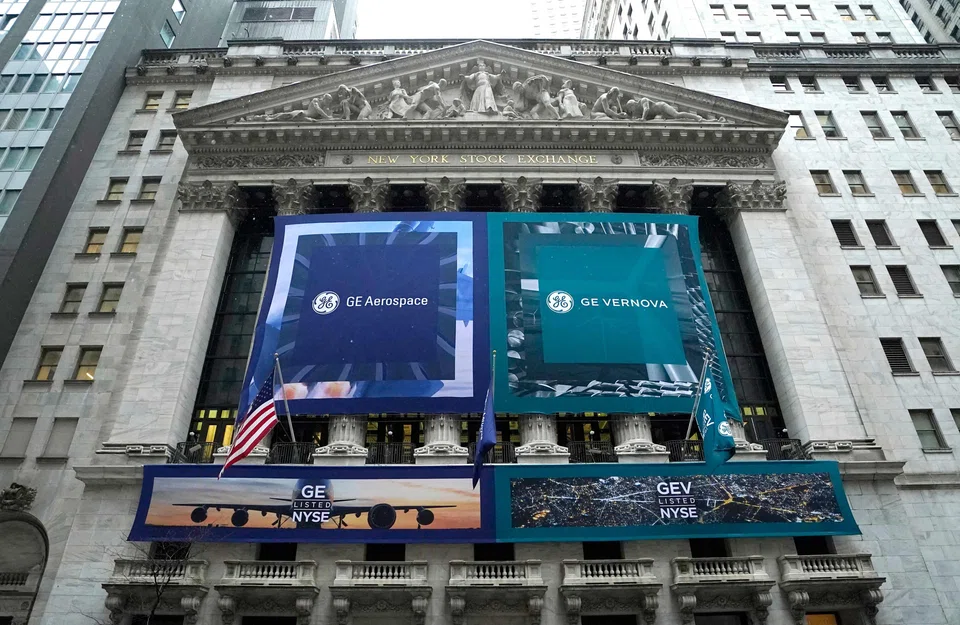
On Tuesday (Apr 2), GE split into two public companies: GE Aerospace, a maker of jet engines, and GE Vernova, a manufacturer of power-generation equipment. A third, GE HealthCare, a medical-devices firm, was spun off in January 2023.
Investors are not mourning the end of GE as they, their fathers, grandfathers and great-grandfathers knew it. On the eve of the split, the company’s market value hovered at nearly US$200 billion – and more than US$230 billion if you add GE HealthCare’s.
In November 2018, shortly after Culp took over as boss, the whole group was worth US$65 billion, the least since the early 1990s. That June, it had been ignominiously kicked out of the Dow Jones Industrial Average (DJIA), an index of American blue chips.
In the past year, both GE and GE HealthCare have handily outperformed the DJIA. Their shares have also done better than those of most American spin-offs. Culp says that the group could not continue as an “all-singing, all-dancing GE”. Instead, GE’s corporate progeny will become less general and, amid the energy transition, more electric.
For much of its history, GE was synonymous with size. Under Jack Welch, the acquisitive CEO who ran it from 1981 to 2001, it became the world’s most valuable company. Subsequent losses at GE Capital, its bloated finance arm, and troubles in its core industrial businesses laid the giant low.
Jeff Immelt, Welch’s successor, sold off GE’s media, home-appliance and, belatedly, finance assets but spent US$11 billion on the ill-timed takeover of a power-and-grid business of Alstom, a French conglomerate, and US$7 billion on a stake in Baker Hughes, a purveyor of oil-industry gear.
John Flannery, who replaced Immelt in 2017, had the idea of spinning off the healthcare division and focusing on GE’s core businesses, aviation and power generation. But he was dumped barely a year into the job, as GE’s share price cratered.
As a result, Culp, the first outsider to run GE, inherited a mess. GE ended 2018 with a US$23 billion write-down of its power business (largely due to the Alstom deal), a US$15 billion capital shortfall in a rump reinsurance business, a net annual loss of US$22 billion and more than US$130 billion in debt.
On paper, his rescue plan looked similar to Flannery’s: hive off health, double down on aircraft engines and power. The way he went about it, though, was different.
He halted his predecessor’s proposed spin-off of the healthcare business, realising that GE would be too weak in the short run to survive without the health unit’s income. Instead, he sold GE’s biotechnology business to his old employer, Danaher, another industrial group, for US$21 billion; accelerated the move towards cleaner energy by divesting the stake in Baker Hughes; and flogged GE’s aircraft-financing unit for more than US$30 billion. He also cut the quarterly dividend from 12 cents a share down to a cent.
Taken together, these moves reduced GE’s debt by some US$100 billion.
Critically, Culp understood that reforming GE required not just changes to its structure but also to its operations.
Six Sigma, a series of techniques championed by Welch that aimed to keep manufacturing defects below 3.4 per million parts, had become a barrier to innovation and was out. Instead, Culp introduced GE to “lean management”, which looks for small changes that add up to big improvements over time.
This approach, pioneered by Toyota in Japan, involves managers solving problems by visiting the factory floor or their customer rather than from the comfort of their desks.
Today, GE executives pepper their disquisitions with Japanese terms such as kaizen (a process of continuous improvement), gemba (the place where the action happens) and hoshin kanri (aligning employees’ work with the company’s goals).
More important, Culp and his underlings routinely spend a week on the factory floor alongside workers. The company credits this system for improvements such as reducing the total distance a steel blade for its gas turbine travels during the manufacturing process from three miles (5 km) to 165 feet (50 metres), and shaving the time to build a helicopter engine from 75 to 11 hours.
This puts the two daughter firms in fighting shape to thrive as their sister, GE HealthCare, has done. In 2023 GE Aerospace and GE Vernova generated combined revenues of US$65 billion, up from US$55 billion the year before. Engines made by GE Aerospace, the group’s most profitable division, which Culp has chosen to run after the break-up, power three-quarters of all commercial flights. GE Vernova’s turbines generate a third of the world’s electricity.
Like many successful managers, Culp also has luck on his side. Demand for passenger jets – and thus the engines that keep them aloft – is rebounding sharply from a pandemic slump. With a backlog of orders until the end of the decade, GE Aerospace expects adjusted operating profit to surge from US$5.6 billion in 2023 to US$10 billion by 2028.
The turbulence at Boeing, which GE supplies with engines for the plane-maker’s troubled 737 MAX planes, means that airlines facing delayed deliveries of these narrow-body workhorses will need to stretch their existing fleet. That, points out Sheila Kahyaoglu of Jefferies, an investment bank, increases demand for GE Aerospace to keep older engines going. Last year, the services business accounted for almost 70 per cent of the division’s revenues.
The winds look equally favourable for GE Vernova. Operating margins in the business rose from low single digits in 2019 to almost 8 per cent in 2023. The International Energy Agency, an official forecaster, estimates that demand for electricity generation will grow by more than half by 2040 as power-hungry data centres and electric cars guzzle more electricity.
America is lavishing subsidies and tax breaks on renewable energy projects. Scott Strazik, a GE veteran who will run GE Vernova, believes that this will help the company attain the scale necessary to spread the high costs of wind-turbine manufacturing, which is still loss-making.
GE’s run of good fortune may not last. Projections for traffic in the notoriously cyclical airline business may turn out to be too rosy. If Boeing doesn’t pull out of its nosedive, GE Aerospace’s order books could take a hit. The transition to clean energy in America, GE Vernova’s largest market, has been fitful even under US President Joe Biden, its climate-friendly president.
Should the carbon-cuddling Donald Trump return to the White House next year, he has vowed to gut green subsidies. GE’s businesses, in other words, face many and serious difficulties ahead. But at least reorganisation is not one of them.
©2024 The Economist Newspaper Limited. All rights reserved
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Income Insurance appoints former Manulife Singapore top man as new CEO

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

